When your belongings arrive scratched, broken, or missing, it can turn an already stressful move into a full-on dispute with the moving company. In the middle of unpacking, you are suddenly forced to document damage, track down receipts, argue about valuation, and meet strict deadlines you may not even know exist.
How you act in the first days and weeks after delivery can dramatically affect the outcome of your moving damage claim. Strong documentation, organized evidence, and clear communication give you leverage. Weak or late documentation, missing paperwork, or casual phone-only complaints can leave you with a low settlement or even a denied claim.
This in-depth guide walks you through the entire process of handling damage, loss, or shortage after a household goods move within the United States. You will learn how to document what happened, interpret your moving paperwork, calculate what you are actually owed under your coverage, respond to lowball offers, and decide when to escalate to a complaint, arbitration, or legal review.
This is general information for consumers using movers in the U.S. Rules can differ for interstate versus local or intrastate moves, and you should always review your bill of lading, tariff, estimate, and any claim form the carrier provides, as well as applicable law in your state.
Key takeaways
- Start documenting damage and missing items immediately at delivery and continue as you unpack. Photos, videos, and inventory notes are your best evidence.
- Review your bill of lading, estimate, and valuation election to understand whether you chose full value protection or released value and how that limits what the mover may owe.
- Most movers require written claims within a specific time window. Confirm deadlines in your paperwork and the carrier's tariff, and submit your claim before the earliest one.
- Organize your claim by item: description, inventory number, condition before and after, value, repair or replacement documentation, and the exact amount you are requesting.
- A polite but firm written record—emails, letters, and claim forms—is more powerful than phone calls alone and is essential if you later escalate to FMCSA, arbitration, or court.
- You can and should respond to low settlement offers with better documentation, clear calculations, and references to your valuation coverage and tariff provisions.
- Escalation options include the mover's internal review, the FMCSA National Consumer Complaint Database for interstate moves, required arbitration programs, state agencies, and small claims court.
Understanding mover liability and valuation
Before you argue about money, you need to understand what the moving company may actually be responsible for under your contract and the law. Household goods carriers are not automatically liable for every dollar of your loss. Their liability is heavily shaped by valuation coverage, exclusions, and your own paperwork.
Valuation vs. insurance
For interstate moves regulated by the Federal Motor Carrier Safety Administration (FMCSA), movers must offer at least two levels of liability: full value protection and a lower released value option (often $0.60 per pound per article). This is valuation, not traditional insurance. It is part of the mover's contractual liability, not a separate homeowner's policy.
If you chose full value protection, the carrier generally agrees (subject to conditions and limits) either to repair the item, replace it with a similar item, or make a cash settlement for the cost of repair or replacement, up to the declared valuation amount. If you signed for the cheaper released value option, the mover's liability may be limited to a small amount per pound, no matter the actual value.
Typical exclusions and limitations
Most tariffs and contracts exclude certain types of damage or limit responsibility. Common examples include:
- Items packed by owner (PBO) where there is no visible damage to the carton at delivery
- Mechanical or internal functioning of electronics with no external damage
- Boxes or items not listed on the inventory (e.g., untagged items)
- Pre-existing damage documented on the inventory or condition reports
- Prohibited items (hazardous materials, perishable goods, etc.)
You need to compare what happened to you with the wording in your bill of lading, estimate, and the mover's tariff or terms and conditions. That understanding will shape how you frame your claim and what you realistically request.
Step 1: Check your moving paperwork
Your paperwork is the foundation of your claim. It describes the agreement, valuation level, and often the deadlines and claim procedure. The claims adjuster will rely on these documents; you should too.
Key documents that matter
- Bill of lading – The main contract for carriage, listing the mover, shipper, origin, destination, valuation election, and basic terms.
- Order for service / written estimate – Shows charges, services, and sometimes valuation options and declared value.
- Household goods inventory – Lists each item or carton with inventory numbers and notations (scratches, dents, worn, etc.). You should have signed copies at origin and destination.
- Delivery receipt – Sometimes integrated into the bill of lading, where you sign at delivery and can note visible loss or damage.
- Tariff or terms and conditions – The mover's rules about liability, claim filing deadlines, repair vs. replacement, and arbitration.
- Claim form – Many carriers require a specific claim form or online portal submission.
What to look for first
- Which valuation level you selected and any dollar amount you declared.
- Any language about the deadline for filing written claims.
- References to an arbitration program or dispute resolution.
- Notes on the inventory regarding pre-existing damage that you disagree with.
- Any notations you made at delivery such as "subject to inspection", "cartons missing", or "obvious damage".
Highlight or mark the paragraphs that deal with claims and liability. Keep copies of all pages in a digital folder so you can quickly quote them in your correspondence.
Step 2: Document damage and missing items
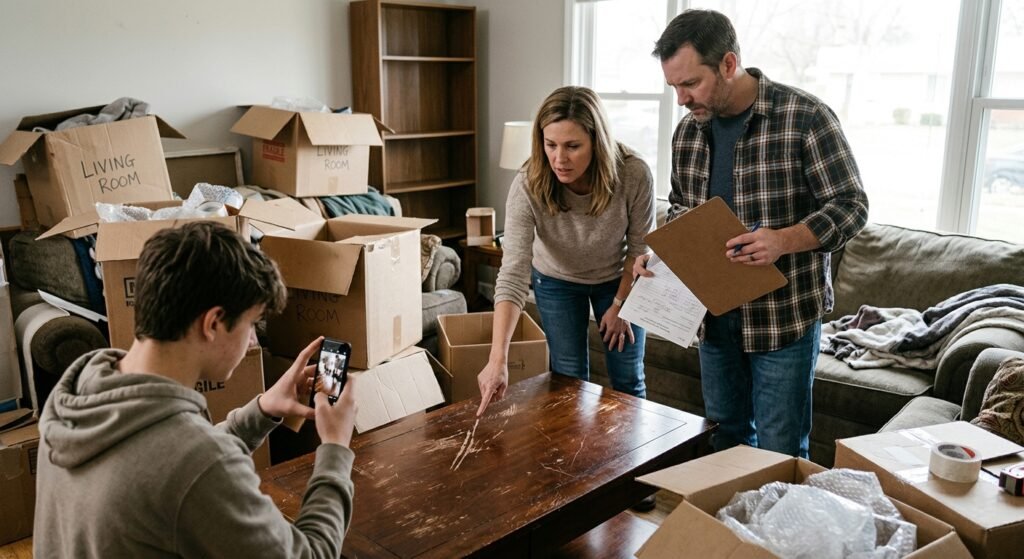
Evidence wins or loses claims. The more clearly you can show the item before the move, during packing or loading, the condition of the box or furniture upon delivery, and the actual damage, the stronger your file.
Photographs and video
Use your phone or camera to capture:
- Wide shots of rooms showing how items were delivered (e.g., crushed boxes stacked in a corner).
- Close-ups of specific damage: scratches, broken legs, cracked screens, torn upholstery, water damage, etc.
- Shots of the item's brand labels, serial numbers, and model numbers where applicable.
- Photos of cartons with visible damage, showing the inventory tag number on the box and any notations.
- Short video clips walking around larger damaged items to show the overall effect.
Delivery receipts and notations
At delivery, you typically sign paperwork acknowledging receipt of the shipment. If you see obvious loss or damage, it is important to note it on the delivery receipt or inventory copies. This does not replace a written claim, but it supports your position that the problem occurred during transit.
If you already completed delivery and did not note anything, do not panic. Many issues are only discovered while unpacking. Continue documenting and prepare to explain in your claim when you first discovered the problem.
Distinguishing types of issues
Your approach may differ depending on whether you are dealing with:
- Visible transit damage – Example: crushed entertainment center, gouged dining table, shattered glass door.
- Concealed damage – Example: electronics that no longer power on, cracked items inside undamaged cartons.
- Loss / missing items – Example: an entire carton missing, or a specific item that appears on the origin inventory but never arrived.
- Shortages within cartons – Example: valuable contents missing from a box with an intact seal.
Note the type for each claimed item in your spreadsheet or claim list. Some tariffs handle concealed damage differently, and missing cartons often require cross-checking inventory numbers.
Step 3: Organize your evidence file
Think of your claim as a small case file. The more organized you are, the easier it is for a claims examiner to understand your position and approve a reasonable settlement. A messy or incomplete file often leads to delays or denials.
Build an item-by-item log
Create a spreadsheet or table listing each damaged or missing item. Include inventory numbers, original value, and supporting documents. Here is an example structure you can adapt:
| Item / Description | Inventory # / Location | Evidence & Documents |
|---|---|---|
| Dining table, solid wood, 6 ft, scratched top | Tag #42, Living Room | Photos before/after; purchase receipt; repair estimate from furniture shop |
| TV, 55" brand/model, cracked screen | Tag #88, Family Room | Photo of damage; serial # photo; replacement price printout |
| Carton "Kitchen 7" missing | Inventory #K7, Kitchen | Copy of inventory showing box loaded; list of contents and values; unpacking notes |
Create a digital folder system
Use folders on your computer or cloud storage to group:
- 01 – Contracts & Forms – bill of lading, estimate, tariff, valuation election, claim form.
- 02 – Photos & Video – subfolders by room or item.
- 03 – Receipts & Proof of Value – purchase receipts, credit card records, screenshots from retailer websites.
- 04 – Repair / Replacement Documentation – estimates from repair shops, written opinions that an item is not repairable, replacement quotes.
- 05 – Correspondence – emails, letters, notes of phone calls with dates and names.
Label files clearly so you can attach or reference them when completing a claim form or writing a demand letter.
Claim deadlines and time limits
Most movers set specific time frames for submitting written claims. Missing a deadline is one of the fastest ways to undermine an otherwise strong dispute.
Where deadlines come from
Deadlines may appear in:
- The bill of lading or order for service.
- The mover's tariff or terms and conditions.
- The claim form or instructions provided by the carrier.
- Federal or state rules (for example, 49 CFR Part 370 discusses processing of claims for interstate carriers, but your contract may still be more specific).
Interstate carriers often require written claims within a certain period from delivery (for example, nine months), but your paperwork controls. Intrastate or local moves may be governed by different state regulations or tariff rules with shorter or longer periods.
Sample timeline of a typical claim
This is an example only; your actual deadlines may differ. Always check your own documents.
| Stage | Approximate Timing | What You Should Do |
|---|---|---|
| Delivery date | Day 0 | Inspect major items, note visible damage or missing cartons on delivery paperwork, start taking photos. |
| Initial documentation | Days 1–14 | Finish unpacking, list all damage and loss, gather receipts and estimates. |
| Claim submission | Before contractual deadline (e.g., within 9 months) | Submit written claim in the format required by the mover, with all supporting documents. |
| Carrier acknowledgment | Within a set period after receipt (varies by tariff / regulation) | Confirm they received your claim; keep any claim number they assign. |
| Settlement / denial | Within their stated time frame to resolve claims | Review their offer or denial, respond with counterarguments or consider escalation. |
If you are close to a deadline and still gathering documents, submit a timely written claim with the best information you have, clearly stating that additional documentation may follow.
How to calculate the amount to claim
To ask for a reasonable settlement, you need a logical calculation behind each dollar you request. The math will depend heavily on whether you chose full value protection or released value (or a different valuation level offered by your mover).
Full value protection scenarios
Under full value protection on many interstate moves, the mover typically has the option to:
- Repair the item,
- Replace it with an item of like kind and quality, or
- Pay you the cost of repair or replacement (subject to limits and deductible, if any).
Your claim should show what you believe is the fair repair cost or replacement value today, backed up with documentation.
Released value calculations
With released value (commonly $0.60 per pound per article for interstate moves), you often must calculate the item's weight and multiply it by the per-pound liability limit. The result can be much lower than the item's market value.
For example, a 20-pound flat-screen TV damaged beyond repair might be limited to 20 lbs x $0.60 = $12.00 if you signed for released value. You may still choose to submit detailed documentation, but you should be prepared for the carrier to apply that liability limit.
Repair, replacement, and depreciation
Many tariffs allow carriers to consider depreciation depending on age and condition, especially when paying cash rather than directly replacing the item. Your job is to document:
- Date of purchase and original price (if known).
- Reasonable current replacement cost for a similar item.
- Why repair is or is not feasible.
- Any unusual factors (collectible, high-end materials, extremely light use).
Here is an example table comparing different valuation outcomes for a single item. This is not a guarantee of how your carrier will calculate, but it illustrates the concepts.
| Item | Scenario | Illustrative Settlement Approach |
|---|---|---|
| Sofa, originally $1,200, 5 years old | Full value protection, torn fabric and broken leg, repairable | Repair estimate $350; mover may choose to pay or arrange $350 repair instead of replacement. |
| Same sofa | Released value at $0.60/lb, approximate weight 150 lbs | 150 x $0.60 = $90 liability limit, regardless of original price. |
| Dining chair, set of 6, one broken | Full value, cannot match single replacement chair | Mover may consider replacing full set or compensating for diminished value under their tariff rules. |
In your claim, clearly state the calculation for each line item, such as:
"Requested amount: $275.00 (repair estimate dated 8/14 from ABC Furniture Repair attached)"
or
"Requested amount: $420.00 (current replacement price for like kind and quality from XYZ Retail, screenshot attached)"
Filing a complete written claim
A written claim is not simply an email saying "my stuff was damaged." Carriers usually expect a fairly detailed description of what is damaged or missing, how it was damaged, and the amount you are requesting. For many interstate carriers, claim procedures reference federal guidance such as 49 CFR Part 370, but your contract and tariff control.
Follow the mover's required process
Check whether your mover:
- Requires use of a specific claim form (paper or online).
- Accepts claim details by email with attachments.
- Needs original documents mailed or scanned.
- Has different addresses for customer service versus claims.
Carefully follow their instructions and keep proof of submission (email sent receipt, certified mail return receipt, screenshot of online submission confirmation).
Build a clear written narrative
In addition to itemized data, include a brief narrative explaining the overall situation. Keep it factual, not emotional. Here is a basic structure:
- Date of pickup and delivery.
- Overall condition of shipment upon delivery (e.g., several crushed boxes, visible damage to large furniture).
- When you first noticed specific damages or missing items.
- A short summary of the most significant items and your total claim amount.
You can insert wording like:
"This claim relates to our household goods shipment transported by your company from Austin, TX to Raleigh, NC with pickup on May 10 and delivery on May 18 under bill of lading number 123456. Upon delivery and during unpacking over the following week, we discovered multiple damaged and missing items as detailed in the attached list and supporting documents."
Attach supporting documentation
Do not rely on the carrier to ask you for missing documents. Attach everything you have up front, including:
- Photos and videos (labeled or referenced in your list).
- Repair estimates and written opinions from professionals.
- Purchase receipts, order confirmations, or credit card statements.
- Printouts showing current replacement prices.
- Copies of relevant pages from the inventory and bill of lading.
- Any delivery notations or emails already exchanged with the mover.
Keep the originals in your records. Send only copies or digital files unless otherwise required.
How movers and adjusters typically respond
Once your claim is submitted, the mover or its third-party claims company will review your file. Understanding what they are looking for can help you anticipate questions and respond effectively.
What the carrier evaluates
Adjusters usually consider:
- Was the claim submitted on time according to the contract?
- Does the damage appear transit-related versus pre-existing?
- Is there adequate documentation of the item's condition and value?
- Is the claimed amount consistent with the selected valuation level?
- Are there any exclusions that may apply (e.g., PBO cartons, prohibited items)?
They may contact you for more information, request an inspection, or ask you to obtain additional repair estimates.
Possible outcomes of the initial review
| Outcome Type | What It Means | Your Next Step |
|---|---|---|
| Full approval | Carrier agrees to pay the full amount you requested or to repair/replace items accordingly. | Confirm the details in writing; ask about payment timing or repair arrangements. |
| Partial approval / low offer | Carrier offers less than requested, citing reasons such as depreciation, liability limits, or insufficient proof. | Review their reasoning, gather counter-evidence, and respond in writing if you disagree. |
| Denial | Carrier denies all liability for specific items or the entire claim, usually citing contract language or lack of evidence. | Carefully read the denial, check your paperwork, and consider appeal, complaint, arbitration, or legal review. |
Do not accept or cash a payment that you believe is unfair without reading the accompanying letter. Some settlement checks or releases may state that acceptance means full and final settlement of your entire claim.
Handling low settlement offers
Low or partial offers are common. The key is responding with facts, not frustration. A well-organized counter can lead to a better outcome.
Understand their reasoning
Carriers may reduce or deny parts of your claim because they believe:
- The item had pre-existing damage noted on the inventory.
- The item was owner-packed and the carton showed no visible damage.
- The claimed value is not supported by receipts or reasonable replacement prices.
- The item is subject to the per-pound liability limit under released value.
- The damage is cosmetic or minor compared to the requested amount.
Read their letter or email carefully and list each reason they give. Then respond point by point.
Prepare a structured counter
When you disagree, send a written response that:
- Thanks them for the offer but clearly states you are not accepting it as full and final settlement.
- Identifies the specific items or parts of the offer you dispute.
- Provides additional documentation or explanation.
- References relevant contract language or valuation coverage when helpful.
For example:
"Regarding Item 4 – 55" television (Inventory #88), your letter states this item is covered only at $0.60 per pound under released value. However, our bill of lading and order for service, copies attached, show that we elected full value protection with a declared value of $75,000. Based on the attached replacement quote, we continue to request $420.00 for this item."
Stay professional; assume your letter may be read later by an arbitrator, regulator, or judge.
Common mistakes and how to avoid them
Certain missteps can seriously weaken your position. Being aware of them early can help you steer clear.
Mistake vs. better practice
| Common Mistake | Why It Hurts You | Better Practice |
|---|---|---|
| Only calling the mover, no written claim | You may miss contractual deadlines and have no record of what was reported. | Follow phone calls with detailed email or letter and file a formal written claim as required. |
| Throwing away damaged items too soon | Carrier may want inspection; without items, they can dispute your description. | Keep damaged items until the claim is resolved or the mover says in writing you may discard them. |
| Accepting a low check marked "full settlement" without reading | Cashing it may waive your right to seek more. | Review all language first; if unclear, ask the carrier in writing whether it is a partial or full settlement. |
What not to sign or say too early
- Do not sign any "release" or "settlement" form until you understand exactly which items and amounts it covers.
- Do not state that everything arrived "in perfect condition" on the delivery receipt if you have not inspected at least the major items.
- Avoid exaggerating losses or guessing about values. Stick to what you can document.
Escalation options: complaints, arbitration, court
If you cannot reach a resolution with the carrier, you may have escalation options. The appropriate path depends on whether your move was interstate or intrastate/local and on the terms in your contract.
Internal appeal or supervisor review
Before going outside, consider asking for a supervisor review. Send a concise letter or email referencing your claim number, summarizing the unresolved issues, and attaching your strongest supporting documents. Sometimes a second-level review produces a better offer.
FMCSA complaint (interstate moves)
For interstate household goods moves, you can submit a complaint to the Federal Motor Carrier Safety Administration through its National Consumer Complaint Database. While FMCSA typically does not resolve individual money disputes, your complaint may prompt the carrier to respond, and it helps regulators monitor patterns of behavior.
Required arbitration programs
Many interstate carriers are required to offer an arbitration program to resolve certain disputes about loss and damage. Your bill of lading or tariff should describe whether arbitration is mandatory or optional, cost-sharing arrangements, and which kinds of disputes qualify.
Before requesting arbitration, review the program rules carefully, including filing deadlines, fees, and whether decisions are binding.
State agencies and small claims court
For intrastate or local moves, your state public utilities commission, consumer protection office, or similar agency may oversee movers and offer complaint processes. In some situations, consumers pursue claims in small claims court, especially where the disputed amount is within the court's limit and arbitration is not mandatory.
Because procedures and rights vary widely by state and situation, you may wish to consult with an attorney or your state consumer-protection agency before choosing this route.
Interstate vs. intrastate and local moves
Not all moves follow the same rules. Understanding the type of move you had helps you locate the right protections and agencies.
Interstate moves
Interstate moves cross state lines and are generally regulated by FMCSA. For these moves:
- Carriers must provide the "Your Rights and Responsibilities When You Move" booklet or its digital equivalent.
- Valuation options like full value protection and released value must be offered.
- Carriers typically participate in an arbitration program for certain disputes.
Intrastate and local moves
Moves that occur entirely within one state (including local moves within a city or region) are usually regulated by state law and state agencies. Differences can include:
- Different required valuation levels or liability limits.
- Different claim deadlines and forms.
- State-specific complaint and enforcement processes.
Check your mover's license information and your contract to confirm whether your shipment was handled under interstate or intrastate authority. Then consult your state transportation or consumer-protection agency for additional guidance on rights and procedures.
Special situations: high-value, heirlooms, and packing
Certain types of items often lead to more complicated disputes. Planning and documentation matter even more for these categories.
High-value and extraordinary items
Many tariffs require "high-value" or "articles of extraordinary value" (often defined by a dollar amount per pound or per item) to be listed separately on a high-value inventory form. If such items are not declared, the carrier may limit liability even under full value protection.
If your claim involves jewelry, fine art, antiques, collectibles, or high-end electronics, gather:
- Appraisals or valuation reports where available.
- Purchase invoices or auction records.
- Any high-value forms you completed with the mover before the move.
Heirlooms and sentimental items
Claims for sentimental value are difficult because tariffs typically compensate based on market value, not emotional importance. Focus your documentation on objective value (materials, craftsmanship, comparable items) rather than sentimental value alone.
Packed by owner (PBO) cartons
Items you packed yourself are often treated differently. If the box shows no external damage, carriers may argue they are not responsible for internal breakage because they did not control the packing method.
To strengthen PBO-related claims:
- Show photos of intact condition before packing if you have them.
- Document any signs of rough handling (crushed corners, torn tape, etc.).
- Note if the movers repacked or re-sealed any cartons at origin.
Sample wording for letters and emails
You do not need to be a lawyer to write effective letters. Clarity, organization, and a professional tone go a long way. Below are some sample phrases you can adapt to your situation.
Initial written claim cover letter
"Re: Claim for loss and damage – Bill of Lading #123456
Dear Claims Department,
This letter accompanies our formal claim for loss and damage to our household goods shipment transported by your company from Denver, CO to Tampa, FL, with pickup on June 2 and delivery on June 9, under bill of lading number 123456.
During delivery and subsequent unpacking, we identified multiple damaged and missing items, which are listed on the attached claim form and spreadsheet. For each item, we have included a description, inventory number, type of damage or loss, claimed amount, and supporting documentation such as photos, receipts, and repair estimates.
Based on our review of the bill of lading and valuation election, we understand that our shipment was transported under full value protection. Our total claimed amount is $3,485.00, as detailed in the attachments.
Please confirm receipt of this claim and advise if any additional information is needed for your review.
Sincerely,
[Name]
Response to a low settlement offer
"Thank you for your letter dated September 12 outlining your proposed settlement of our claim number 78910. We appreciate your review; however, we are unable to accept the offer as full and final settlement because several items remain undervalued or unresolved.
Specifically:
- Item 2 – Bedroom dresser (Inventory #31): Your offer of $75.00 appears to be based on released value at $0.60 per pound. Our bill of lading (copy enclosed) shows that we elected full value protection. Attached is a repair estimate of $260.00 from XYZ Furniture Repair, which we believe is a reasonable measure of our loss.
- Item 5 – Missing carton "Office 3" (Inventory #O3): The denial letter states there is no record of this carton being loaded. However, the origin inventory (page 4 attached) lists item O3 as loaded, and we documented its absence on the delivery receipt. We are re-submitting our itemized list of contents and values.
We respectfully request that you reconsider these items in light of the attached documentation and provide an updated settlement offer."
Quick checklists you can use
Delivery-day checklist
- Have copies of your bill of lading and inventory on hand.
- As items come off the truck, check inventory tag numbers and obvious damage.
- Set aside visibly damaged cartons or furniture for extra photos.
- Note missing cartons or major damage on the delivery paperwork before signing.
- Take photos of truck position, access issues, and any incidents (e.g., dropped boxes) if they occur.
Claim preparation checklist
- Confirm your deadline for written claims from the bill of lading and tariff.
- List each damaged or missing item in a spreadsheet with inventory number.
- Gather at least one piece of proof of value for each item (receipt, statement, or replacement price).
- Obtain repair estimates where appropriate.
- Write a short narrative summarizing the shipment and the problems.
- Prepare digital copies of all documents for submission.
Evidence organization checklist
- Create separate folders for contracts, photos, receipts, estimates, and correspondence.
- Name photo files with item names and inventory numbers (e.g., "DiningTable_Tag42_after.jpg").
- Keep an index listing which files support which claim line item.
- Record dates and names for all phone calls with the mover.
- Back up your claim folder in the cloud or on an external drive.
Escalation readiness checklist
- Have copies of all claim submissions and carrier responses.
- Confirm whether arbitration is mandatory or optional under your contract.
- Check FMCSA and your state agency websites for complaint procedures.
- Calculate the amount still in dispute after any partial payments.
- Consider consulting with a consumer-law attorney or legal aid if the dispute is significant.
Frequently asked questions
How long do I have to file a moving damage claim?
Deadlines vary. Many interstate movers require written claims within a specific period from delivery (often measured in months), but your bill of lading, tariff, and claim instructions control. Check those documents immediately and submit your claim before the earliest stated deadline.
Do photos really matter for a moving claim?
Yes. Clear photos and videos are some of the strongest forms of evidence. They help show that the damage is recent, the severity of the problem, and whether the box or furniture appears to have been mishandled.
What if I did not notice damage until weeks after delivery?
Concealed damage is common, especially inside cartons. Document what you found as soon as you discover it and still file a written claim within the contractual deadline. Be prepared to explain when and how you discovered the damage.
Can I file a claim if I packed my own boxes?
Generally yes, but claims for items packed by you are harder to prove, especially when the carton looks undamaged. You will need strong evidence that the damage was due to transit handling rather than packing, and the carrier may rely on contract language that limits liability for PBO cartons.
What if the mover lost an entire box?
A missing carton is typically treated as loss. Cross-check the inventory to confirm it was loaded, note that it never arrived, and list the contents and values in your claim. Supporting documents such as receipts or photos of contents before packing are helpful.
Should I cash a settlement check if I disagree with the amount?
Read the accompanying letter and any wording on the check carefully. If it indicates "full and final settlement," cashing it may waive your right to pursue more money. Ask the mover in writing whether the payment is partial or final before depositing it.
Can I still sue the moving company if arbitration is in my contract?
Many interstate moving contracts require or strongly favor arbitration for certain disputes. Whether you can still file in court, and under what conditions, depends on the specific arbitration clause and applicable law. Consider getting legal advice if the amount is significant.
Will my homeowner's insurance cover moving damage?
Some homeowner's policies offer limited coverage for property in transit, but many exclude or restrict it. You would need to review your policy or speak with your insurance agent. Insurance coverage, if available, is separate from the mover's contractual liability.
Do I need a lawyer to file a moving claim?
Most consumers handle the initial claim process without an attorney. However, if the disputed amount is large, the issues are complex, or you are considering arbitration or court, consulting with a lawyer familiar with consumer and transportation law can help you understand your options.
What happens if I miss the claim deadline?
If you miss a clearly stated contractual deadline, the carrier may deny your claim on that basis alone. In some cases you may still try to negotiate, complain to regulators, or seek legal advice, but your position is generally weaker once a deadline has passed.
Official sources & further reading
- FMCSA Protect Your Move – Official consumer information on interstate movers
- FMCSA National Consumer Complaint Database – File an interstate moving complaint
- 49 CFR Part 370 – Principles and practices for the investigation and voluntary disposition of loss and damage claims
- 49 CFR Part 375 – Transportation of household goods in interstate commerce; consumer protection regulations
- State public utilities commissions or consumer-protection offices – For intrastate and local move rules and complaint procedures (see your state government website).
- Your bill of lading, order for service, and the mover's tariff or terms and conditions – Primary sources for your specific claim deadlines and valuation rules.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.