When your delivery finally arrives and you spot scratched furniture, crushed boxes, or missing items, you do not just have a mess to clean up. You have a potential claim that will live or die based on how strong your claim file is. What you document in the first days, how you organize it, and how clearly you present your losses will shape the outcome far more than what you say on the phone.
Carriers, adjusters, and third-party claim companies review hundreds of files every month. Weak files with missing paperwork, vague descriptions, and no valuation support usually end in low offers or denials. Thorough, organized, fact-based files are far more likely to get serious consideration. You cannot control the mover, but you can control the quality of your documentation.
This guide walks you step-by-step through building a strong moving damage claim file: what documents matter, how to photograph and list damages, how to calculate the dollar amount you are claiming, how to present evidence, and how to respond when the mover pushes back or makes a low offer. It is written for interstate and local household-goods moves in the United States, with references to federal rules where they apply.
Regulations and deadlines can vary by state and by move type (interstate, intrastate, local, international, military, or corporate). Always check your bill of lading, tariff, estimate, and claim form for specific requirements, and consider speaking with a qualified attorney or your state consumer office for legal questions.
Key takeaways
- Your claim file should tell a clear story: what happened, what is damaged or missing, what it was worth, and what you are asking the mover to pay under the coverage you chose.
- Key documents include the bill of lading, inventory, estimate, delivery receipt, valuation election, photos, receipts, and written repair or replacement estimates.
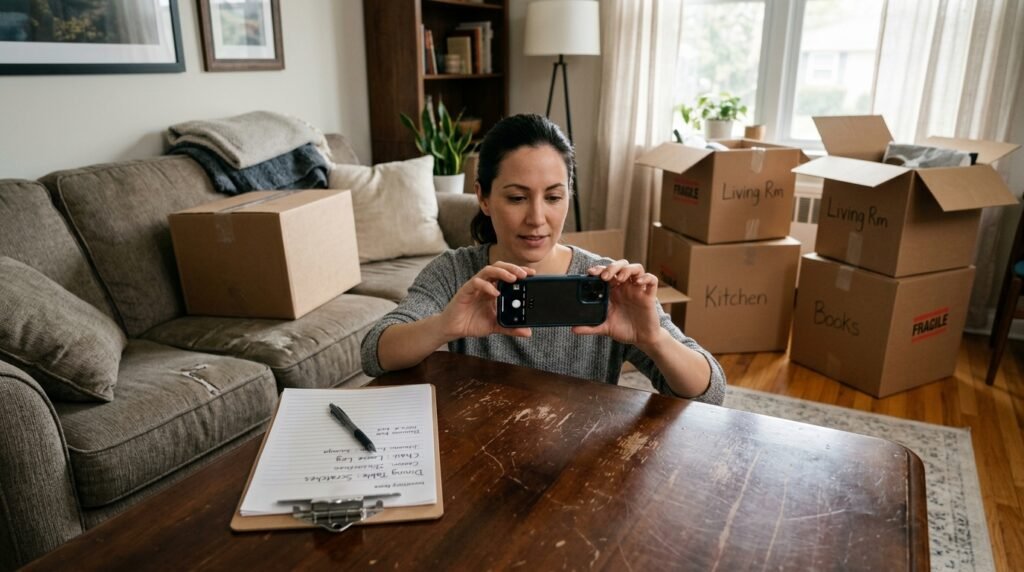
- Take dated, close-up and wide-angle photos, and note damage directly on the delivery receipt or inventory when possible before the crew leaves.
- Always calculate and present a specific dollar amount per item, supported by receipts, online replacement links, or professional estimates, instead of a single vague total.
- Understand whether you selected full value protection, released value (60 cents per pound), or another option, because this changes how much you can realistically recover.
- Keep your communication written, organized, and calm; attach evidence and reference item numbers so adjusters can easily verify your claims.
- If you receive a low offer or denial, you can usually submit a written dispute with added evidence, and, for many interstate moves, pursue arbitration or regulatory complaints.
Why your claim file matters more than your story
Most consumers describe their move with frustration and emotion: the late arrival, the rushed crew, the gouged furniture. While your experience matters, what typically drives claim outcomes is not the story itself, but the evidence you attach and how clearly you present it.
Claim departments and third-party administrators follow internal guidelines, tariffs, and federal or state rules. They often rely on checklists and software that look for specific things: item numbers, model details, photos, receipts, weight, age, and valuation type. If your file is missing these details, the default answer tends to be a low number or no payment.
Think of your moving damage claim file as a small case file. It should make it easy for a stranger who was not at your move to see:
- What was moved and under what contract.
- When pickup and delivery occurred.
- What condition items were in before and after the move.
- Exactly which pieces are damaged or missing.
- How you arrived at each claimed dollar amount.
- Why, under the chosen valuation, the mover should pay that amount.
Understanding mover liability and limits
Before spending hours on spreadsheets and photos, you need a basic understanding of how movers are usually liable. Liability is rarely unlimited. It often depends on federal rules, state laws, and your own choices on valuation forms.
Interstate vs. intrastate and local moves
For interstate moves (state to state) by licensed household-goods carriers, federal law and regulations under the Federal Motor Carrier Safety Administration (FMCSA) usually apply. These moves often fall under the Carmack Amendment and regulations in 49 CFR Part 370 and Part 375.
For intrastate or local moves within one state, state laws, public utilities commission rules, or consumer-protection statutes may control. Some states closely follow federal rules; others do not. Your bill of lading and tariff will often explain which rules apply.
Common valuation options
Movers typically offer at least two valuation options for household-goods shipments. These are not the same as insurance; they are levels of carrier liability:
- Released value (60 cents per pound per article) – Often the default on interstate moves if you do not pay extra. The mover's maximum liability is usually 60 cents times the weight of the item, regardless of its real value.
- Full value protection (FVP) – A higher level of liability, usually for an additional fee. The carrier typically agrees to repair, replace, or pay the current market replacement value of items, subject to limits, deductible, and exclusions.
Other options can include third-party insurance, special high-value inventories, or state-specific valuation types. Always review the valuation election form you signed.
| Valuation type | How liability is calculated | Example outcome |
|---|---|---|
| Released value (60 cents per lb) | Weight of item x $0.60, regardless of purchase price or brand. | 50 lb TV crushed: 50 x $0.60 = $30 maximum payment. |
| Full value protection (FVP) | Repair cost, replacement with similar item, or cash payment of current replacement value, subject to limits/deductible. | Same 50 lb TV crushed: cost to replace with similar model, minus any deductible. |
| Third-party insurance | Depends on insurance policy terms; can cover gaps in carrier liability. | May pay more than carrier liability, but involves separate insurer. |
Knowing your valuation type helps you set realistic expectations and tailor your file. If you are under released value, your focus is proving that damage occurred in the mover's custody and documenting weight. Under full value, you must support the cost to repair or replace.
Documents you need in every claim file
A strong claim file starts with core paperwork. If you are missing these documents, ask the mover in writing for copies. Many carriers keep electronic versions that can be emailed.
Core move documents
- Bill of lading (BOL) – The primary contract for your shipment, showing parties, dates, origin, destination, valuation selected, and basic terms.
- Order for service / written estimate – Shows estimated charges, services, packing, and any special conditions.
- Tariff or terms and conditions – Often referenced in the BOL or estimate; describes claim processes, deadlines, and limitations.
- Household goods inventory sheets – List of items loaded, often with pre-existing condition codes and item numbers.
- Weight tickets (for interstate or weight-based moves) – Document the shipment weight, sometimes relevant to valuation.
- Valuation election form – Shows which liability level you selected and any deductible.
- Delivery receipt / household goods descriptive inventory sign-off – Shows delivery date and any exceptions or damage notations you made at delivery.
Evidence and value documents
- Photos and videos – Before and after, close-up and room views, showing context and detail.
- Receipts or invoices – For major items, including electronics, furniture, and appliances, showing purchase price and date.
- Bank or credit card statements – When receipts are missing, sometimes acceptable as secondary proof.
- Repair estimates – From furniture repair shops, appliance technicians, or specialized professionals.
- Online replacement listings – Product pages from reputable retailers showing current price for similar items.
- Correspondence with the mover – Emails, letters, and messages about delays, shortages, or visible damage.
- Mover claim form – Many companies require use of their form or online portal; keep a PDF or screenshots of what you submit.
| Document | Why it matters | Where to get it |
|---|---|---|
| Bill of lading | Proves contract terms, dates, and valuation choice. | Your move folder or request from mover's office. |
| Inventory sheets | Shows what was loaded and item numbers tied to damage. | Given at load/delivery; ask for scanned copy if lost. |
| Photos/videos | Visually proves new damage or missing boxes. | Your phone, camera, or cloud backup. |
| Repair estimates | Supports the amount you are claiming for repairs or replacement. | Local repair shops or online service providers. |
Documenting damage and loss step-by-step
Strong documentation starts the moment you see something wrong. While you can still file if you noticed issues later, the longer you wait, the easier it is for a carrier to argue the damage happened after delivery.
1. Inspect during and immediately after delivery
- Walk through each room as items come off the truck.
- Open boxes that look crushed, torn, or damp.
- Check furniture corners, legs, and glass surfaces.
- Test basic function on electronics and appliances as soon as practical.
If you notice obvious damage during delivery, politely point it out to the driver and request that it be noted on the delivery receipt or inventory.
Sample wording at delivery: “Please note that dresser item #24 has a fresh gouge on the top surface, and box #17 arrived crushed on one side.”
2. Photograph everything carefully
- Take wide shots showing the item in the room and the damage area.
- Take close-ups from different angles, with good lighting.
- Include the inventory tag number in a photo if still attached.
- For missing items, photograph the space where the item was supposed to be and any remaining packaging.
Turn on the date/time stamp feature or make sure your device settings preserve metadata. Back up all photos to cloud storage before you do anything else.
3. Create a damage and loss list
Use a spreadsheet or simple table to list each affected item. Include fields for:
- Item number from inventory.
- Item description (brand, model, size, color).
- Type of issue (damaged, missing, stolen, mechanical failure).
- Description of damage.
- Location in home.
- Purchase date (approximate if needed).
- Purchase price (with proof if available).
- Claimed amount.
- Photo filenames or references.
| Item # | Description & damage | Evidence attached |
|---|---|---|
| 24 | Solid wood dresser, large gouge and deep scratch on top surface; back corner crushed. | 3 photos (24a-24c), purchase receipt, furniture repair estimate. |
| 17 | Medium box marked “Kitchen Glass”; arrived crushed, several glasses shattered. | 4 photos of box and broken contents, Amazon order history screenshot. |
4. Note deadlines immediately
Different movers and jurisdictions set different claim filing deadlines. For many interstate shipments, carriers require written claims within a certain number of months, often nine months, but your documents control. Some state rules or contracts require much shorter deadlines for notifying the company of problems.
- Read the "claims" or "loss and damage" sections of the tariff or terms.
- Check the back of the bill of lading for deadlines.
- Review the mover's website or claim instructions.
Put the earliest deadline on your calendar and aim to submit your initial claim well before that date.
How to organize your evidence so adjusters can follow it
A thick stack of random photos and emails is not persuasive by itself. Adjusters need to match each photo and document to a specific item and claimed amount. The easier you make their job, the less excuse they have to undervalue your losses.
Use a clear folder structure
- Create a main folder named "[Last name] – Move Claim – [Month Year]."
- Create subfolders: Contracts, Inventory, Photos, Receipts, Estimates, Correspondence, Submitted Claims.
- Within Photos, create subfolders for big items (e.g., "Dresser 24," "TV 36") if you have many images.
- Save emails as PDFs when possible, named with the date and subject.
Number and label everything
Use consistent item numbers that match your inventory sheets or your own numbering system if the inventory is unclear. Reference these numbers in your claim form and letters.
File naming examples:
- 24_dresser_damage_photo1.jpg
- 24_dresser_repair_estimate_ABC_Furniture.pdf
- claim_submission_2026-04-10.pdf
Prepare a master claim summary
In addition to your detailed spreadsheet, create a one to two-page summary that:
- Lists total claimed amount.
- Breaks down amounts by category (furniture, electronics, boxes, missing items).
- Explains your valuation type and deductible (if any).
- Highlights especially serious losses (e.g., destroyed sofa, missing jewelry box).
This document will be the first thing many adjusters read. It should reference attached schedules and evidence by name.
| Organization step | Benefit for your claim | What adjuster sees |
|---|---|---|
| Item numbering & labeled files | Makes it easy to verify every photo, receipt, and estimate. | Professional, organized file vs. scattered images. |
| Master claim summary | Gives clear overview of losses and coverage context. | Quick understanding of scope and high-impact items. |
| Separate evidence folders | Prevents "lost" documents or excuses about missing proof. | Easy navigation to support each claimed amount. |
Calculating the dollar amount of your claim
Your claim file should include a clear calculation for each item. Do not simply write "sofa ruined" or "box missing." You need to show how much you seek and why that number is reasonable under your coverage.
Key inputs for each item
- Original purchase price and date (if known).
- Current replacement cost for similar quality (for full value or repair-based claims).
- Weight (for released-value or weight-based limits).
- Age and condition before the move.
- Repair vs. replacement cost, if repair is feasible.
Example calculation methods
| Scenario | Inputs | Claimed amount logic |
|---|---|---|
| Released value, damaged sofa | Weight ~150 lbs; fabric torn, frame broken; purchase price $1,200. | 150 lbs x $0.60 = $90 maximum under released value, regardless of age or original price. |
| Full value protection, broken TV | Purchased 2 years ago for $800; similar model now $650; repair estimate $400. | Claim $400 for professional repair or $650 replacement, depending on policy terms. |
| Missing box of clothes | No box delivered; list of approximate contents and purchase prices totaling $500. | For FVP: claim current replacement value for similar items; for released value: estimate box weight x $0.60. |
Even if you know that released value will severely limit what you can get, you should still document full losses in case of disputes, misclassified valuation, or supplemental coverage.
Depreciation, valuation, and realistic expectations
Under some valuation policies and in many state rules, depreciation (a reduction in value due to age and use) may be applied. Under others, current replacement cost without depreciation is used. Your paperwork will usually state which applies.
Basic depreciation concepts
- Useful life – The number of years an item is expected to last (e.g., 7–10 years for a sofa, 3–5 for a television).
- Age at time of loss – How long you owned it before the move damage.
- Condition – Better-than-average condition may justify lower depreciation; heavy wear may justify more.
| Item | Example original price / age | Illustrative depreciated value |
|---|---|---|
| Sofa | $1,200; 5 years old; useful life 10 years. | Approximately half of original value, if policy allows depreciation. |
| Laptop | $1,000; 3 years old; useful life 4–5 years. | Significant depreciation; adjuster may use current used-market value. |
| Dining table | $800; 8 years old; solid wood, good condition. | Moderate depreciation depending on policy and condition notes. |
Some full value protection plans focus on current replacement cost without depreciation, while others may use formulas. Always read your valuation terms. When in doubt, document both original cost and current similar replacement price, and allow the adjuster to apply any depreciation while you reserve the right to question it.
Sample wording for claim letters and emails
Your written claim notice and follow-up emails should sound factual and organized, not hostile. You can be firm without being abusive. Written communication creates a record you can use later if you need to escalate.
Initial written claim notice
Subject: Formal claim for damage and loss – [Last name] / BOL #[Number]
Dear [Mover or Claims Department],
I am submitting a formal claim for damage and loss related to my shipment moved by your company from [origin city/state] to [destination city/state], picked up on [pickup date] and delivered on [delivery date], under Bill of Lading #[number]. I elected [valuation option, e.g., Full Value Protection with $x deductible / Released Value].
Attached you will find:
- A claim summary listing each damaged or missing item, item number, description, and claimed amount.
- Photos and/or videos documenting the condition of each item and the damage observed.
- Copies of receipts, online replacement listings, and/or repair estimates supporting the claimed amounts.
- Copies of the bill of lading, inventory sheets, and my valuation election.
The total amount claimed is $[total], subject to your review and any applicable deductible. Please acknowledge receipt of this claim and advise if you require any additional documentation. I look forward to your written response within the time frame required by your tariff and applicable regulations.
Sincerely,
[Your name]
[Address]
[Phone / Email]
Response to a low offer
Subject: Response to settlement offer dated [date] – BOL #[Number]
Dear [Claims Adjuster],
Thank you for your settlement letter dated [date]. After reviewing the itemized offer, I believe several items have been undervalued or denied without sufficient explanation.
Specifically:
- Item #24 (dresser): Your offer is $75 based on repair with "touch-up only." The attached professional estimate from [repair company] indicates that structural damage requires more extensive repair totaling $260. Photos 24a–24c show the depth of the damage. I respectfully request that you reconsider this amount based on the attached evidence.
- Item #17 (kitchen box): The claim was denied for "insufficient documentation." I am now providing additional photos and a detailed list of the contents with purchase dates and prices. Please review the updated documentation.
Please issue a revised, itemized offer or provide a written explanation for any continued denials, referencing the specific contract or tariff provisions you rely on. I reserve all rights under applicable law and the governing tariff.
Sincerely,
[Your name]
Common claim file mistakes and how to avoid them
Many consumers unintentionally weaken their own claims. Knowing the most common pitfalls helps you avoid them.
| Common mistake | Why it hurts your claim | Better approach |
|---|---|---|
| Waiting months to inspect items | Mover may argue damage happened after delivery. | Inspect and document as soon as possible after delivery. |
| Submitting only a narrative without evidence | Adjusters need photos, receipts, and itemized amounts. | Attach photos, receipts, and a detailed item list from day one. |
| Accepting rushed or blank forms at delivery | You may miss the chance to note obvious damage on delivery paperwork. | Take a few extra minutes to check for visible damage and write it in. |
| Threatening the mover instead of documenting | Emotional emails do not replace evidence and may stall communication. | Stay factual and focused on evidence, while reserving your rights calmly. |
How movers and claim departments typically respond
Understanding how the other side works helps you anticipate their moves and prepare your file accordingly. Claims are often handled by in-house departments or third-party administrators who follow set procedures.
Typical stages of mover response
- Acknowledgment – A short notice that your claim was received, sometimes with a claim number and an estimated processing time.
- Request for more information – If your file is missing documents or clarity, they may request specific items, such as repair estimates or proof of ownership.
- Inspection or repair offer – For significant damage, they may send an inspector, furniture medic, or technician before making a decision.
- Itemized settlement offer – You should receive a written explanation of payments or denials by item, often with brief reasons.
- Appeal or dispute stage – Some companies formally allow one or more levels of appeal; others simply accept additional information before closing the file.
What they may argue
- Damage was "inherent vice" or due to the item's condition, not handling.
- Packaging was inadequate (especially for owner-packed boxes).
- Item had pre-existing damage as noted on inventory.
- High-value items were not declared separately as required by contract.
- Claimed value exceeds contract limits or valuation.
Your job is to counter these points with clear evidence and references to the actual contract, not just opinions.
Disputing a low settlement offer with evidence
If the carrier sends a low or partial offer, you may be able to improve the result by submitting a structured, evidence-based dispute. Avoid emotional back-and-forth; focus on facts.
Steps to dispute a low offer
- Read the offer carefully, including line-item explanations and references to contract provisions.
- Highlight items with big gaps between your claim and the offer.
- Gather or update evidence (e.g., additional photos, more detailed estimates, comparable replacement items).
- Prepare a short dispute letter referencing specific items and attaching new evidence.
- Request a revised itemized offer or a written explanation under the tariff or valuation rules.
When to compromise vs. escalate
Sometimes the difference between your number and the mover's number is small compared to the time and stress of further escalation. Other times, especially with large or high-value losses, pressing further or exploring arbitration may be worth it. Consider:
- Total claimed amount vs. offer.
- Strength of your evidence on liability and value.
- Deadlines for arbitration or court.
- Fees or costs for arbitration or legal review.
Escalation options: FMCSA, arbitration, and beyond
If negotiations stall, there may be regulatory or dispute resolution paths available, depending on your type of move and the company's policies.
FMCSA complaints (for many interstate moves)
For interstate household-goods moves, you can submit a complaint to the Federal Motor Carrier Safety Administration's National Consumer Complaint Database. While FMCSA generally does not resolve individual money disputes, complaints can trigger contact with the mover and may be considered in enforcement actions.
Arbitration programs
Federal regulations require interstate household-goods carriers to participate in an arbitration program for certain disputes, including some loss and damage issues. The details vary by carrier and arbitration provider, and there may be:
- Caps on the dollar amount that can be arbitrated.
- Filing fees for you and possibly the mover.
- Deadlines measured from the date of the mover's final offer or denial.
Check your bill of lading and the "Your Rights and Responsibilities When You Move" booklet for details on the mover's arbitration program and how to file.
State consumer agencies and small claims court
For intrastate or local moves, or when arbitration is not mandatory or suitable, you may consider:
- Filing a complaint with your state's consumer protection office or public utilities commission (for regulated movers).
- Using small claims court for modest disputes where the court's jurisdiction and rules allow.
- Consulting a private attorney for advice on larger or complex cases.
Always review your contract for any mandatory arbitration clauses or venue provisions, and confirm deadlines before filing any action.
What not to sign or say too early
In the rush of delivery or frustration afterward, you can accidentally sign away important rights or make statements that weaken your position.
Be cautious with releases and "paid in full" language
- Do not sign any document that says "claim settled," "paid in full," or "no damage" unless you fully understand and agree with it.
- If the mover offers a quick cash payment at delivery in exchange for a release, be sure you are comfortable that it covers all damage, including damage you may not yet have discovered.
- Ask for time to review any release language and keep a copy before signing.
Avoid informal verbal agreements that are not documented
Drivers or crew leaders sometimes promise that "the office will take care of it" or "we will fix that later." Assume that if it is not written down and backed by the claims department, it may not happen. Always follow up in writing.
Sample wording:
“During delivery on [date], your driver stated that the damaged table would be repaired at your company's expense. I am confirming that statement in writing and requesting claim instructions so I can provide the necessary documentation.”
Typical claim timeline and follow-up strategy
Every case is different, but many household-goods claims follow a rough pattern from delivery to final decision. Understanding this helps you plan follow-ups without becoming a constant caller.
| Stage | Approximate timing (example) | Your action |
|---|---|---|
| Damage discovery & documentation | Delivery day to 1–2 weeks after delivery | Inspect, photograph, gather receipts, and start your item list. |
| Initial claim submission | Within contract or regulatory deadline (often within months) | Submit written claim with attachments; keep proof of submission. |
| Carrier acknowledgment | Days to a few weeks after claim | Note claim number; ask about typical processing time. |
| Investigation & evaluation | Several weeks to a few months (varies) | Respond promptly to any document requests; consider sending additional evidence if needed. |
| Offer or denial | Within regulatory or contractual decision timeframe, where applicable | Review, compare to your claim, and decide whether to accept, dispute, or escalate. |
Follow up in writing if the company's stated timelines expire without an update. Keep all follow-up emails organized in your correspondence folder.
Quick checklists for a strong claim file
Immediate steps after discovering damage
- Photograph each damaged or missing item from multiple angles.
- Note damage on the delivery receipt if the crew is still present.
- Save all boxes, packing material, and damaged items until the claim is resolved or the mover says otherwise in writing.
- Create an initial damage list with item numbers and brief descriptions.
- Check your bill of lading and valuation election.
- Put claim deadlines on your calendar.
Building your claim file
- Gather the bill of lading, inventory, estimates, and receipts into one folder.
- Create a spreadsheet listing each claimed item and amount.
- Label photo files with item numbers and short descriptions.
- Request at least one repair estimate for major damaged pieces.
- Find online replacement examples for items you cannot repair.
- Draft a short claim summary and cover letter.
Before submitting your claim
- Confirm you included all required company claim forms.
- Check math on your totals and each line item.
- Verify that every claimed item has at least one piece of evidence (photo, receipt, estimate, or inventory reference).
- Save a PDF copy of everything you plan to submit.
- Send by the method required (online portal, email, mail) and keep proof of submission.
When you receive a response
- Compare the offer line-by-line with your original claim.
- Highlight items that were denied or reduced substantially.
- Decide whether to prepare a written dispute or accept as final.
- Mark any arbitration or escalation deadlines on your calendar.
- Keep copies of checks, releases, or final letters in your claim file.
Frequently asked questions
How long do I have to file a moving damage claim?
Deadlines vary by mover, contract, and whether your shipment was interstate or intrastate. Many interstate carriers require written claims within a specific number of months, often around nine months, but your bill of lading, tariff, and claim instructions control. Always check those documents and aim to file as soon as you can.
What if I do not have receipts for everything that was damaged?
You can still file. Use any proof you have, such as bank statements, online order histories, photos of the items in your old home, and current replacement listings from reputable retailers. Explain approximate purchase dates and prices. Receipts help, but they are not always mandatory.
Can I throw away damaged items after taking photos?
It is safer to keep damaged items and packing materials until your claim is resolved or the mover confirms in writing that you may dispose of them. The carrier or its representative may request inspection. If you must dispose of something for safety reasons, document it thoroughly first.
What if my claim is for a missing box that never arrived?
List the box as a separate item, reference its inventory number and description, and create a detailed list of contents with approximate values. Provide any receipts or order histories for higher-value contents. For some valuation types, the carrier may use weight-based limits; for full value protection, replacement value for the contents may apply, subject to terms.
Does full value protection mean I will always get full replacement cost?
Not necessarily. Full value protection generally provides higher coverage than released value, but it often allows the mover to choose between repair, replacement with a similar item, or a cash payment, and it may include deductibles, exclusions, or limits on certain categories. Read the valuation terms you signed to understand how it applies to your claim.
Should I accept a partial settlement check if I disagree with the amount?
Before cashing any check or signing any release, carefully read the accompanying letter. If it states that the payment is "in full and final settlement" of all claims, depositing the check may waive your right to seek more. If language is unclear, ask the mover in writing whether the payment is partial or final and keep their response.
Can I still file a claim if I signed the delivery receipt as "received in good condition"?
Often yes, especially if damage was not visible or discoverable at delivery (such as contents of sealed boxes or internal mechanical damage). You should explain in your claim when and how you discovered the issues and provide strong evidence. However, the mover may use the clean receipt to challenge your claim, so detailed documentation is even more important.
Do I need a lawyer to handle a moving damage claim?
Many consumers handle routine claims themselves using organized documentation. However, if your losses are large, liability is disputed, or you are considering arbitration or court, it can be helpful to consult an attorney familiar with transportation or consumer law in your state. This guide is general information and not legal advice.
What happens if the mover ignores my claim?
If reasonable time passes without acknowledgment or a decision, follow up in writing and reference any deadlines in the applicable rules or tariff. For many interstate moves, you may submit a complaint to FMCSA and, in some cases, pursue arbitration or court, subject to contract provisions and deadlines.
Official sources & further reading
- FMCSA – Protect Your Move (general information on interstate household-goods moves and consumer rights).
- FMCSA National Consumer Complaint Database (portal to file complaints about interstate movers).
- 49 CFR Part 370 (federal regulations concerning the processing of loss and damage claims for interstate carriers).
- 49 CFR Part 375 (federal consumer protection regulations for interstate household-goods carriers).
- Your state's consumer protection agency or public utilities commission website for intrastate moving rules (search by your state name plus "household goods movers regulations").
- The "Your Rights and Responsibilities When You Move" brochure provided by your interstate mover, which explains valuation, claims, and arbitration basics.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.