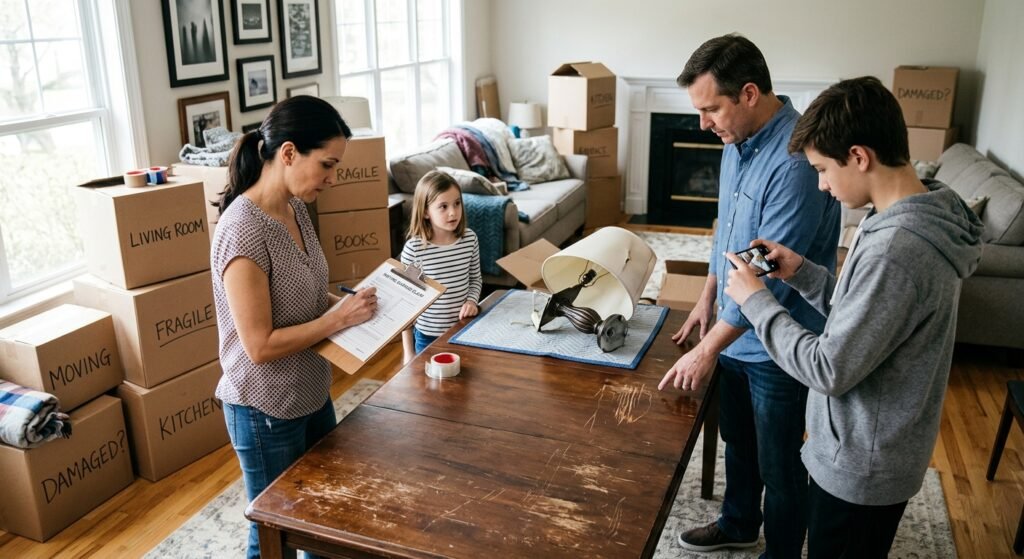
When your belongings arrive damaged, missing, or days late, you are suddenly forced into a process you never planned for: a moving damage claim. Instead of settling into a new home, you are hunting for receipts, taking photos, and arguing over depreciation with a company you may never see again.
What you do in the days and weeks after delivery has a direct impact on how strong your claim file is, how seriously the mover or carrier treats you, and what kind of settlement you may receive. Timing, documentation, and a clear understanding of valuation and liability rules all matter more than most customers realize.
This guide walks you step by step through how to handle a moving damage claim from start to finish. You will learn how to document loss, calculate what to ask for, respond to low offers, and when it may be time to escalate through complaints, arbitration, or court. The goal is not to promise a result, but to help you build a clean, organized file that gives you the best chance of a fair resolution.
Rules can vary depending on whether your move was interstate, intrastate, local, military, corporate, or international. Always review your bill of lading, estimate, tariff, and claim form instructions, and consider speaking with a qualified attorney or your state consumer agency about your specific situation.
Key takeaways
- Act quickly after delivery: note damage on delivery receipts, take photos and video, and gather key paperwork like the bill of lading and inventory pages.
- Your settlement options are limited by the valuation level you agreed to (for example, released value vs. full-value protection) and by federal or state rules.
- A strong claim file pairs clear evidence (photos, estimates, receipts) with an organized damage log that is easy for a claim adjuster to understand.
- Depreciation, repair vs. replacement, and weight-based limits all affect how much you may reasonably claim for each item.
- You do not have to accept the mover's first offer; you can ask for explanations in writing, provide more evidence, and negotiate respectfully but firmly.
- If you cannot resolve the dispute, you may be able to use arbitration, file regulatory complaints, or consider small claims court, depending on your situation.
- Never sign a broad release, cash-out agreement, or "zero damage" delivery receipt until you understand what rights you may be giving up.
Understanding moving damage claims
Before you start gathering photos and estimates, it helps to understand what a moving damage claim actually is and how movers typically handle them.
For most interstate household-goods moves in the United States, the mover's liability for loss and damage is governed by federal law, including the Carmack Amendment and regulations issued by the Federal Motor Carrier Safety Administration (FMCSA). Many states have similar rules for intrastate moves, but details can differ.
In basic terms, a claim is your written demand to the carrier for payment for loss, damage, delay, or other service issues covered by your contract and applicable law. It is not just a complaint; it is a request for compensation, supported by documentation.
Types of problems you can usually claim for
- Furniture scratched, gouged, broken, or water-damaged
- Electronics that no longer work after delivery
- Boxes missing entirely or with missing contents
- Appliances dented or not functioning after the move
- Items delivered late under certain circumstances (delivery delay claims)
- Extra charges that were not agreed to in writing (depending on your contract)
Not every problem is compensable. Damage that clearly existed before pickup, normal wear and tear, or issues caused by your own packing may be excluded or reduced. That is one reason the starting inventory and condition notations matter so much.
Typical deadlines for filing
For many interstate moves, the carrier's tariff may require you to submit a written claim within nine months of delivery. Some intrastate moves and local moves may have shorter deadlines under state law or under the contract you signed. The only way to know is to read:
- The bill of lading
- The mover's tariff or terms and conditions
- Any claim form or instructions provided by the mover
Even if you technically have months, it is much easier to gather evidence and witness statements in the first few days and weeks after delivery, while everything is still fresh and the boxes are not fully discarded.
Documents you need before you start
Strong claims start with strong paperwork. Before you sit down to fill out a claim form or write a demand letter, assemble the core documents you will need throughout the process.
Core moving documents
- Bill of lading (BOL) – Your main contract of carriage. Shows the carrier, dates, basic terms, and often the valuation option you chose.
- Order for service / estimate – Describes the services to be provided and estimated charges.
- Household goods inventory – Lists items and their conditions at origin; often includes condition codes.
- Delivery receipt / household goods receipt – Signed at delivery, sometimes with space to note visible damage or missing items.
- Valuation or protection plan election form – Shows whether you chose full-value protection, released value (for example, $0.60 per pound per article), or another option.
Supporting financial and repair documents
- Original purchase receipts or bank/credit card records (if available)
- Product pages or screenshots showing current replacement cost
- Repair estimates from licensed professionals
- Written opinions from specialists (for high-value items like artwork, pianos, or antiques)
| Document | Why it matters | Where to find it |
|---|---|---|
| Bill of lading | Defines your contract, valuation choice, and key dates. | Given at pickup and/or delivery; email from mover. |
| Household goods inventory | Shows pre-move condition and weights (if listed). | Signed at origin; sometimes also updated at delivery. |
| Valuation election form | Controls maximum compensation method and limits. | Included with estimate or BOL package. |
| Delivery receipt | Records visible exceptions and final delivery date. | Provided at delivery for your signature. |
First steps after delivery
The first 24–72 hours after delivery are critical. You do not have to unpack your entire house immediately, but you should focus on damage detection and basic documentation.
Immediate actions on delivery day
- Walk through your home with the driver or crew leader.
- Identify any obvious damage or missing items while they are still there.
- Note visible damage and missing items on the delivery receipt, including tag numbers when possible.
- Take clear photos and short videos of damaged areas before the crew leaves.
- Do not sign any form stating that everything arrived "in good condition" if that is not true.
Next 2–7 days
- Unpack high-risk items first: electronics, glassware, artwork, fragile items, and anything high in value.
- Keep all packing material, boxes, and labels for damaged items until your claim is resolved or the mover tells you in writing that you may discard them.
- Start a written damage log, listing item description, inventory tag number, room, and type of damage.
- Check your mover's claim instructions and calendar all stated deadlines.
Documenting damage and loss
Evidence is the backbone of any moving damage claim. You do not need to be a professional photographer or appraiser, but you do need to be thorough and organized.
Photos and video: what adjusters want to see
- Wide shots that show the entire item in context (for example, the whole dresser in the bedroom).
- Close-ups of the specific damage (scratches, cracks, dents, broken legs, torn fabric).
- Multiple angles if damage is subtle or in a hard-to-see location.
- Photos of the box, label, and packing materials for damaged boxed items.
- Short videos turning the item or opening and closing moving parts (drawers, doors) when relevant.
Creating a damage inventory log
Create a simple spreadsheet or table listing each affected item. Include:
- Item description (for example, "Ashley dark brown leather sofa")
- Inventory tag number (if any)
- Room and box number (if relevant)
- Type of damage (broken leg, torn arm, missing cushion)
- Replacement value or repair estimate
- Link to photos or file names
| Item | Damage description | Evidence attached |
|---|---|---|
| Leather sofa, tag #123 | Right arm torn, backrest puncture, wood frame cracked underneath. | 5 photos, 1 video, receipt, repair estimate. |
| 55" Samsung TV, tag #245 | Will not power on; screen lines; packed by mover. | 4 photos, video of power-up attempt, online price screenshot. |
| Medium box #M-19 (kitchen) | Missing box; never delivered. | Copy of inventory; annotated unpacking checklist. |
Handling missing boxes and items
For missing boxes or items, documentation focuses on proving that the item was tendered to the mover and not delivered.
- Identify the original inventory number and description if possible.
- Note any special labels like "High Value" or "Packed by Owner".
- Confirm with everyone in your household that it was not misplaced during unloading.
- Document your unpacking process and which boxes you opened.
Valuation and mover liability basics
One of the most confusing parts of a moving damage claim is why a mover offers far less than what you think an item is "worth." In many cases, it comes down to the valuation level you selected and how liability is limited.
Common valuation options
Interstate carriers must offer at least two main levels of liability. Names and details may vary, but the concepts are similar:
- Released value protection – This is often the default, low-cost option. Liability is limited (for example, to $0.60 per pound per article) and is not based on replacement cost.
- Full-value protection (FVP) – Higher level of protection, usually for an additional fee. The mover may repair the item, replace it with an item of like kind and quality, or pay you the cost of repair or replacement up to a certain dollar-per-pound minimum or total declared value.
- Third-party insurance – Some consumers buy separate insurance from a third-party provider. Claims against that policy are separate from the mover's own liability.
Your bill of lading and valuation election form should state which option applies. If you are not sure, ask the mover for a copy in writing.
| Valuation type | How payment is calculated | Typical impact on settlement |
|---|---|---|
| Released value (e.g., $0.60/lb) | Weight of item x cents per pound, regardless of market value. | Low payments for light but expensive items (electronics, decor). |
| Full-value protection | Repair, replacement, or cash, subject to caps and exclusions. | Closer to actual loss, but may still be reduced by depreciation. |
| Third-party insurance | According to separate policy terms and coverage limits. | Can fill gaps but usually requires separate claim process. |
Depreciation and "like kind and quality"
Even with full-value protection, you are usually not entitled to brand-new replacements for old items without considering age and condition. Many carriers apply depreciation, reducing the value based on years of use and remaining useful life.
If your five-year-old sofa was damaged, a settlement based on a reasonable depreciated value is more common than paying the full cost of a brand-new sofa. Your job is to propose values that are realistic but not artificially low.
Calculating your claim amount
Once you have your damage log and understand your valuation level, you can estimate what to actually request in your moving damage claim. This is often where consumers either overreach or undersell their position.
Repair vs. replacement
For each item, ask:
- Is it reasonably repairable to a similar appearance and function?
- Would repair cost more than replacement value, considering depreciation?
- Would repair leave obvious defects or safety issues?
Carriers often choose the lower of repair or replacement. Providing a repair estimate from a local professional can help you avoid a low flat offer that does not reflect real costs.
Example calculation approaches
| Scenario | Calculation method | Illustrative outcome |
|---|---|---|
| Released value, broken 40 lb TV | 40 lbs x $0.60/lb = $24 maximum liability (if that is your tariff rate). | Even if TV costs $500, settlement may be about $24. |
| FVP, 6-year-old sofa, repairable tears | Local repair estimate $280 vs. depreciated value $350. | Carrier likely chooses $280 repair allowance or direct repair. |
| FVP, missing new dining chair (set of 4) | Cost to replace matching chair or entire set, based on market availability. | Carrier may pay cost of one chair or negotiate for partial set replacement. |
Checklist: preparing your claim totals
- List each item with a proposed dollar amount for repair or replacement.
- Apply reasonable depreciation where appropriate, especially for older items.
- Note which items were packed by the mover vs. packed by owner (this can affect how movers view liability).
- Indicate valuation level and any total value caps that may apply.
- Add subtotals by category (furniture, electronics, missing boxes) and a grand total.
Building a strong, organized claim file
A clean, organized claim file makes it easier for an adjuster to understand your loss and harder for the mover to dismiss your demands. Think like you are building a binder a third party could review months from now.
How to structure your file
- Section 1 – Summary: Cover letter or claim form, including claim number if already assigned.
- Section 2 – Core documents: Bill of lading, inventory pages, valuation election, delivery receipt.
- Section 3 – Damage log: Spreadsheet or table listing each claimed item and amount.
- Section 4 – Evidence: Photos, videos, repair estimates, receipts, product links.
- Section 5 – Correspondence: Emails, letters, texts with mover and adjuster.
Digital organization tips
- Create a single folder on your computer or cloud drive titled "Moving Claim – [Mover Name] – [Month Year]."
- Use clear file names like "Sofa_tag123_photos" or "TV_repair_estimate_06-2026."
- Export texts with the mover into PDF if they contain important statements or promises.
- Back up the entire folder in at least one other location.
| Organization mistake | Why it hurts your claim | Better approach |
|---|---|---|
| Sending dozens of unlabeled photos in random order. | Adjuster struggles to match evidence to specific items and amounts. | Label photos and reference them in your damage log by file name. |
| Mixing personal rants with factual descriptions of damage. | Distracts from the claim facts and may reduce credibility. | Keep emotions out of your formal claim; stick to facts and numbers. |
| Relying on verbal promises only. | Hard to prove what was agreed later on. | Confirm key discussions by email and save the replies. |
Submitting your claim
Once your documentation is ready, it is time to formally present your moving damage claim. Follow the mover's instructions carefully to avoid delays or technical denials.
Common submission methods
- Online claim portal provided by the carrier or their claim service company
- PDF or paper claim form sent by email, mail, or fax
- Detailed claim letter with attachments, if no specific form is required
Key elements to include
- Your full name, move origin and destination, and contact information.
- Carrier or mover name, DOT/MC number (for interstate moves), and any job or order numbers.
- Pick-up and delivery dates.
- Claim type: loss, damage, delay, or combination.
- Itemized list of claimed items and amounts, matching your damage log.
- Clear reference to your supporting evidence (photos, estimates, receipts).
Sample wording for a short cover statement:
"Please accept this letter and attached documents as my formal written claim for loss and damage related to my household goods shipment performed by [Mover Name] under Bill of Lading #[Number], picked up on [Date] in [City, State] and delivered on [Date] in [City, State]. The attached damage log identifies each item, the type of loss, and the amount claimed, with corresponding photos and estimates."
Tracking and timelines after submission
Regulations for interstate moves generally require carriers to acknowledge receipt of a written claim within a set period (for example, 30 days) and to pay, deny, or make a firm settlement offer within a longer period (for example, 120 days), subject to certain conditions. Check your carrier's tariff and 49 CFR Part 370 for general federal guidelines, keeping in mind that intrastate rules may differ.
Keep a log of:
- The date you submitted the claim and how (portal, email, certified mail).
- Any claim number assigned by the mover or claim company.
- Dates and content of all follow-up communications.
How movers and adjusters respond
After you submit your moving damage claim, your file is usually handed off to a claims department or a third-party adjusting company. Understanding how they think helps you respond strategically.
What adjusters typically review
- Your valuation level and any total caps or special declarations.
- The inventory and condition codes at origin and destination.
- Whether the items were packed by the mover or packed by owner.
- Whether damage seems consistent with transit damage or may be pre-existing or wear and tear.
- The clarity and completeness of your evidence.
Common responses you may receive
- Request for more information – Additional photos, proof of value, or repair estimates.
- Partial offer – Payment for some items but denial or lower amounts on others.
- Denial of specific items – Based on alleged pre-existing damage, excluded items, or lack of proof.
- Full offer – Acceptance of your claimed amounts (less common but possible when your claim is moderate and well-supported).
Handling low or unfair settlement offers
It is common for carriers to open with a lower offer than you requested, especially on older items or where evidence is weaker. That does not automatically mean you should accept it.
Analyzing the offer
- Compare the offer item by item with your damage log.
- Note which items were fully approved, partially approved, or denied.
- Determine whether reductions are based on valuation limits, depreciation, or a disagreement about damage or causation.
Responding in writing
When you challenge an offer, keep your tone professional and focused on facts. Avoid emotional language or threats.
Sample wording for a negotiation response:
"Thank you for your settlement offer dated [Date]. I appreciate your approval of several items; however, I respectfully disagree with the proposed settlement for the following items: [list]. The amounts offered do not appear to reflect the actual repair or replacement cost, even after reasonable depreciation, nor do they align with the documentation I submitted. I have attached an additional repair estimate and current pricing information for your review and request that you reconsider the amounts for these items."
Negotiation checklist
- Ask the claims representative to specify how they calculated each disputed item.
- Request copies of any depreciation schedules or internal guidelines they used, if available.
- Provide updated or additional estimates or product links when the market price has changed.
- Be open to reasonable compromise when evidence is uncertain, but do not accept arbitrary reductions without explanation.
- Get any final agreement in writing before you sign releases or cash settlement checks.
Common mistakes to avoid
Certain missteps can weaken your moving damage claim or give the mover an easy excuse to deny or reduce payment. Knowing them ahead of time helps you steer clear.
| Mistake | How it harms your position | Better practice |
|---|---|---|
| Throwing away boxes and packing materials too quickly. | Carrier may claim damage was due to your unpacking or not their packing. | Keep materials for damaged items until the claim is resolved or carrier approves disposal. |
| Signing a "no damage" statement at delivery when there are issues. | Mover may point to your signature to dispute later claims. | Note visible damage and mark "subject to further inspection" when allowed. |
| Submitting a claim with vague descriptions like "many items broken." | Adjuster cannot evaluate or pay unidentifiable items. | Itemize each affected item with clear descriptions and amounts. |
Other pitfalls to watch for
- Missing the written claim deadline stated in your contract or tariff.
- Relying on phone calls instead of written communications for important points.
- Accepting a small "goodwill" payment that comes with a broad release of all claims you have not yet discovered.
- Exaggerating or inflating prices, which can hurt credibility for the whole file.
When and how to escalate a dispute
If you cannot reach a fair settlement directly with the mover, other options may be available. The right path depends on whether your move was interstate or intrastate, the amounts at stake, and the specific contracts you signed.
Regulatory complaints
- FMCSA National Consumer Complaint Database – For interstate household-goods carriers, you may submit a complaint to the Federal Motor Carrier Safety Administration. This does not guarantee compensation, but it can trigger regulatory review of patterns of misconduct.
- State consumer protection agencies – Many states regulate intrastate household-goods movers through public utilities commissions, consumer affairs departments, or similar agencies.
- Attorney General offices – Some state AGs accept complaints about moving scams or unfair practices.
Arbitration
Many movers participate in arbitration programs for certain disputes, particularly over charges or loss and damage up to specific dollar limits. Your bill of lading or estimate should state whether arbitration is available or required, and under what rules.
- Check any arbitration clause in your contract for deadlines and procedures.
- Determine what types of claims can be arbitrated (for example, charges, damage up to a certain amount).
- Be prepared to present organized evidence similar to a claim file.
Small claims court or legal review
When the dispute value is within your local small claims court limits, you may decide to file suit there. Rules for what you must do before filing (for example, giving the carrier time to respond to your claim) and what you can recover depend on your state and whether federal preemption applies.
Before going to court, many consumers find it helpful to have an attorney review their claim file and moving paperwork to evaluate options and potential obstacles. Legal timelines and jurisdiction questions can be complex, especially for interstate moves.
Sample wording and practical checklists
This section offers practical templates and step-by-step lists you can adapt to your situation.
Sample initial claim letter outline
- Paragraph 1: Identify yourself, the mover, bill of lading number, and move dates.
- Paragraph 2: State that you are submitting a formal written claim for loss, damage, and/or delay.
- Paragraph 3: Summarize the main categories of your claim (for example, furniture damage, missing boxes, electronics).
- Paragraph 4: Refer to your attached damage log and evidence, stating total amount claimed.
- Paragraph 5: Request acknowledgment of receipt and advise how you prefer to be contacted.
Sample closing sentence:
"Please confirm receipt of this claim and advise if you require any additional information in order to complete your review."
Checklist: evidence for a strong moving damage claim
- Bill of lading and all addenda.
- Inventory pages with any pre-existing damage codes highlighted.
- Photos and videos saved in clearly labeled folders.
- At least one repair estimate for major damaged furniture or appliances.
- Receipts or bank records for high-value items when available.
- Screenshots or printouts of current replacement prices from reputable retailers.
- Written notes or emails about any issues during loading, transit, or delivery.
Timeline overview: from delivery to resolution
| Stage | Suggested timeframe | Key actions |
|---|---|---|
| Delivery & first inspection | Day 0–3 | Note obvious damage on receipt, take initial photos, begin damage log. |
| Documentation phase | Days 3–21 | Gather repair estimates, receipts, and replacement pricing. |
| Claim submission | Within contractual deadline (often months, not days) | Submit claim form or letter with full documentation. |
| Carrier review | Weeks to several months, depending on rules | Respond to requests for information; track all communications. |
| Settlement or escalation | After offer received | Negotiate as needed; consider arbitration, complaints, or legal options if unresolved. |
Final checklist before you accept a settlement
- Confirm all damaged or missing items you discovered are included and correctly listed.
- Verify that the amounts reflect your valuation level and reasonable depreciation.
- Read any release or settlement agreement carefully, including small print.
- Ask how and when payment will be issued, and whether it is contingent on any further inspection.
- Keep copies of all final documents and correspondence in your claim file.
Frequently asked questions
How long do I have to file a moving damage claim?
Many interstate carriers require written claims within nine months of delivery under their tariffs and applicable federal rules, but you should check your bill of lading, terms and conditions, and any state rules for local or intrastate moves. It is best to act as soon as practical while evidence is clear.
Do I have to note all damage on the delivery receipt?
You should note any visible damage or missing items you see during delivery, but most contracts recognize that you cannot fully unpack and inspect everything on the spot. You can usually still claim later-discovered damage within the written claim period, especially if you act promptly and document thoroughly.
What if the mover says I chose the cheap coverage?
If you selected released value protection, the mover's liability is typically limited to a set amount per pound per article, even for high-value items. You can ask the mover to show the signed valuation form and bill of lading proving that election, but if it is valid, it may significantly limit your recovery.
Can the mover deny my claim because I packed my own boxes?
Movers often argue that they are not responsible for internal damage to boxes that you packed yourself, particularly when there is no visible crush or external damage. However, they may still be responsible when there is clear evidence of rough handling, missing boxes, or other factors. Provide detailed photos and explanations to support your position.
What if my items were damaged in storage before final delivery?
If your goods were in the mover's storage-in-transit or warehouse, damage discovered on delivery may still be part of the same claim. The carrier's liability and valuation coverage typically continue during authorized storage-in-transit periods, but check your contract and any warehouse receipts.
Do I need a lawyer to handle a moving damage claim?
Many consumers handle claims themselves, especially for moderate amounts. However, if your loss is large, you suspect serious misconduct or fraud, or you are considering court action, it can be wise to consult a lawyer experienced in transportation or consumer law in your state.
What happens if I accept a settlement check?
Often, cashing a settlement check or signing a release means you are accepting the offer as full and final settlement of your claim. Read any accompanying letters or releases carefully, and do not endorse or deposit checks that you do not want to treat as final payment.
Can I file complaints even if I already accepted a settlement?
You can typically still submit regulatory or consumer complaints about service issues, but your ability to seek more money for the same loss may be limited once you have signed a release or accepted final payment. If you are unsure, seek legal advice before signing anything.
Does filing a complaint with FMCSA or a state agency get me my money faster?
Regulatory complaints may pressure companies to improve practices or respond more carefully, but they do not guarantee reimbursement or speed. Agencies usually do not act as your personal lawyer; they focus on patterns and compliance issues.
Official sources & further reading
- FMCSA Protect Your Move – Consumer information on interstate household moves
- FMCSA National Consumer Complaint Database – File a complaint about an interstate mover
- 49 CFR Part 370 – Principles and practices for the investigation and voluntary disposition of loss and damage claims
- 49 CFR Part 375 – Transportation of household goods in interstate commerce; consumer protection regulations
- State consumer protection agencies or public utilities commissions overseeing household-goods movers in your state (search by your state name and "household goods mover regulations").
- The bill of lading, mover's tariff, and written claim instructions provided by your carrier.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.