When your belongings arrive scratched, broken, or missing, you are suddenly pushed into a world of paperwork, photos, and deadlines you never planned for. How you document and prove your moving damage claim in the first days after delivery can make the difference between a fair settlement and a frustrating denial.
Movers and their insurance or claims departments do not simply take your word for it. They rely on what is written on the bill of lading, delivery receipt, inventories, your photos and videos, repair estimates, and how clearly you present your loss. If your file is weak or disorganized, the carrier has more room to reduce or reject your claim.
This practical guide walks you step by step through how to document, calculate, and present a stronger moving damage claim. You will learn exactly what to photograph, what to write on delivery paperwork, how to track missing items, how to show value and depreciation, and how to respond if the mover challenges your evidence or offers a low settlement.
This is general information about U.S. household-goods moves. Rules can vary for interstate versus local or intrastate moves, military or corporate relocations, and international shipments. Always review your bill of lading, tariff, valuation election, and the mover’s written claim instructions, and consult an attorney for legal advice about a specific dispute.
Key takeaways
- Write specific damage notes and note missing items on the delivery receipt before signing, while the crew is still present.
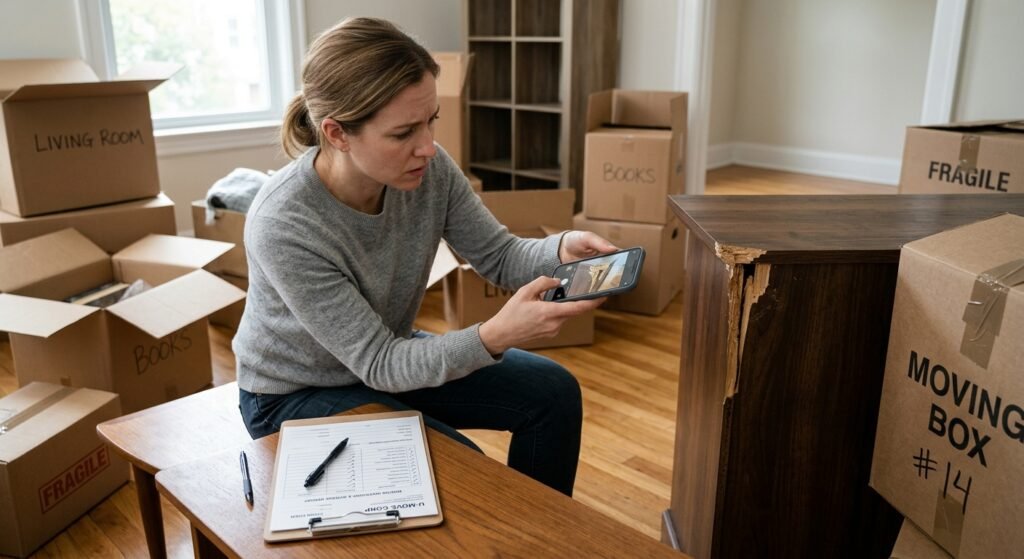
- Take clear, well-lit photos and videos of each damaged item, its model/brand labels, packing materials, and the surrounding area.
- Keep a detailed list of every damaged or missing item with make, model, age, original price, and links or estimates for repair or replacement.
- Match your claimed amounts to your valuation selection (released value, full-value protection, or other coverage) and document depreciation if required.
- Save copies of all key documents: bill of lading, inventories, estimates, emails, text messages, and receipts for any emergency repairs.
- Respond to low settlement offers with organized counter-evidence, including additional photos, estimates, and short written arguments.
- Know when to escalate through the mover’s internal process, FMCSA complaints, arbitration, state consumer agencies, or small claims court.
Understanding mover liability and limits
Before you can document and prove your moving damage claim, you need to know what the mover is actually responsible for. Liability is not automatic full replacement value in every situation. It depends on the type of move, the valuation option you chose, and any exclusions in the tariff or contract.
Interstate vs. intrastate and local moves
For interstate moves (between states), federal law, including the Carmack Amendment and regulations in 49 CFR Part 375, generally governs the carrier’s liability for loss and damage. For intrastate or local moves, state law and state regulations often control. Some states require specific coverage, limits, or claim procedures for household-goods movers.
This means your rights and the mover’s obligations can differ depending on where your shipment originated, where it was delivered, and how it was billed. Always review your bill of lading, estimate, and the mover’s tariff or terms and conditions.
Valuation options and what they really mean
Most residential moves offer at least two types of valuation:
- Released value (basic carrier liability) – Often around $0.60 per pound per item for interstate moves. This is not insurance and usually provides minimal compensation.
- Full-value protection (FVP) or similar coverage – The mover agrees to repair, replace with an item of like kind and quality, or pay the current market value (subject to limits, deductibles, and conditions).
Your documentation strategy is similar under either option, but the way you calculate and present the dollar value will change. With released value, weight matters more. With full-value protection, current replacement value, repair estimates, and depreciation matter more.
| Valuation type | Typical payout basis | Key evidence to focus on |
|---|---|---|
| Released value / basic liability | Cents per pound per item (e.g., $0.60/lb) | Item weight, damage photos, inventory notes, delivery receipt notations |
| Full-value protection | Repair cost, replacement cost, or current market value (subject to limits) | Purchase receipts, replacement links, repair estimates, proof of age and quality |
| Third-party insurance (if purchased) | Policy terms, often replacement cost up to policy limits | Insurance policy, premium payment, damage photos, invoices, receipts |
Why liability matters for your evidence
Understanding liability helps you decide what to emphasize:
- For minimal coverage, spend extra time proving what happened and that the mover is responsible.
- For full-value protection, also devote effort to proving how much the loss is worth today.
First steps at delivery: setting up your claim
The moment your shipment arrives, you begin building your case. Choices you make in the first hour of unloading can strengthen or weaken your claim later.
Inspect as you go, not days later
- Be present for delivery if at all possible.
- As boxes and furniture come off the truck, visually inspect for crushed corners, tears, punctures, broken legs, or moisture.
- Set obviously damaged items aside in a designated area so you can photograph them and avoid further handling damage.
- Keep high-value items and boxes clearly in view.
Write precise notes on the delivery receipt
Before you sign the delivery receipt (or bill of lading at destination), document any visible issues. Vague notations like “subject to inspection” or “damaged” are weaker than specific, item-level comments.
Examples of stronger wording you might write next to your signature area or in the exceptions section:
- “Dining table – deep scratch on top approximately 10 inches, not noted at origin.”
- “Sofa – right arm crushed, fabric torn, frame creaking.”
- “Box #42 – delivered open, contents appear broken.”
- “Box #88 and #103 missing at delivery.”
Do not feel pressured to rush. You are entitled to take reasonable time to inspect and note obvious issues before signing.
Keep damaged items and packing materials
Do not throw away boxes, padding, or broken pieces until your claim is resolved or the mover tells you in writing they do not need to inspect them. Carriers sometimes send inspectors or request photos showing how an item was packed.
Photo and video evidence: how to do it right
Photos and videos are among the most powerful tools you have to prove your moving damage claim. Poor or incomplete images make it easier for a carrier to argue the damage was pre-existing, minor, or unrelated to the move.
What to photograph for each damaged item
- The entire item, from multiple angles.
- Close-ups of the damage (scratches, dents, cracks, tears) with something to show scale (a ruler, coin, or your hand at the edge of the frame).
- Any manufacturer labels, serial numbers, or model tags.
- Original packaging, moving blankets, or boxes showing impact points or crushing.
- The area where the item was placed at destination (to show no obvious non-move-related causes like pets or children).
How to shoot better claim photos
- Use natural light where possible; avoid harsh flash reflections.
- Hold the camera steady and use focus lock so details like cracks or tears are sharp.
- Take more images than you think you need; you can choose the clearest later.
- Immediately back up photos to cloud storage or a computer folder labeled by item.
Using video to tell the story
Short videos can help show how drawers no longer slide, how a bed frame is wobbly, or how a TV screen flickers after impact. Narrate calmly and factually:
“This is the right side of our dining table. You can see a deep scratch about 10 inches long that was not present prior to loading. I am moving my hand along the scratch now for scale.”
Building your paper trail: essential documents
A moving claim often turns on paperwork. The carrier’s adjuster will compare your claim to the documents generated before and during the move. You should gather and keep copies of everything in a single, organized digital and/or physical file.
Core documents for most claims
- Bill of lading (pickup and delivery copies).
- Order for service or confirmation.
- Written estimate (binding or non-binding).
- Valuation election form showing your coverage choice and any deductible.
- Origin and destination inventories, including high-value item lists.
- Delivery receipt with your notations of damage or missing items.
- Claim form provided by the carrier (if applicable).
Supporting documents that strengthen your file
- Receipts or invoices showing original purchase price and date.
- Credit card statements or order confirmations for items bought online.
- Photos of items in your previous home (before the move) if available.
- Written repair estimates from furniture shops, electronics repair, or other specialists.
- Printouts or screenshots of current replacement items from reputable retailers.
- Emails or text messages with the mover about damages, delays, or missing items.
- Any incident reports created by the crew at delivery.
| Document | Why it matters | Tips |
|---|---|---|
| Bill of lading | Primary contract; shows carrier, dates, and basic terms | Keep legible copies from both pickup and delivery sides |
| Inventories | Show pre-move condition codes and which items were loaded | Compare condition codes to actual state at delivery |
| Valuation election | Determines how your loss will be calculated | Highlight limits, deductibles, special exclusions |
| Repair estimates | Help prove reasonable cost to fix items | Obtain from reputable, neutral vendors when possible |
Inventories and checklists for damaged and missing items
To keep your claim clear and manageable, you should create a master list of all damaged, destroyed, and missing items. This becomes the backbone of your claim form and supporting evidence.
Creating your damage and loss log
Use a spreadsheet or table with columns such as:
- Item number (for your own tracking).
- Room / location.
- Description (brand, model, color, size).
- Inventory number (if listed on the mover’s inventory sheets).
- Type of issue (damaged, destroyed, missing, late).
- Notes on damage (where, how severe).
- Original purchase date and price (if known).
- Estimated repair or replacement cost.
- Photo/Video file names.
| Item description | Issue | Key details to record |
|---|---|---|
| Queen bed frame (solid wood) | Broken leg | Which leg, size of break, effect on stability, repair estimate |
| 55” TV (Samsung) | Cracked screen, no picture | Model number, date of purchase, prior condition, replacement price |
| Box #27 (kitchen) | Missing | Inventory #, list of contents, approximate total value |
Checklist: tracking everything in one place
- Assign a unique reference number to each claimed item.
- Link each item to its photos, receipts, and estimates.
- Mark whether the item appears on the mover’s inventory and how it was coded.
- Note if the damage was written on the delivery receipt.
- Update status as the mover inspects, requests info, or offers settlement.
How to calculate and support the dollar amount claimed
Once you have your list of damaged and missing items, you must attach realistic dollar amounts that match your coverage and are supported by evidence.
Basic ways to value your loss
- Repair cost – If an item can be reasonably repaired, submit a written estimate and claim that amount.
- Replacement cost – For full-value protection or insurance, provide links or quotes for a similar item (same or comparable brand, size, and quality).
- Actual cash value – Replacement cost minus depreciation; often used when policies specify “ACV” instead of replacement cost.
- Weight-based amount – For released value, multiply the item’s weight by the cents-per-pound rate.
Example: comparing valuation methods
| Scenario | Claim basis | Illustrative result |
|---|---|---|
| 50 lb dresser, destroyed, released value at $0.60/lb | Weight x rate | 50 lb x $0.60 = $30 (regardless of market value) |
| Same dresser under full-value protection | Replacement or repair cost | If replacement is $700, claim may aim toward that figure |
| TV repair vs. replacement | Lesser of repair or replacement | If repair is $150 and replacement is $450, carrier may choose $150 repair |
Checklist: supporting your numbers
- Attach at least one written repair estimate for repairable items.
- Provide 2–3 replacement examples from mainstream retailers for big-ticket items.
- Explain why cheaper substitutes are not comparable if the mover proposes them.
- For older items, show approximate original price and age to justify your requested amount.
- Spell out the math in your claim: how you arrived at each figure.
Depreciation, valuation options, and how they affect payouts
Many consumers are surprised when carriers apply depreciation to their belongings. Depreciation reflects the idea that older items have less value than new ones due to wear and tear, age, and market changes.
Typical depreciation considerations
- Age of the item (years in use).
- Type of item (electronics often depreciate faster than solid wood furniture).
- Condition before the move (if you can show good condition, it can help).
- Useful life expectations (a 2-year-old couch is valued differently from a 12-year-old couch).
| Item type | Illustrative useful life (not a legal rule) | Documentation that helps you |
|---|---|---|
| Electronics (TV, laptop) | Often 3–5 years in practice, depending on policy | Proof of recent purchase, photos showing excellent condition |
| Quality wood furniture | Can have long useful life (10+ years) | Receipts, brand/model info, photos of minimal wear |
| Rugs, soft furniture | Subject to wear; useful life depends on material and use | Cleaning records, purchase history, close-up condition photos |
Policies and movers may use their own internal depreciation schedules. You can ask for an explanation and challenge aggressive depreciation with evidence of condition and market value.
Organizing your claim file for clarity and impact
Adjusters and claims reviewers are more likely to take a well-organized claim seriously. Disorganized submissions with scattered photos and unclear descriptions are easier to delay or deny.
Building a clear structure
- Create a single main folder on your computer titled “Moving Claim – [Mover Name] – [Month Year].”
- Within it, make subfolders: Documents, Photos, Videos, Estimates, Correspondence.
- Name files clearly, e.g., “Item01_DiningTable_Scratch_Photo1.jpg” or “Item03_TV_RepairEstimate_ShopA.pdf.”
- Maintain a master index spreadsheet linking each item to its file names and claim amount.
Checklist: what your final claim packet should include
- Completed claim form (if provided by the mover).
- Cover letter summarizing key facts and total amount claimed.
- Damage and loss log (spreadsheet or table) listing each item and amount.
- Copies of bill of lading, inventories, valuation election, and delivery receipt.
- Photos and videos labeled by item number.
- Repair estimates and replacement value documentation.
- Copies of all email or written communications with the mover.
Communicating with the mover or claims company
Professional, concise communication improves your credibility and puts pressure on the mover or their third-party claims administrator to handle your file properly.
Use writing over phone whenever possible
- Send important information and updates by email or certified mail so there is a clear record.
- If you must speak by phone, take notes of the date, time, who you spoke with, and what was said.
- Follow up calls with a short recap email: “As we discussed today, you indicated that …”
Stay factual and avoid emotional wording
It is understandable to be upset about damaged belongings, but emotional or hostile language can distract from the facts of your claim. Stick to:
- Dates and timelines.
- Specific item details and damage descriptions.
- References to documents (invoice, inventory number, photo label).
- Concrete requests (e.g., “Please confirm receipt of my claim” or “Please explain how you calculated this offer.”).
How to challenge low settlement offers
Low initial offers are common. Your job is to respond with additional evidence and clear reasoning, not just disagreement.
Step-by-step response to a low offer
- Compare the offer line-by-line to your item list.
- Identify where the carrier disputed damage, applied high depreciation, or substituted cheaper replacements.
- Gather and attach additional evidence for those items: more photos, current pricing from multiple sources, or an extra repair estimate.
- Write a concise rebuttal letter referencing their offer and your supporting documents.
- Set a reasonable deadline for a revised response (for example, 10–14 days), within any overall claim timeframe.
Sample wording when disputing a low offer
“Regarding Item 4 – Queen Bed Frame: Your offer of $75 appears to be based on excessive depreciation. The bed was purchased in 2019 for $950 and used lightly in a guest room. Attached are additional photos showing excellent pre-move condition and a current replacement quote of $1,050 for the same model. I respectfully request that you reconsider the valuation for this item.”
Common documentation mistakes and how to avoid them
Certain errors show up repeatedly in denied or underpaid claims. Knowing them in advance can save you time and money.
| Mistake | How it hurts your claim | Better approach |
|---|---|---|
| Signing delivery receipt as “received in good condition” without notes | Mover may argue there was no visible damage at delivery | Note specific visible damages and missing items before signing |
| Throwing away packing materials and broken parts too soon | Loses potential evidence about cause and severity | Keep all materials until claim is resolved or mover says otherwise in writing |
| Submitting only a short, vague claim letter | Adjuster may treat it as unsupported or incomplete | Provide detailed list, photos, and supporting documents from the start |
| Missing claim deadlines | Carrier may deny claim as untimely | Check bill of lading and contract; calendar all deadlines and send claims well before them |
Claim timelines, deadlines, and follow-up
Most movers and regulations require that you file your written claim within a certain period. Missing a deadline can severely limit or even eliminate your ability to recover.
Where to find your deadlines
- Bill of lading terms and conditions.
- Mover’s tariff or rules circular.
- Valuation or protection plan certificate.
- Claim form or instructions (sometimes on the mover’s website).
Many interstate carriers state that claims must be filed in writing within a certain number of months from delivery, and that lawsuits, if allowed, must be filed within a specific period after the carrier denies the claim. However, specific time limits can vary, so always check your individual documents and applicable law.
Illustrative claim timeline (your case may differ)
| Time period | Typical consumer actions | Notes |
|---|---|---|
| Day 0–3 after delivery | Inspect, photograph damage, note issues on delivery receipt, start item list | Critical period for strong documentation |
| Week 1–4 | Gather repair estimates, receipts, replacement values; submit written claim | Try not to wait until near the deadline |
| After claim submission | Respond to requests for information, review settlement offers, negotiate as needed | Keep track of all correspondence dates |
Follow any written instructions on when and how the mover will respond. If deadlines for their response pass, send a polite written reminder and, if necessary, consider escalation options.
Escalation: complaints, arbitration, and small claims court
If your claim is denied or the settlement offer remains unreasonably low despite your evidence, you may have escalation options. These depend on the type of move and the contracts you signed.
Internal appeal or supervisor review
- Ask in writing for your claim to be reviewed by a supervisor or higher-level claims manager.
- Attach a brief summary of the dispute and your best supporting documents.
FMCSA complaint (for interstate moves)
For interstate household-goods moves, the Federal Motor Carrier Safety Administration (FMCSA) operates a National Consumer Complaint Database. You can file a complaint about issues such as loss, damage, or deceptive practices. While FMCSA does not resolve individual dollar disputes, complaints can encourage carriers to pay more attention to problem files.
Required arbitration programs
Many interstate movers must offer an arbitration program for certain loss and damage disputes, often as required by federal regulation. Check your bill of lading and the mover’s materials to see whether arbitration is available, when it is required, and any fees or time limits for filing. Arbitration decisions can be binding, so review program rules carefully and consider legal advice before proceeding.
State consumer or utility agencies
Some states regulate household-goods movers through a public utilities commission, transportation agency, or consumer protection office. These agencies may accept complaints, investigate patterns, or in some cases help mediate disputes. Search your state’s official website for information about moving company regulation.
Small claims or other court options
Depending on your contract and applicable law, you may have the option to pursue your dispute in small claims court or another court. Contracts can contain forum selection clauses, arbitration requirements, or liability limits, so it is important to read your paperwork and consider consulting a qualified attorney about your specific situation before filing a lawsuit.
What not to sign or say too early
Protect your claim by being cautious about what you sign or state, especially during and immediately after delivery.
Documents to review carefully
- Release or settlement agreements – Do not sign anything that appears to waive further claims unless you fully understand the consequences and are satisfied with the settlement.
- “No damage” acknowledgments – Avoid signing documents that say everything was received in perfect condition if you have not had time to inspect.
- Blank or incomplete forms – Never sign blank forms; all key fields should be filled in or clearly marked.
Statements to avoid
- Admitting fault – Do not speculate that you might have caused damage when you are unsure.
- Overstating or exaggerating – Stay accurate; inflating damage can undermine your entire claim.
- Agreeing verbally that “everything is fine” before checking your goods.
Sample wording for letters and emails
Clear, professional wording makes your written claim easier to understand and harder to ignore. Here are examples you can adapt.
Sample initial claim notice
“Dear [Mover/Claims Department],
I am writing to provide formal notice of loss and damage to my household goods shipment transported by [Carrier Name], Bill of Lading #[Number], picked up on [Date] and delivered on [Date] to [Destination City/State].
During and after delivery, I observed multiple damaged and missing items. Attached is a detailed list identifying each item, the nature of the damage or loss, and the amount claimed, along with supporting photos, receipts, and estimates. Please confirm receipt of this claim and advise if you require any additional information at this time.
Sincerely,
[Your Name]”
Sample follow-up after no response
“Dear [Mover/Claims Department],
On [Date], I submitted a written claim regarding loss and damage to my shipment under Bill of Lading #[Number]. I have not yet received confirmation or a response. Please confirm in writing that you received my claim and provide an update on its status and expected timeline for review.
Thank you,
[Your Name]”
Frequently asked questions
How soon should I start documenting damage after delivery?
Begin as soon as items come off the truck. Note obvious damage on the delivery receipt, set damaged pieces aside, and take photos within the first few days while the condition and circumstances are fresh.
Do I need receipts for everything in my moving damage claim?
Receipts help, especially for high-value items, but they are not always required. You can also use credit card statements, order confirmations, comparable replacement prices, and photos to support your claimed amounts.
What if I discover hidden damage after I already signed the delivery receipt?
You can still file a claim, but the mover may question whether the damage occurred after delivery. Document when and how you discovered the problem, take detailed photos, and file your written claim as soon as possible within the allowed time.
Can the mover deny my claim because I packed my own boxes?
Movers often limit liability for boxes you packed yourself, especially if there is no visible exterior damage. However, they may still be responsible if you can show rough handling or damage inconsistent with proper care. Photos of crushed boxes and how they were stacked can help.
How do I prove the weight of an item under released value coverage?
You can use manufacturer specifications, user manuals, product listings from retailers, or online databases to show approximate weight. Print or screenshot the information and include it with your claim.
Should I repair or replace items before my claim is resolved?
If possible, wait until the claim is resolved or get written approval from the mover or insurer before repairing or discarding items. If you must make emergency repairs, keep all receipts and take thorough photos first.
What if the mover’s offer is far below my claimed amount?
Ask for a written explanation of how they calculated the offer, then respond with additional evidence: more photos, better estimates, and clear reasoning. You may also consider internal appeals, complaints, arbitration, or legal options if allowed.
Can I file a complaint with FMCSA or a state agency about my claim?
Yes, for interstate moves you can file with the FMCSA National Consumer Complaint Database. Many states also have consumer protection or transportation agencies that accept complaints about movers. These bodies may not set your settlement, but they can monitor patterns and sometimes help resolve issues.
Does filing an insurance claim change my rights against the mover?
It depends on the policy and contracts involved. Third-party insurance may pay you and then seek recovery from the mover, or it may require you to cooperate with subrogation efforts. Review your policy and consider legal advice if you have questions about how insurance interacts with the mover’s liability.
Do I need a lawyer to pursue a moving damage claim?
Many consumers handle routine claims themselves using good documentation. For larger losses, complex disputes, or potential lawsuits, consulting a qualified attorney familiar with transportation or consumer law can help you understand your options.
Official sources & further reading
- FMCSA – Protect Your Move
- FMCSA National Consumer Complaint Database
- 49 CFR Part 370 – Principles and practices for the investigation and voluntary disposition of loss and damage claims
- 49 CFR Part 375 – Transportation of household goods in interstate commerce
- State consumer protection offices or public utilities commissions (check your state’s official website for household-goods mover information).
- The bill of lading, tariff, valuation election, and mover’s claim instructions specific to your shipment.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.