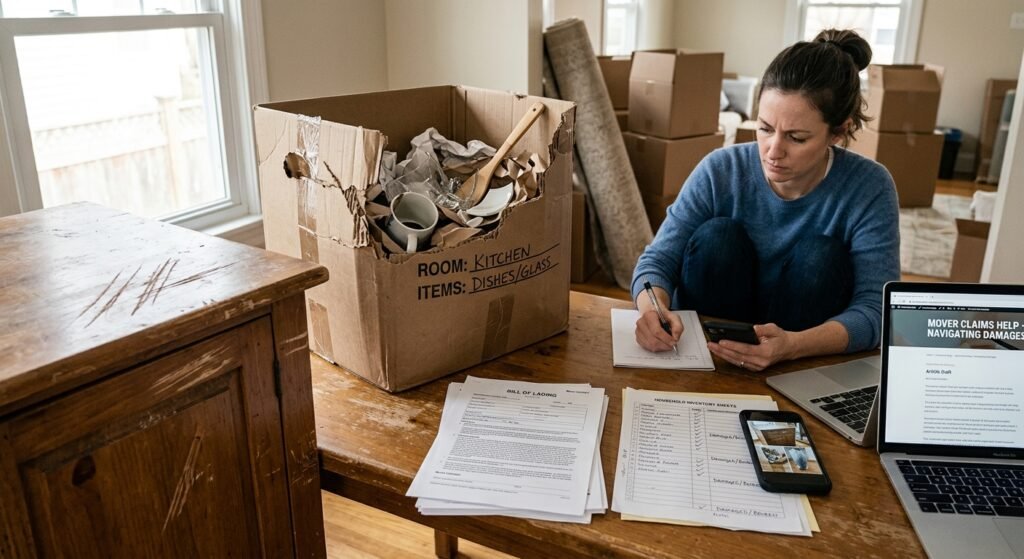
When a move goes wrong, the damage is more than just broken furniture. You lose time, energy, and peace of mind while arguing with a company that seems to control the process and the paperwork. The one thing you can control is the strength of your claim file.
Most disputes with moving companies are not won with angry phone calls. They are won with organized documentation, clear evidence, and a claim package that shows the mover exactly what happened, what you are claiming, and why your number is reasonable under the valuation you chose.
This guide walks you through how to build a strong moving damage claim file from the moment you notice damage or missing items, through documentation, calculations, responses to low settlement offers, and potential escalation to arbitration or complaints. It focuses on practical steps, not theory, so you can present your case in a way that claims departments and adjusters understand.
Rules can vary depending on whether your move is interstate, intrastate, local, military, corporate, or international. Always check your bill of lading, tariff, estimate, and the mover’s written claim instructions. This guide is general information, not legal advice, but it will help you assemble a more complete, credible claim file.
Key takeaways
- Your claim is only as strong as your documentation. Photos, inventory pages, receipts, and written timelines matter more than phone calls.
- Know what valuation you chose on the bill of lading. It usually controls whether you are limited to cents per pound or get full replacement/repair value.
- Deadlines are critical. Your mover’s tariff, bill of lading, and federal or state rules may set strict time limits to file and support your claim.
- Organize your claim file by item: damage description, evidence, value calculations, and requested amount so adjusters can follow it easily.
- Never sign broad releases or accept checks marked as full and final settlement until you fully understand what you are giving up.
- Escalation (FMCSA complaint, state agency, arbitration, or court) should be backed by the same organized evidence file, not just frustration.
- Always keep copies of everything you send and receive, including emails, texts, and the final settlement, in case the dispute resurfaces.
Understanding moving damage claim basics
Before you can build a strong file, you need to understand what you are actually building it for. A claim against a household-goods carrier is a formal written demand for money due to loss, damage, or delay of your shipment.
What a claim file needs to prove
In practical terms, your documentation should help demonstrate four key points:
- The mover received your goods in good condition (or at least not in the damaged condition you are claiming).
- The mover delivered your goods in damaged condition, or failed to deliver them at all, or delivered them late.
- The specific dollar amount of your loss, based on the valuation option and any limits in your paperwork.
- That you followed the mover’s procedures and deadlines to submit your claim.
Federal law (often referred to as the Carmack Amendment for interstate moves) and related regulations give carriers the right to require written claims with certain minimum information. Many movers base their claim rules on 49 CFR Part 370, which describes standards for filing and investigating freight claims. Your own paperwork takes priority, so always read it closely.
Types of losses you might claim
Your file may include one or more of these categories:
- Physical damage (scratched furniture, broken glass, dented appliances)
- Missing items (boxes that never arrived, items checked on the inventory but not delivered)
- Catastrophic loss (water damage, mold, items destroyed in an accident)
- Delay-related losses (extra lodging or living expenses, if allowed by your contract)
Each category requires a slightly different kind of proof and calculation, but the core structure of your claim file can remain the same if you organize it carefully.
Documents you must locate before you claim
Your paperwork is the skeleton of your claim file. Without it, the mover controls the narrative. With it, you can point to specific pages, signatures, and valuation elections instead of arguing in general terms.
Essential documents checklist
- Bill of lading (the main contract for the move)
- Order for service or written estimate
- Inventory sheets (often numbered, with notations for pre-existing damage)
- Weight tickets (for interstate or long-distance shipments)
- Final invoice and payment receipts
- Any photos or videos taken before loading or during packing
- Emails, texts, and messages exchanged with the mover
- The mover’s written claim form and instructions
- Tariff or terms and conditions (this may be online or embedded in the estimate)
If you do not have one of these, request it in writing. Many movers will provide missing documents upon request, especially the bill of lading and inventory.
How these documents support your case
| Document | What it shows | How it helps your claim |
|---|---|---|
| Bill of lading | Contract terms, valuation election, signatures, pickup/delivery dates | Proves what coverage you have and key dates for deadlines and delay claims |
| Inventory sheets | Item numbers, carton counts, pre-existing damage codes, condition at origin | Connects each damaged/missing item to the shipment and its original condition |
| Estimate / tariff | Rules, limits of liability, claim instructions, extra fees | Shows what the mover disclosed and what you agreed to pay for coverage |
Keep these documents in a dedicated digital folder along with scans or photos of any paper copies so you can attach them to emails or upload them with your claim.
Inspecting delivery and recording damage
The condition of your shipment at delivery is where most disputes start. The better you document this stage, the less room there is later for the mover to argue that something “must have already been that way” or “was never on the truck.”
At delivery: what to do and what not to do
- Be present for the entire delivery if possible. If you cannot, designate a trusted adult who understands what to look for.
- Check off items against the inventory as they come off the truck.
- Direct boxes and furniture to the correct rooms to avoid chaotic stacking.
- Note missing items or obvious major damage on the delivery receipt or inventory before signing.
- Avoid rushing to sign the paperwork just to get the crew out the door.
On many interstate moves, the delivery driver will ask you to sign the inventory pages. This is your chance to note boxes that are missing or visibly crushed and any large pieces that are clearly damaged.
Hidden damage discovered after delivery
You will not be able to fully unpack everything while the crew is still there. That is expected. However, as soon as you discover additional damage or missing items after delivery:
- Take clear photos and short videos before moving or attempting repairs.
- Update your own list of damaged/missing items with inventory numbers if possible.
- Notify the mover in writing (email is best) that you have discovered additional issues and will be filing a claim.
Many movers set an internal deadline to give notice of concealed damage (for example, within a few days), even though the formal claim deadline may be longer. Your file is stronger if you document both the date of delivery and the date you discovered the problem.
Collecting strong evidence: photos, videos, and more
Evidence turns your complaint into a claim. The goal is to show, as clearly as possible, what happened to each item, not just tell the story.
Photo and video checklist
- Overall shot of the item in the room (shows scale and context)
- Close-up of the damage from multiple angles
- Photo of manufacturer label, brand, and model if available
- Photo of any matching piece that is not damaged (helps contrast condition)
- Photo of crushed boxes, torn packaging, or wet cartons
- Video walk-through of the home immediately after delivery, including stacked boxes and any obvious damage
Take photos in good lighting, and avoid filters that could distort colors or make damage hard to see.
Other types of useful evidence
| Evidence type | Example | How it helps |
|---|---|---|
| Receipts or proof of purchase | Email receipt from furniture store, credit card statement | Shows original cost, purchase date, and brand for valuation and depreciation |
| Online replacement links | Current price for similar model on retailer website | Supports replacement cost when you cannot locate the original receipt |
| Repair estimates | Written quote from a furniture repair shop or appliance technician | Gives a professional opinion on whether repair is feasible and what it costs |
The stronger and more organized your evidence, the harder it is for a carrier to dismiss your claim as exaggerated or unsupported.
Matching items to the inventory and paperwork
A common reason claims are delayed or reduced is that the claims department cannot easily match the item you are talking about to their records. If you do that work for them, your claim file is far more persuasive.
How to match each item
- Locate the item on the mover’s inventory. Note the inventory number and description.
- Check for any pre-existing damage codes (often letters and numbers written in small print).
- Compare those codes to the mover’s chart of condition symbols. Many are generic (e.g., “M” for marred, “S” for scratched).
- Include the inventory number, description, and any codes in your claim spreadsheet or list.
If you strongly disagree with a pre-existing damage notation and you have photos showing better condition before the move, include those photos and explain the discrepancy briefly in your claim narrative.
Sample wording to connect an item to the inventory
“Item 12 – Dining Table, oak, 6ft (Inventory #47, described as ‘Table wood DR 6ft’). No pre-existing damage codes listed on the inventory. Table top now has deep gouge approximately 8 inches long discovered at delivery on 8/10/2026.”
When your claim paperwork reads like this item by item, the claims examiner can easily follow your logic, which usually leads to a smoother review.
Valuation coverage and how it limits your recovery
Even the best documentation cannot get you paid more than the coverage you selected allows. Many consumers misunderstand this and are shocked to learn that their recovery is limited by valuation and not the mover’s estimate or their homeowners insurance.
Common valuation options
| Valuation type | Typical description | Impact on your claim |
|---|---|---|
| Released value protection | Mover’s liability limited to a small amount per pound (e.g., $0.60/lb per article for interstate moves) | Severely limits recovery for lighter but expensive items like electronics |
| Full value protection | Mover agrees to repair, replace, or pay the current replacement value, subject to exclusions and declared shipment value | Allows claims for repair or replacement cost, but may involve deductibles and caps |
| Third-party moving insurance | Policy purchased separately from an insurer, not the mover | Adds another layer of claim rules and may require notifying both mover and insurer |
For interstate household-goods moves, federal rules require movers to offer at least a basic released value option and a higher level of protection, but the exact details and names can vary. Your bill of lading should show which one you elected, and your claim file should be built around that choice.
Why valuation matters to your calculations
Under released value, a 10-pound flat-screen TV is treated like any other 10-pound object, even if it cost $800. Under full value, that same TV might be repaired or replaced at current cost, subject to depreciation rules and policy limits.
Your claim spreadsheet should clearly show how you calculated each item’s claimed amount under the applicable valuation. This demonstrates that you are not simply demanding replacement cost when you are limited to weight-based liability.
How to calculate and support your dollar loss
Once you have your evidence and know your valuation coverage, you can turn that information into dollar amounts. This is where many claim files become confusing and vulnerable to reduction. A clear, consistent calculation method makes your position easier to defend.
Typical calculation methods
| Scenario | Calculation approach | Example |
|---|---|---|
| Released value (weight-based) | Item weight (in pounds) × per-pound rate stated in contract | 50 lb dresser × $0.60/lb = $30 maximum claim |
| Full replacement value | Cost to repair OR cost to replace with similar item, whichever is less, sometimes minus depreciation | Repair estimate $200 vs replacement $600 → $200 claim |
| Partial damage to a set | Value of damaged piece or reasonable share of set value, depending on contract language | 1 dining chair damaged out of 6 → 1/6 of table-and-chair set value, if allowed |
Building a simple claim spreadsheet
Most consumers find it easiest to track their calculations in a spreadsheet. Your columns could include:
- Item number (matching inventory)
- Description
- Type of loss (damaged, missing, destroyed)
- Weight (if known or estimated)
- Original cost and purchase year
- Evidence (photo file name, receipt, link, estimate)
- Valuation method applied
- Claimed amount
“Item 12 – Dining Table, oak, 6ft (Inv. #47). Purchased 2019 for $900 (receipt attached). Repair estimate from ABC Furniture Repair is $250 (attached). Under full value protection, claiming $250 for repair.”
When you send your claim, you can export this spreadsheet as a PDF or attach it in its original file format along with your evidence bundle.
Organizing your claim file for clarity
A strong file is not just about having many documents; it is about organizing them so that anyone reviewing your claim can follow each item from start to finish.
Suggested folder structure
- 01 – Core documents (bill of lading, inventory, estimate, tariff)
- 02 – Photos and videos (subfolders labeled by item number)
- 03 – Receipts and proof of value
- 04 – Repair estimates
- 05 – Correspondence (emails, letters, texts saved as screenshots or PDFs)
- 06 – Claim forms and spreadsheets
Name your files in a way that matches your claim spreadsheet. For example, “Item12_DiningTable_Photo1.jpg” is far easier for a claims examiner to cross-reference than “IMG_3021.jpg.”
Timeline table for your claim file
| Stage | Typical timing (example only) | What to add to your file |
|---|---|---|
| Delivery & initial inspection | Day 0–2 | Photos, notes on obvious damage, marked delivery receipt |
| Full unpack & evidence gathering | Days 1–14 (varies) | Additional photos, updated item list, notice email to mover |
| Claim preparation | Days 7–30+ (check your contract) | Spreadsheets, receipts, repair estimates, claim form draft |
Deadlines for filing and resolving claims can differ between interstate and intrastate moves and between carriers. Your bill of lading and tariff will usually spell out how much time you have to submit a written claim and how long the mover has to respond.
Filing the claim: forms, deadlines, and sample wording
Once your evidence and calculations are ready, it is time to file. This is more than just sending a complaint email. A formal claim usually must meet minimum information requirements to be valid.
Check the mover’s claim instructions
- Look for a “claims” section in the estimate, bill of lading, or mover’s website.
- Confirm where claims must be sent (email, online portal, mailing address, or fax).
- Note any stated deadline (for example, “Within 9 months of delivery” for some interstate carriers, or a shorter period for certain moves).
- See whether original documents are required or if copies are acceptable.
Federal regulations such as 49 CFR Part 370 describe the minimum content of a written claim, but your carrier may have more specific instructions. When in doubt, provide more detail, not less.
Key elements your written claim should include
- Your full name, current address, phone number, and email
- Move details (origin, destination, move date, delivery date, bill of lading or job number)
- A clear statement that you are filing a claim for loss and/or damage
- A summary of what happened (short, factual, not emotional)
- An itemized list of claimed items with amounts (you can attach this as a spreadsheet)
- A statement that supporting documents and photos are attached or will be provided upon request
Sample claim cover letter wording
“I am submitting a formal claim for loss and damage related to my household goods shipment moved by your company from Chicago, IL to Atlanta, GA under Bill of Lading #123456, picked up on 7/15/2026 and delivered on 7/20/2026.
Attached is an itemized list of damaged and missing items, including inventory numbers, descriptions, claimed amounts, and supporting documentation. I have also included photos, receipts where available, and a repair estimate for certain items.
Please confirm receipt of this claim and advise if you require any additional information to complete your investigation.”
Send your claim by a method that gives you proof of delivery (such as email with read confirmation or certified mail). Save a copy of everything you send in your claim file.
How movers and claims departments typically respond
Once your claim is filed, the mover or its claims administrator will open an investigation. How they respond varies widely, but understanding their process can help you anticipate what to do next.
Possible steps in the mover’s investigation
- Request for more information (missing receipts, clearer photos, more detail)
- Questions about pre-existing damage noted on the inventory
- Weight verification for items under released value
- Referral to a third-party repair company for inspection or quote
- Review of valuation limits, declared value of the shipment, and any deductibles
Respond promptly and in writing to any information requests. When you provide additional documents, label them clearly and update your claim spreadsheet if necessary.
Typical time frames
Some carriers state in their tariffs that they will acknowledge claims within a certain number of days and aim to resolve them within a set period. For many interstate movers, these time frames are influenced by federal guidance, but they are not always strictly enforced.
Use your claim file timeline table to track all key dates: when you filed, when you received responses, and when you sent additional information. If communication stalls, a polite but firm follow-up referencing those dates can show that you are paying attention.
Responding to low or unfair settlement offers
One of the most frustrating experiences for consumers is receiving a settlement offer that seems far below their actual loss. This is where a well-built claim file becomes essential.
Analyze the offer carefully
- Compare each line item in the offer to your claim spreadsheet.
- Identify whether the mover applied released value instead of full value, or vice versa.
- See whether they used depreciation, lower repair costs, or different replacement items than you proposed.
- Check for items that were omitted entirely.
Sometimes what feels like an arbitrary cut is actually based on the carrier’s understanding of your valuation coverage or internal rules. You may not agree, but you need to understand their reasoning to effectively respond.
Common reasons for reduced offers and how to respond
| Mover's rationale | What it means | Possible response |
|---|---|---|
| “Limited by released value” | They applied a per-pound rate, often $0.60/lb, regardless of the item's cost | Verify the valuation election on the bill of lading; if wrong, point to the correct document |
| “Pre-existing damage noted” | Inventory codes show scratches, dents, or wear before the move | Provide pre-move photos and explain if the damage is different or more extensive |
| “Insufficient documentation” | They feel you did not prove value, damage, or connection to the move | Submit additional photos, receipts, or written explanations tied to specific items |
Sample wording to dispute a low offer
“Thank you for your settlement offer dated 9/30/2026. After reviewing your itemized breakdown, I believe several items were valued incorrectly or omitted.
For example, Item 12 – Dining Table (Inv. #47) was limited to $30 under released value. However, the bill of lading (copy attached) shows that I elected full value protection, not released value. I have included that page for your review and respectfully request that this item be reconsidered under the correct coverage.
Please review the attached notes regarding Items 5, 12, and 23 and advise if you need any additional information.”
Keep your tone firm but professional. Focus on documents and numbers, not accusations.
Common mistakes that weaken a claim file
Knowing what not to do is just as important as knowing what to include. Many consumers unintentionally make errors that give carriers an easy reason to deny or reduce claims.
Frequent pitfalls
- Waiting too long to file, missing the claim deadline in the tariff or contract.
- Submitting only a narrative complaint with no itemized list or evidence.
- Sending photos but not tying them to specific inventory numbers or items.
- Accepting a check marked as “full and final settlement” without realizing it ends the dispute.
- Throwing away damaged items before the carrier can inspect them.
- Signing forms at delivery without noting obvious missing items or major damage.
Mistakes and countermeasures table
| Mistake | Why it hurts your claim | Better approach |
|---|---|---|
| Relying on phone calls only | No written record; hard to prove what was said or promised | Always follow up calls with an email summarizing the conversation |
| Guessing values without research | Makes your claim look inflated or unsupported | Use receipts, online prices, or repair estimates whenever possible |
| Signing broad releases early | May waive future claims or rights to dispute the offer | Read every release carefully; ask questions or seek legal advice if unsure |
If you have already made one of these mistakes, be honest in your file and focus on strengthening the remaining evidence rather than trying to hide the problem.
When and how to escalate: complaints, arbitration, court
Not every dispute ends with a settlement offer you find acceptable. Escalation options depend on the type of move, your contract, and your state. The stronger your claim file, the better positioned you are if you decide to take the next step.
Internal appeal or reconsideration
- Many movers will reconsider a claim if you provide new evidence or show that they misapplied valuation.
- Write a focused letter pointing to specific documents and contract language.
- Set a reasonable deadline for a response and keep proof of delivery.
FMCSA complaints for interstate moves
If your move crossed state lines, you can submit a complaint to the Federal Motor Carrier Safety Administration (FMCSA) through its National Consumer Complaint Database. This does not guarantee a particular outcome in your claim, but it can prompt regulatory attention to patterns of behavior.
FMCSA also operates the Protect Your Move program, which provides educational materials and tools for consumers dealing with moving companies. Your detailed claim file will make it easier to describe the issues if you file a complaint.
State consumer agencies
For intrastate or local moves, your state’s consumer protection office or public utilities commission may regulate movers. Some accept complaints or offer mediation services. Check your state government website for the appropriate agency and procedures.
Arbitration and small claims court
- Many household-goods carriers participate in arbitration programs, especially for disputes about charges or certain damage claims.
- Your bill of lading or tariff may require arbitration before you can sue, or may limit your ability to go to court.
- Small claims court is sometimes an option for limited-dollar disputes, depending on state law and your contract.
Arbitration and court both rely heavily on evidence. The claim file you have built – with documents, photos, spreadsheets, and correspondence – becomes your exhibit binder. While this guide cannot provide legal advice, it can help you prepare the factual backbone of your case if you seek legal guidance or representation.
How long to keep records and what to store
Even after your claim is resolved, it is wise to keep your claim file for a reasonable time in case issues resurface, the mover’s payment method fails, or a later dispute arises about the terms of the settlement.
What to keep
- All core move documents (bill of lading, inventory, estimate, invoices)
- Copies of your claim form, spreadsheet, and evidence list
- Photos, videos, receipts, and estimates used in the claim
- All emails and letters exchanged with the mover, insurer, or agencies
- The settlement letter or agreement and proof of payment
Consider backing up your digital folder to cloud storage or an external drive labeled with the move date and mover’s name.
Frequently asked questions
How soon should I start building my moving damage claim file?
Begin as soon as you notice damage or missing items. Take photos immediately, note issues on the delivery paperwork when possible, and start a simple list of affected items. Do not wait until you are fully unpacked to begin collecting evidence.
Do I need original receipts for every damaged item?
Original receipts are helpful but not always required. You can often support value with credit card statements, order confirmations, warranty registrations, or current prices for similar items online. Explain your method in your claim spreadsheet.
What if the inventory shows pre-existing damage I do not agree with?
If you have pre-move photos showing better condition, include them and explain the difference in writing. Note that you disagree with the inventory code, but stay factual rather than accusatory.
Can I throw away badly damaged items after I take photos?
It is safer to keep damaged items until your claim is resolved or until the mover confirms in writing that they do not need to inspect them. Some carriers may request an in-person or virtual inspection.
How detailed does my claim list need to be?
The more detailed, the better. Include inventory numbers, descriptions, type of damage, evidence references, and claimed amounts. A clean spreadsheet attached to your claim is usually easier for the mover to process than a long narrative.
Should I accept a partial payment while we keep negotiating?
Be very careful. If a check or agreement is labeled as “full and final settlement,” cashing it or signing may end your claim. Ask the mover to clarify in writing whether a payment is partial or final, and consider seeking legal advice if you are unsure.
Can I claim for emotional distress or inconvenience?
Most moving contracts and valuation options cover physical loss or damage to goods, not emotional distress. Some may address certain delay expenses if specified. Check your tariff and bill of lading for what is and is not covered.
What if the mover does not respond to my claim?
Follow up in writing and keep copies. If there is still no response within the time frames stated in the tariff or within a reasonable period, you may consider filing complaints with FMCSA or your state agency, and exploring arbitration or legal options.
Do I need a lawyer to pursue a moving damage claim?
Many consumers handle claims directly with the mover, especially for modest losses. For large losses, complex disputes, or if you are considering arbitration or court, consulting a lawyer familiar with transportation or consumer law may be helpful.
Will my homeowners or renters insurance cover moving damage?
Some policies provide limited coverage for moves, but many exclude damage while items are in the hands of a moving company. Check your policy and speak with your insurer. Even if coverage exists, they may require you to pursue the mover first.
Official sources & further reading
- FMCSA Protect Your Move – Federal resources on interstate household-goods moves, your rights, and carrier responsibilities.
- FMCSA National Consumer Complaint Database – Portal to file complaints about interstate movers and brokers.
- 49 CFR Part 370 – Federal regulations on principles and practices for the investigation and voluntary disposition of loss and damage claims.
- 49 CFR Part 375 – Federal rules covering transportation of household goods in interstate commerce.
- Your state attorney general's consumer protection office or public utilities commission – Check your state government website for intrastate moving rules and complaint options.
- Your mover's bill of lading, tariff, and written claim instructions – These documents often control deadlines, valuation options, and procedures specific to your shipment.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.