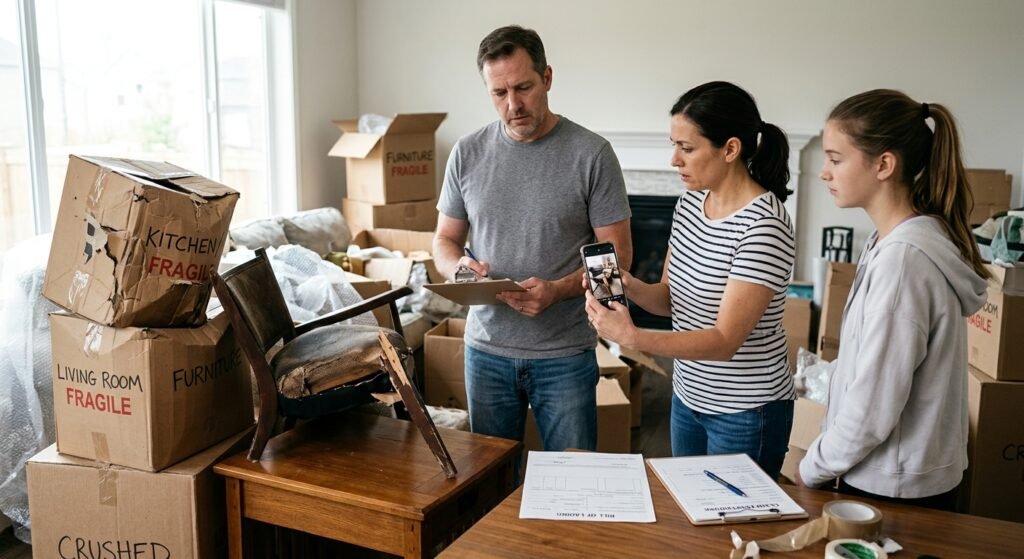
When your belongings arrive damaged, missing, or days late, you are suddenly forced to become your own claims adjuster. You are dealing with broken furniture, stressed family members, and a moving company that may already be talking about “limited liability” or “per-pound coverage.” In this moment, what you do next can make a big difference in how your claim plays out.
Most people only move a few times in their lives. Movers, carriers, and third-party claims companies handle files every day. That imbalance is why a strong, organized claim file matters. The better your documentation, timelines, photographs, and valuation support, the harder it is for anyone to minimize your loss or delay your settlement.
This guide walks you through how to build a serious, well-documented moving damage claim file from day one. You will learn what to photograph, which documents to save, how to calculate your dollar loss, how to respond to low offers, and when to escalate disputes using tools like FMCSA complaints, arbitration, or small claims court where appropriate.
This is general information about household-goods moves in the United States. Rules can differ for interstate versus intrastate moves, military or corporate relocations, and international shipments. Always review your bill of lading, tariff, and valuation election, and consider speaking with an attorney or your state consumer agency for advice on your specific situation.
Key takeaways
- Build a dedicated claim file immediately at or after delivery, including the bill of lading, inventory, photos, emails, and receipts.
- Document damage before repairs or disposal using clear photos, video walk-throughs, and written notes tied to inventory numbers.
- Your compensation is usually limited by the valuation option you chose and the mover’s tariff, not automatically by replacement value.
- Support each claimed item with evidence: ownership, condition before the move, extent of damage, and realistic repair or replacement cost.
- Track deadlines on the bill of lading and mover paperwork; many interstate movers require written claims within 9 months of delivery.
- Respond to low offers with organized counterevidence, not anger: updated estimates, comparable replacement links, and written explanations.
- Escalation tools include internal appeals, FMCSA complaints, arbitration, state consumer agencies, and, where appropriate, small claims court.
Understanding mover liability and valuation
Before you argue about numbers, you need to know what the mover may actually be responsible for. In U.S. household-goods moves, liability is driven by the type of move (interstate vs. intrastate), what your contract says, and which level of valuation you selected.
Interstate vs. intrastate moves
Interstate moves (between states) are generally governed by federal law, including the Carmack Amendment and Federal Motor Carrier Safety Administration (FMCSA) rules. Intrastate or local moves are usually controlled by state law or state moving regulations.
Why this matters: deadlines, claim forms, required arbitration programs, and the default liability levels are often different for intrastate moves. Your bill of lading and estimate should indicate whether your shipment is interstate or intrastate.
Released value vs. full value protection
Most movers offer at least two valuation levels:
- Released value protection (often around $0.60 per pound per article for interstate moves). This is the bare minimum and is usually included at no extra charge. Payouts can be very low for lighter, more expensive items.
- Full value protection at a higher cost, where the mover agrees to repair, replace, or pay the current market replacement value up to a certain limit, subject to deductibles and exceptions.
If you signed for released value, you may feel shocked when the adjuster offers $36 to settle a claim for a destroyed 60-inch television. That is the effect of per-pound coverage. On the other hand, full value protection typically requires you to document actual replacement or repair costs.
Why this should show up in your claim file
Your claim file should contain:
- A copy of the page where you chose the valuation level.
- Any separate valuation certificate or declaration needed for full value protection.
- Any limitations listed in the tariff (e.g., exclusions for certain items, high-value declarations, pairs-and-sets provisions).
If the mover argues that you selected the lowest coverage but your paperwork is unclear or unsigned, that inconsistency can become part of your dispute and escalation strategy.
Documents that matter in a moving damage claim
Missing or incomplete paperwork is one of the biggest obstacles consumers face. You can strengthen your position by rounding up all key documents and keeping them together from the start.
Core documents for your file
- Bill of lading (BOL) – the main contract for carriage; it usually contains liability terms, arbitration requirements, and claim deadlines.
- Order for service / estimate – binding or nonbinding estimate, including valuation options and expected charges.
- Household goods inventory – the numbered list the movers used when loading, often with condition codes like “SC” (scratched) or “BR” (broken).
- Pickup and delivery receipts – signed documents noting the dates and any notations you or the driver made about damage or missing items.
- Valuation election form – the form where you selected released value or full value protection.
- Tariff or terms and conditions – sometimes provided as a separate booklet or link, describing how claims will be handled.
- Invoices and payment records – proof of what you paid and when.
- Claim form – if the mover or third-party administrator requires a particular form, keep blank and submitted copies.
Helpful supporting documents
- Original purchase receipts for high-value items.
- Credit card or bank statements showing purchases if receipts are missing.
- Product manuals, registration emails, or photos of items in your old home.
- Repair estimates from local shops or qualified contractors.
- Online price quotes or links showing current replacement cost.
- Emails and text messages with the mover, driver, sales rep, or claims company.
Your goal is simple: if a stranger opened your claim folder, they could understand exactly what happened, what was damaged, and why you are asking for a particular amount.
How to start and structure your claim file
A strong claim file is not just a pile of papers. It is organized in a way that tells your story clearly and backs up every dollar claimed.
Create a central system
Use whatever system you will truly maintain: a physical binder, a shared drive folder, or both. Consider this structure:
- Section 1: Contracts & move documents – BOL, estimates, inventory sheets, valuation forms.
- Section 2: Damage logs & photos – item-by-item lists with corresponding photo files.
- Section 3: Valuation & receipts – purchase records, online price screenshots, repair quotes.
- Section 4: Communications – emails, letters, internal claim notes, and phone call summaries.
- Section 5: Offers, decisions & escalation – claim acknowledgment, settlement letters, appeals, and arbitration forms.
Sample timeline and file structure table
| Stage | What to do | What to file |
|---|---|---|
| Delivery day | Note visible damage on delivery receipts; start taking photos and video. | Signed receipts, initial photo set, driver’s notes. |
| First 3–5 days | Complete inspection room by room; build your damage log. | Damage list, updated photos, short video walk-through. |
| Within claim deadline | Submit written claim with supporting documents. | Claim form, spreadsheets, receipts, estimates. |
Checklist: starting your claim file
- Create a dedicated email folder and label for all mover communication.
- Scan or photograph paper documents so you have digital copies.
- Rename photos with clear titles (e.g., “Item12_bedframe_leg_crack.jpg”).
- Start a simple spreadsheet listing item number, description, problem, and claimed amount.
- Keep a running log of calls: date, time, who you spoke with, and what was said.
Inspecting delivery and documenting damage
Your claim is only as strong as your evidence of damage. That evidence starts at delivery and continues as you unpack.
During delivery
- As items come off the truck, compare tags with the inventory list.
- If you see visible damage, mention it to the driver and make sure it is noted on the delivery receipt or inventory.
- Do not feel rushed into signing documents without at least a basic walk-through to spot obvious problems.
If the driver insists on a quick signature, you can add wording like: “Subject to further inspection for concealed damage and missing items.”
After delivery: systematic inspection
Once the crew leaves, do a more detailed inspection:
- Start with high-value rooms (electronics, antiques, artwork, primary bedroom, kitchen).
- Work item by item, checking against the inventory list number.
- Photograph damage from multiple angles, including close-ups and context shots.
- For missing items, photograph the empty location (e.g., a missing drawer unit in a bedroom) and any packaging that arrived open or empty.
Creating a damage log
In your spreadsheet or notebook, record for each item:
- Inventory number and item description.
- Room and location at delivery.
- Type of problem (scratched, dented, broken, missing, water-damaged, mold, etc.).
- Notes about packaging (crushed box, wet carton, missing padding).
- Whether you have pre-move photos to show condition.
This log becomes the backbone of your written claim and helps you avoid forgetting items later.
Evidence checklist: photos, video, and witnesses
Strong evidence can move your claim from “he said, she said” to a clear, documented loss. Your goal is to show three things for each item: ownership, pre-move condition, and post-move damage or loss.
Photo and video evidence
- Before-and-after photos – If you have social media posts, real estate listing photos, or home pictures showing undamaged items before the move, save them.
- Close-up shots – Show cracks, dents, tears, water lines, and broken pieces.
- Context shots – Show the whole item and its surroundings so an adjuster can understand what they are looking at.
- Packaging photos – Crushed cartons, broken crates, or inadequate padding can support negligence arguments.
- Video walk-throughs – Narrate the date, room, and item numbers as you walk around damaged goods.
Document and witness evidence
- Neighbors, friends, or family who saw damage at delivery or helped unpack.
- Emails or texts from the driver or dispatcher acknowledging issues.
- Contractors or repair shops stating that damage was caused by impact, moisture, or mishandling.
Evidence types table
| Evidence type | What it proves | Tips |
|---|---|---|
| Pre-move photos | Item existed, condition before shipment. | Pull from listing photos, phone galleries, or insurance files. |
| Post-move photos | Nature and extent of damage after shipment. | Take multiple angles; include inventory tag or label when possible. |
| Repair estimates | Reasonable cost to fix, or that item is not repairable. | Request written estimates on letterhead with photos if possible. |
Checklist: evidence to gather
- At least one clear photo of every damaged item.
- Photos of box labels and inventory tags tied to those items.
- Any pre-move photos you can locate.
- Written repair estimates for high-value or complex items.
- Screenshots of comparable replacement items and prices.
- Copies of any texts or emails admitting delay, damage, or loss.
Calculating and supporting your claim amount
Once you have your damage log and evidence, you need to convert it into a dollar amount. How you calculate that amount depends heavily on your valuation option and any limitations in your contract or tariff.
Basic approaches to valuation
- Full value protection – Typically allows for repair, replacement with like kind and quality, or a cash payment up to replacement cost (subject to the policy terms and any deductible).
- Released value – Often limited to a fixed amount per pound per article (such as $0.60 per pound for interstate shipments), regardless of market value.
- State-specific rules – Some states have different minimums or special rules for intrastate moves; check your state’s consumer protection or public utilities commission.
Building an itemized claim spreadsheet
Your spreadsheet should clearly list:
- Item number and description.
- Weight (if known) or estimated weight.
- Original purchase price and approximate purchase date (year).
- Condition before the move (excellent, good, fair).
- Type of damage or loss.
- Claimed repair cost or replacement value.
- Any depreciation applied (for full value claims).
Sample valuation table
| Item | Key facts | Claim approach |
|---|---|---|
| Sofa, 5 years old | Purchased $1,200; torn fabric and broken leg; repairable. | Repair estimate of $350; claim that amount under full value protection. |
| TV, 2 years old, 40 lbs | Purchased $600; screen shattered; not repairable. | Under released value at $0.60/lb, limited to $24; under full value, support replacement cost with current prices. |
Depreciation and valuation explained
Depreciation is a reduction in value over time based on age, condition, and useful life. Many movers or claims departments will apply depreciation to full value claims unless the contract says otherwise.
How depreciation works in practice
There is no single nationwide depreciation chart for household goods. Different carriers use different internal guidelines. However, you may see rough patterns like:
- Electronics: faster depreciation, often over 3–5 years.
- Furniture: slower depreciation, sometimes over 7–15 years depending on quality.
- Mattresses and bedding: moderate depreciation, often over 5–8 years.
If a 5-year-old item is destroyed, the carrier may argue that its current value is much lower than its original price. Your job is to provide reasonable evidence that your claimed amount matches fair market value or that repair cost is justified.
Sample depreciation illustration
| Item | Original price / age | Possible depreciated value |
|---|---|---|
| Dining table | $900, 8 years old, solid wood, good condition | Carrier may argue $300–$400, depending on condition and market. |
| Laptop | $1,000, 3 years old, used daily | Carrier may argue significantly lower value due to rapid tech depreciation. |
How to push back on unfair depreciation
- Provide current used-market listings for similar items in similar condition.
- Show that the item was in “like new” or excellent condition, even at its age.
- Highlight that certain items (antiques, solid wood pieces) hold value better than mass-market goods.
Keep your arguments grounded and reasonable; extreme positions on either side are easier for an adjuster to reject.
Claim timelines and deadlines
Your right to pursue compensation is tied to time. Many consumers lose leverage by missing deadlines or letting their claim go quiet for months.
Common timeframes (check your paperwork)
- Notice of loss or damage at delivery: often expected, but concealed damage is usually still claimable later.
- Written claim deadline for many interstate moves: commonly 9 months from delivery, but your contract controls.
- Time for the carrier to acknowledge and resolve the claim: federal regulations for interstate carriers (49 CFR Part 370) include standards for acknowledgment and disposition of claims, but your specific timeline may vary.
Intrastate moves may have different time limits set by state law or by the contract. Always read the bill of lading and any attached terms.
Timeline planning table
| Event | Target timing | Your action |
|---|---|---|
| Delivery date | Day 0 | Photograph visible damage; note issues on paperwork. |
| Initial inspection | Days 1–7 | Complete damage log and gather evidence. |
| Formal claim submission | As soon as practical; before contractual deadline | Send written claim with all required information and attachments. |
Checklist: managing deadlines
- Locate and highlight any claim deadline language in your bill of lading.
- Mark calendar reminders 30, 60, and 90 days before your latest possible claim date.
- Submit your written claim early enough to add documents or clarify issues if needed.
- Keep proof of when you sent the claim (email timestamp, certified mail receipt, or online portal confirmation).
Communicating with the mover or claims company
How you communicate can affect how your file is treated. You want to be firm, factual, and organized, not emotional or vague.
Best practices for communication
- Use email whenever possible so you have a written record.
- When you must speak by phone, follow up with an email recap of what was discussed.
- Reference your job number, claim number, and shipment dates in every message.
- Attach labeled documents and photos instead of sending large, disorganized batches.
Sample email tone
“I appreciate your prompt acknowledgment of my claim. Attached is an updated spreadsheet listing each damaged or missing item, the supporting photos, and the repair or replacement values. Please review the documentation and let me know if you require any additional information to evaluate the claim in good faith.”
This tone signals that you are organized and expect a serious review, but you are not making personal attacks.
How to respond to low or partial settlement offers
Many consumers receive an initial settlement offer that feels unfairly low, especially under full value protection. You are not required to accept the first offer if it does not reasonably reflect your documented loss.
Analyze the offer
- Compare the offer line by line against your itemized claim.
- Identify where the adjuster used different weights, values, or depreciation.
- Note items that were denied outright and the reasons given.
Common reasons for low offers and countermeasures
| Issue | How it hurts your claim | How to respond |
|---|---|---|
| Assumed pre-existing damage | Carrier reduces or denies items listed with condition codes on inventory. | Provide pre-move photos showing better condition; explain that minor scuffs are different from current major damage. |
| Aggressive depreciation | Offer far below realistic used value. | Submit used-market comparables and a written explanation of the item’s quality and condition. |
Sample counteroffer wording
“Thank you for your settlement offer dated May 12. After reviewing the line-item detail, I cannot agree that this offer fairly compensates the documented loss. In particular, items 7, 15, and 22 have been significantly undervalued compared to the attached repair estimates and current replacement prices. I have included a revised spreadsheet, additional photos, and comparable listings supporting a higher value. Please review this additional evidence and reconsider the amounts for these items.”
A written, evidence-based response is more effective than simply stating that the offer is “unacceptable.”
Common mistakes that weaken your claim
Understanding what not to do is just as important as following best practices. Many consumers unintentionally harm their own position.
Typical pitfalls
- Throwing away damaged items before the claim is resolved, leaving no chance for inspection.
- Failing to note obvious damage or missing items at delivery when it was practical to do so.
- Submitting a vague claim like “many things were broken” without itemization.
- Missing written claim deadlines listed in the contract.
- Accepting a low settlement and signing a release without understanding its finality.
Mistake and countermeasure table
| Mistake | Why it hurts | Better approach |
|---|---|---|
| Disposing of items too early | Carrier may argue they cannot verify damage or repair options. | Keep damaged items until the claim is resolved or you have written permission to discard them. |
| No written claim | Phone complaints usually do not count toward formal deadlines. | Submit a clear written claim following the mover’s instructions before the deadline. |
Checklist: avoid these errors
- Do not rely only on phone calls; follow up in writing.
- Do not sign a broad release without reading and understanding it.
- Do not exaggerate or claim for items that were never shipped.
- Do not wait until month eight to begin gathering documents for a 9-month deadline.
- Do not send random, unlabeled photos; organize and label everything.
Organizing your evidence for negotiation or escalation
As your claim progresses, organization becomes more important. An adjuster or arbitrator will understand your case faster if your evidence is easy to follow.
Suggested structure for your claim package
- Cover letter summarizing the move, the problems, and the total amount claimed.
- Itemized spreadsheet listing all claimed items and values.
- Photo index mapping item numbers to specific photo filenames.
- Attachment packet with photos, receipts, estimates, and relevant email threads.
Practical tips
- Use consistent item numbers from the inventory wherever possible.
- Number your attachments (Attachment A, B, C) and reference them in your cover letter.
- Save a full copy of everything you send, including file names and emails.
This level of organization signals that you are prepared to pursue the matter through any available channels if needed.
Escalation options: FMCSA, arbitration, agencies, court
If you reach an impasse with the mover or its claims company, there are escalation paths. Which ones apply will depend on whether your move was interstate or intrastate, and what your contract says.
Internal appeal
Before going outside the company, you can typically:
- Request a review by a supervisor or claims manager.
- Provide additional evidence and a written explanation of why the offer or denial is unreasonable.
FMCSA and federal tools (for most interstate moves)
- FMCSA National Consumer Complaint Database – You can file a complaint about an interstate household-goods mover with the Federal Motor Carrier Safety Administration. While FMCSA does not resolve individual claims, complaints can trigger reviews and may encourage movers to resolve disputes.
- Required arbitration program – Many interstate movers must offer arbitration for certain disputes, especially over loss, damage, or charges, usually after you exhaust the company’s internal process.
State consumer agencies and regulators
For intrastate moves, or even for additional help with interstate disputes, you may contact:
- Your state’s consumer protection office or attorney general.
- Your state public utilities commission or transportation regulator, if they oversee movers.
- Local consumer affairs offices in larger cities or counties.
Court options
In some situations, consumers pursue claims in small claims court or other courts. However:
- Your bill of lading may require you to complete the mover’s internal process and sometimes arbitration before going to court.
- Court procedures, jurisdiction, and monetary limits vary by state.
- Consider consulting an attorney to understand your options and deadlines.
Escalation is more effective when your claim file is complete and well-documented. Agencies and courts cannot fix missing evidence.
What not to sign or say too early
In the stress of a damaged move, it is easy to sign or say things you later regret. Slow down and protect your position.
Documents to read carefully
- Delivery receipts – You often must sign to receive your goods. You can still add limiting language such as “subject to further inspection.”
- Settlement releases – Before signing any release, confirm that you understand whether it ends all claims related to the move or only certain items.
- Arbitration or forum selection clauses – Be aware of what they require, such as specific arbitration programs or locations.
Statements to avoid
- “Everything looks fine” when you have not opened boxes yet.
- “It was probably my fault for packing that myself” if you do not actually know what caused the damage.
- “It is not a big deal” about an item that later turns out to be expensive.
Stick to factual observations: what you see, what you documented, and what is listed on the paperwork.
Sample wording for your claim and emails
Strong writing does not mean legal jargon. It means clear, factual, and specific statements tied to your evidence.
Sample initial written claim paragraph
“I am submitting a written claim for loss and damage to my household goods shipment transported under Bill of Lading No. 123456 from Denver, CO to Raleigh, NC, delivered on March 5, 2026. Attached is an itemized list of damaged and missing items, supporting photos, receipts, and repair estimates where available. The total amount claimed is $4,250. I elected full value protection as shown in the enclosed valuation form. Please review the attached documentation and confirm receipt of this claim.”
Sample follow-up email after no response
“On April 2, I submitted a written claim with supporting documents regarding my March 5 household goods delivery. I have not yet received acknowledgment or an update on the status of my claim. Please confirm that my claim was received, provide a claim number, and advise when I can expect a written response, consistent with applicable regulations and your company policy.”
Checklist: content to include in your written claim
- Your full name, current address, phone number, and email.
- Pickup and delivery dates, origin and destination cities.
- Bill of lading number, job number, and any claim number.
- A clear statement that this is a written claim for loss and damage.
- Total dollar amount claimed, with itemization available in an attached list.
- Copies or references to supporting evidence (photos, receipts, estimates).
Frequently asked questions
How long do I have to file a moving damage claim?
Many interstate movers require written claims within nine months of delivery, but your exact deadline is set by the bill of lading, tariff, and applicable law. Intrastate moves can have different time limits. Always check your paperwork and file as soon as you can.
Do I need receipts for every damaged item?
Receipts are helpful, especially for high-value items, but they are not always required. You can also use bank or card statements, online order histories, product manuals, registration emails, and realistic replacement price screenshots to support value.
What if I find damage after the movers leave?
Concealed damage is common. Document it with photos and video as soon as you discover it and add it to your written claim. Explain that the damage was not visible at delivery. Follow any instructions the mover provides for reporting concealed damage within a certain period.
Can the mover deny my claim because I packed my own boxes?
Movers often argue that they are not responsible for internal damage to boxes packed by the customer unless there is visible outside damage. However, each case is fact-specific. If cartons arrived crushed, wet, or torn, document that. Some contracts and state rules address packed-by-owner boxes differently.
Should I accept a partial settlement payment?
Some carriers offer partial payments while leaving the rest of the claim open; others require a full release. Read the letter and any release form carefully. If you are unsure, ask whether accepting the payment will close your claim in full and consider getting independent advice.
Will filing a complaint with FMCSA make the mover pay more?
FMCSA does not order movers to pay individual claims. However, complaints can bring regulatory attention to a mover’s practices. Sometimes the possibility of scrutiny encourages companies to review disputes more carefully.
Do I need a lawyer for a moving damage dispute?
Not always. Many consumers handle smaller disputes themselves using the mover’s internal process, arbitration, or small claims court. For large losses, complicated legal issues, or if you are unsure about your rights, consulting a qualified attorney in your state can be helpful.
What if the mover’s inventory says my items were already scratched?
Inventory condition codes are often written quickly and may not match reality. If a mover relies on them to deny your claim, you can respond with pre-move photos, witness statements, and descriptions showing that the current damage is different in type or degree from any minor pre-existing wear.
Can I throw away damaged items after taking photos?
It is safer to keep damaged items until the claim is resolved or you have written permission from the mover to discard them. Adjusters sometimes want to inspect items in person. If you must discard something (for example, due to mold), take extensive photos and explain why it could not be kept.
What happens in moving claim arbitration?
Arbitration is usually a more informal process than court, where an independent arbitrator reviews written submissions from both sides and issues a decision. Rules vary by program. Some decisions are binding on the mover, and there may be caps on how much money the arbitrator can award. Your contract and the mover’s arbitration program documents explain the details.
Official sources & further reading
- FMCSA Protect Your Move – Federal guidance on choosing movers, understanding estimates, and handling complaints for interstate moves.
- FMCSA National Consumer Complaint Database – Portal to file complaints about interstate household-goods movers.
- 49 CFR Part 370 – Federal regulations on the processing of loss and damage claims for interstate carriers.
- 49 CFR Part 375 – Federal regulations governing transportation of household goods in interstate commerce.
- State consumer protection or public utilities commission websites – Many states publish specific rules and consumer guides for intrastate household-goods moves.
- Your bill of lading, tariff, and mover’s written claim procedures – These documents control deadlines, valuation options, and dispute resolution steps for your shipment.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.