When a move goes wrong, it usually happens fast: boxes arrive crushed, a table leg snaps off, or an entire carton is missing. In a matter of hours, you go from excited about your new home to angry, overwhelmed, and unsure what to do next. How you respond in the first days after delivery can make or break your moving damage claim.
Most movers will not pay for loss or damage just because you say something was broken. They will look at your paperwork, how quickly you reported problems, what photos and receipts you provide, and which valuation option you chose. If your file is weak or disorganized, you are more likely to see a low settlement or even a denial.
This guide walks you through a complete, step-by-step process to handle moving damage, missing items, and disputes with movers. You will learn how to document problems correctly, understand liability and valuation, calculate the amount you are claiming, respond to low offers, and escalate through complaints, arbitration, or small claims court when necessary.
This is general information based on common U.S. moving rules and industry practices, including federal guidance for interstate moves. Specific rights and deadlines depend on your paperwork, whether your move was interstate or intrastate, and your state’s laws. Always review your bill of lading, estimate, and tariff, and consult a qualified professional for legal advice about your specific situation.
Key takeaways
- Your bill of lading, estimate, inventory, and valuation election control what the mover may owe you, not verbal promises.
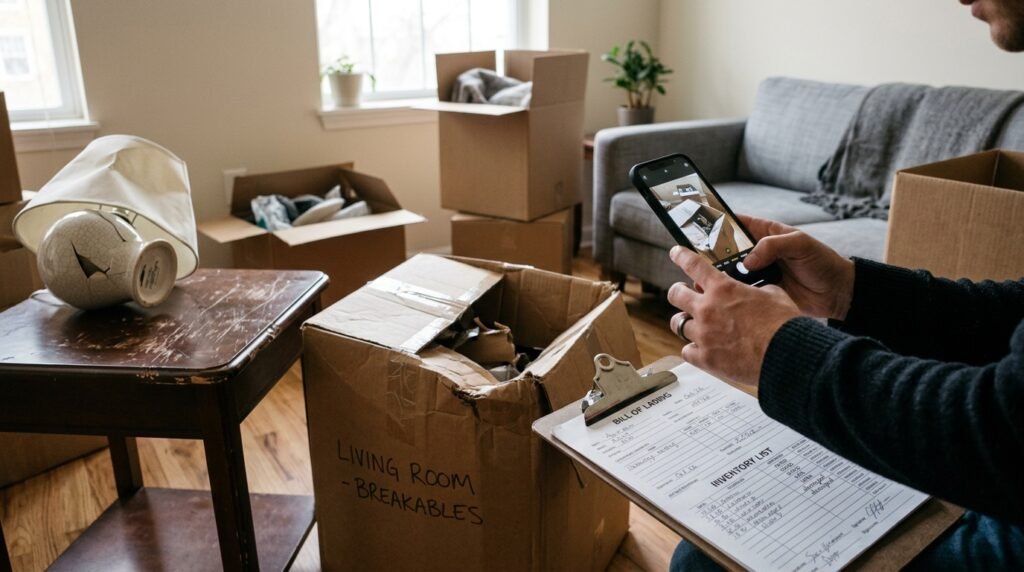
- Document damage and missing items immediately with clear photos, video, delivery notations, and a detailed inventory.
- Deadlines matter. Many movers require written claims within a set period; check your paperwork and carrier tariff.
- Understand which valuation option you chose (released rate vs. full-value) before calculating what to demand.
- Support your claim with receipts, repair estimates, and replacement links instead of guessing values.
- Be skeptical of quick, low settlements or releases that waive further rights, especially if you have not fully inspected items.
- If negotiations stall, you may escalate through the mover’s arbitration program, FMCSA complaints, state agencies, or small claims court.
Understanding mover liability and valuation
Before you argue with a mover about money, you need to understand what they promised to cover. Household-goods carriers are not automatically responsible for every dollar of damage you experience. Their liability is defined by federal or state rules and by the valuation option you selected in your moving paperwork.
Interstate vs. intrastate moves
Most cross-state (interstate) household moves are governed in part by federal law and regulations overseen by the Federal Motor Carrier Safety Administration (FMCSA). These rules address topics like required documents, estimates, and claims processes. Federal rules often reference concepts found in the Carmack Amendment, which establishes a carrier’s liability for loss and damage in interstate commerce.
Moves that take place entirely within one state (intrastate or local moves) are instead governed by state law and the rules of state agencies such as public utilities commissions or consumer protection offices. Some states largely mirror federal concepts; others have specific rules and deadlines. Always review your bill of lading and any tariff or terms attached to your estimate.
Valuation options: released rate vs. full-value
Most interstate movers must offer at least two valuation options:
- Released rate valuation (often 60 cents per pound per article) – the lowest level of protection, usually included at no extra charge.
- Full-value protection (or another higher level valuation) – you pay more, but the carrier’s potential liability is closer to the item’s actual value, subject to limits and exclusions.
These choices are typically presented on the bill of lading or a separate valuation election form. Your initials and signature show which valuation you picked.
| Valuation type | How liability is calculated | Typical result |
|---|---|---|
| Released rate (e.g., $0.60/lb) | Weight of item in pounds × per-pound rate, regardless of actual value | Low payouts on light, high-value goods (TVs, electronics, decor) |
| Full-value protection | Repair, replacement with similar item, or cash up to valuation limit, minus deductible if any | Higher payouts but subject to exclusions, item caps, and documentation |
| State-specific options (intrastate) | Varies by state tariff or statute; may follow similar structure to federal rules | Must review state rules and mover’s tariff closely |
Many consumers mistakenly call released rate coverage “insurance.” It is not an insurance policy for your benefit; it is a limited liability level for the carrier. Separate third-party insurance, if you purchased it, is a different product with different rules.
Typical exclusions and limitations
Carriers often limit or exclude liability for certain situations, especially under full-value protection. Common examples (always check your own paperwork) include:
- Items packed by owner (PBO) where there is no visible damage to the carton.
- High-value items not separately listed when required.
- Mechanical or internal failure of electronics without visible external damage.
- Perishables, hazardous materials, or prohibited items.
- Ordinary wear and tear, pre-existing damage, or inherent vice (fragility) of certain items.
Knowing these limitations helps you frame your claim, anticipate arguments, and decide where to focus your evidence.
What documents matter for your claim
Your paperwork is the backbone of your claim. Claims adjusters and arbitrators will rely heavily on the written record, not just what you remember. Gather all documents you received before, during, and after the move.
Core moving documents
- Bill of lading (BOL) – The main contract of carriage. Shows valuation choice, pickup and delivery dates, and terms and conditions.
- Order for service or written estimate – Describes services, estimated charges, and sometimes notes on special items.
- Inventory sheets – Lists each item or carton, often with condition codes at origin and exceptions at delivery.
- Weight tickets (for some interstate moves) – Show shipment weight, sometimes relevant to valuation limits.
- Receipts and invoices – For the move itself, packing materials, and any third-party services (e.g., crating, hoisting).
Delivery-related documents
- Delivery receipt – Often part of the inventory or BOL. This is where you should note obvious damage or shortages at delivery.
- Exception sheets – Forms where the driver or crew record damage noticed on delivery.
- Emails or texts with the dispatcher or driver about delays, damage, or access problems.
Claim-specific documents
- Carrier claim form – Many movers require use of their own form or online portal for formal claims.
- Repair estimates – From furniture refinishers, appliance technicians, or other specialists.
- Purchase receipts – For high-value items, electronics, and recently purchased furniture.
- Replacement price printouts – Screenshots or printouts from reputable retailers showing current replacement costs.
| Document | Why it matters | Common issues |
|---|---|---|
| Bill of lading | Shows contract terms, valuation, and sometimes claim deadlines or arbitration info. | Customer signs without reading; later surprised by valuation limits. |
| Inventory sheets | Help prove items were loaded, conditions at origin, and exceptions at delivery. | Illegible codes, missing pages, or no copy given to customer. |
| Repair estimates | Support claimed repair costs and whether replacement is more economical. | Mover disputes high estimates or insists on using their own vendor. |
Start a dedicated folder (physical and digital) and store all of these records together. This will save time and help you present a credible, organized claim.
First steps on delivery day
Delivery day is often chaotic, but what you do while the crew is present can shape the outcome of your dispute months later. Slow the process down just enough to protect yourself.
Inspect before signing
- Walk through your home as items come off the truck.
- Look for crushed cartons, opened boxes, or visible damage to furniture.
- Check that key pieces (bed parts, dining table top and legs, TV) arrive and are assembled.
- Open a few boxes in each room, especially those with fragile or valuable items.
Do not let anyone rush you into signing the delivery paperwork without at least a basic inspection.
Note visible damage and missing items on the paperwork
When the driver presents the delivery receipt or inventory pages for your signature, carefully note any problems in writing. Use clear language, such as:
- “Sofa torn on right arm, carton #23 crushed, box #41 missing.”
- “Headboard deep scratch, dining table leg broken, TV screen cracked.”
Keep a photo of the signed pages that show your notations. This can be powerful evidence that damage happened during the move, not later.
What not to do on delivery day
- Do not sign any document that says you received items “in good condition” if you see obvious damage.
- Do not sign a blanket release or settlement that offers quick cash in exchange for waiving future claims, unless you fully understand the impact and have inspected everything.
- Do not argue or become abusive with the crew. Calm, specific notes on your paperwork usually help more than heated words.
Documenting damage and missing items
Once the truck leaves, your main job is to document every problem clearly. Strong evidence can overcome a weak valuation level; weak evidence can sink a strong legal position.
Photographs and video
- Take wide shots of the room showing where the item sits.
- Take close-ups of the damage, from multiple angles, in good lighting.
- Photograph the entire item, not just the damaged area, so it is clearly identifiable.
- For cartons, photograph the box, shipping labels, and any crush damage or punctures.
- Turn on date stamps or keep the original file metadata if possible.
Written description checklist
For each damaged or missing item, create a written entry that includes:
- Inventory number (if any)
- Item description (brand, model, size, color)
- Approximate purchase date
- Approximate original price
- Current condition description and specific damage (scratches, cracks, dents)
- Whether the mover packed it or you did
- Location in the home at delivery
Example wording for your notes:
“Inventory #87 – Samsung 55″” LED TV, purchased 2019 for approximately $650. Packed by mover in original box. On delivery, screen was shattered with spider-web cracks in the upper-right quadrant and the unit will not power on.”
Evidence for missing items
Missing items are often harder to prove than visible damage. Use a combination of documents and photos:
- Flag items or cartons marked as “not located” or “short” on the delivery inventory.
- Compare origin and destination inventory pages to show the item was loaded but not delivered.
- Provide photos of the item in your old home (if available).
- Include receipts or bank statements proving you owned the item.
| Claim type | Most persuasive evidence | Extra tips |
|---|---|---|
| Visible damage to furniture | Photos before and after move (if available), close-up photos, repair estimate, origin and destination inventory notations. | Highlight any notes of “good” at origin vs. damage at delivery. |
| Broken electronics | Photo of undamaged packaging, external damage to carton, written statement that unit worked before move, technician diagnosis if available. | Avoid powering on repeatedly if there is visible damage; this can worsen the condition. |
| Missing carton | Inventory page showing carton number at pickup, delivery receipt noting shortage, detailed contents list from you. | Describe high-value contents separately within the lost carton. |
Organizing your claim file
Carriers and adjusters take organized claims more seriously. A clean file also helps you later if you need to go to arbitration or court.
Set up a simple system
- Create a main folder on your computer or cloud storage labeled “[Mover Name] Claim – [Month Year].”
- Make subfolders: Photos, Receipts, Estimates, Paperwork, Emails.
- Save every email as a PDF and file it by date.
- Rename photo files with simple titles: “dining-table-scratch-1.jpg” instead of random numbers.
Create a master item list
A spreadsheet or table works well for tracking each claimed item and the evidence you have. Include these columns:
- Item number
- Inventory tag (if any)
- Item description
- Type of loss (damaged/missing)
- Original price and year purchased
- Claimed amount (based on valuation rules)
- Photos available? (Y/N)
- Receipt available? (Y/N)
- Repair estimate? (Y/N)
- Notes (e.g., “Packed by mover,” “Noted on inventory at delivery”)
| Item # | Item description | Evidence checklist |
|---|---|---|
| 1 | Dining table, oak, 6 ft, broken leg | Photos (Y), Receipt (N), Estimate (Y), Inventory tag #45, delivery exception noted. |
| 2 | Carton #23 (kitchen), missing | Inventory page (Y), Photos of similar cartons (Y), Detailed contents list (Y). |
Calculating the amount of your claim
Once you have documented all problems, you must figure out how much to claim, based on the valuation option and supporting documents. This is where many consumers either overreach or undervalue their losses.
Repair vs. replacement
Under many full-value protection programs, the mover (or its insurer or valuation provider) may choose among:
- Paying for reasonable repairs;
- Replacing the item with a similar item of like kind and quality; or
- Paying a cash settlement based on repair or replacement cost, sometimes minus depreciation or deductibles.
For moderate damage (such as a scratched table or cracked dresser drawer), a quality repair estimate is often enough. For severe damage (shattered glass, broken frames, crushed furniture), replacement may be more realistic.
Released rate calculations
If you are limited to released rate (for example, $0.60 per pound per article for interstate moves), your claim math will be very different. You will need approximate item weights.
Example: A 100-pound dresser destroyed in transit with a released rate of $0.60/lb:
- 100 lbs × $0.60 = $60 maximum liability, even if the dresser cost $800.
For a 25-pound flat-screen TV:
- 25 lbs × $0.60 = $15 maximum liability, even if the TV cost $500.
Full-value example with depreciation
Some full-value programs adjust for age and condition. While practices vary, a simple example helps illustrate the idea:
| Item | Original cost & age | Possible settlement logic |
|---|---|---|
| Sofa (good quality) | Paid $1,200 five years ago; expected useful life 10 years. | Half of useful life remaining → approx. $600 actual cash value; repair estimate $350 → mover might pay $350 for repairs if feasible. |
| Washer | Paid $700 three years ago; expected life 8 years. | 5 years of life left (5/8 of value) ≈ $437.50. If repair is more expensive, settlement may be close to this ACV amount, depending on rules. |
Not all carriers use the same depreciation formulas, and some state rules restrict certain practices. The key is to support your numbers with receipts, product pages, and clear reasoning, then be prepared to negotiate.
Depreciation and valuation in practice
Depreciation is a way of recognizing that most household goods lose value over time. Using it correctly can help you build a realistic and defensible claim.
Typical depreciation by category (illustrative only)
Every carrier and jurisdiction may treat depreciation differently, but many adjusters roughly view useful life like this:
- Electronics: 3–5 years
- Mattresses: 5–8 years
- Sofas and upholstered furniture: 7–10 years
- Wood furniture: 10–15+ years depending on quality
- Appliances: 8–12 years
To approximate current value, you can divide the age by the expected life and apply that percentage to the original cost. Always label this as your estimate, not a guaranteed rule.
Using depreciation to support, not hurt, your claim
- Be honest about age; inflating age or cost can hurt credibility.
- Explain if an item was rarely used and in excellent condition despite its age.
- For unique or heirloom pieces, emphasize that market value may differ from simple formulas.
- Attach online listings for used or comparable items to show realistic current value.
Filing the claim with the mover
Once your evidence, item list, and calculations are ready, you are prepared to formally submit your claim. Many consumers wait too long or submit incomplete information, giving the carrier an easy excuse to delay or reduce payment.
Check deadlines and procedures
Look at your bill of lading, tariff, and any move confirmation documents. For many interstate moves, carriers require written notice of claims within a certain number of days, and a complete written claim within a longer period. Intrastate moves may have different or shorter time limits set by state rules or the mover’s tariff.
If your mover uses a specific claim form or online portal, use it. Some movers reject or delay claims that do not follow their listed procedure, although they still must comply with applicable law.
What a “written claim” usually needs
While definitions vary, a written claim typically must:
- Be submitted by the shipper or an authorized person.
- Describe the property that is lost or damaged.
- Assert that the carrier is responsible.
- Request payment of a specific or determinable amount.
Here is example wording you could adapt to your situation:
“This letter constitutes my formal claim for loss and damage arising from my household goods shipment under Bill of Lading #123456. I am claiming compensation for the items listed in the attached schedule, which were either damaged or not delivered. Based on the valuation provisions in my moving documents, I request payment in the total amount of $3,275.40 for repair and replacement.”
Submission checklist
- Completed carrier claim form or detailed letter.
- Copy of bill of lading and delivery receipt.
- Itemized list with claimed amounts.
- Photos and videos of damage.
- Repair estimates and/or replacement price printouts.
- Receipts or proof of purchase where available.
- Any relevant emails or texts acknowledging problems.
How movers and claim departments respond
After you submit your claim, the mover or its third-party claims administrator will review your file. For interstate moves, carriers often have a set time window in their tariff or in federal rules for acknowledging and resolving claims, though these timeframes can vary.
Typical stages of carrier response
- Acknowledgment – A letter or email confirming receipt of your claim and assigning a claim number.
- Request for more information – They may ask for missing documents, additional photos, or clarification of amounts.
- Inspection – They might send an inspector or repair vendor to examine damage in person.
- Settlement offer or denial – A written decision explaining what they will pay or why they are denying certain items.
Common carrier arguments
Expect the mover to raise issues like:
- Pre-existing damage or normal wear and tear.
- Poor packing when items were packed by you.
- Insufficient documentation of ownership or value.
- Limitations under your chosen valuation level.
- Exclusions for items not allowed or not disclosed as high value.
Your organized file, clear photos, and consistent story are your best tools to counter these arguments.
Responding to low settlement offers
It is common for the first settlement offer to be lower than you expect. Sometimes the calculation is correct under the rules; other times the carrier has misapplied valuation limits, misread your documents, or simply relied on weak internal estimates. You do not have to accept the first offer.
Evaluate the offer line by line
Ask the carrier for a detailed breakdown of how they valued each item. Then create a side-by-side comparison.
| Item | Your claimed amount | Carrier offer & reasoning |
|---|---|---|
| Oak dining table | $650 (repair estimate) | $250 – “scratches only, minor cosmetic damage” |
| TV 55″ LED | $475 (depreciated value) | $15 – released valuation 25 lbs × $0.60/lb |
In this example, you might challenge the table valuation with stronger photos and repair opinions, but you may have little room to move on the TV if you indeed chose released rate coverage.
How to write a strong counteroffer
When responding to a low offer, stay factual and reference your evidence. Avoid emotional language and threats. Example wording:
“Thank you for your settlement letter dated May 15, 2026 regarding Claim #7890. I appreciate your review but cannot accept the proposed amount as full and final settlement. For the oak dining table (Item #1), your offer of $250 does not reflect the professional repair estimate of $650 from ABC Furniture Repair (attached) or the extent of the structural damage shown in Photos 5–9. I request that you reconsider and adjust the allowance for this item to the full repair amount of $650.”
You can go item by item, explaining why your figure is more consistent with the paperwork and the valuation rules you agreed to.
Common mistakes that weaken claims
Understanding typical missteps can help you avoid them and strengthen your position from the start.
| Mistake | Why it hurts your claim | Better approach |
|---|---|---|
| Waiting months to inspect items | Mover may argue damage happened after delivery or that you missed deadlines. | Inspect essentials within days and submit written notice as soon as you discover issues. |
| Accepting quick cash on delivery | You may sign away further rights before discovering more damage. | Avoid signing releases until you fully understand the scope of loss. |
| Submitting only a few photos | Adjuster may downplay severity or question your story. | Provide multiple angles, overall and close-up shots, plus written descriptions. |
| Claiming unrealistic values | Undermines your credibility and invites heavy depreciation. | Base values on receipts and current market prices, adjusted for age and condition. |
When and how to escalate a dispute
If you have gone through the carrier’s claim process, responded to their offer, and still cannot reach a fair resolution, you may need to escalate. The right path depends on whether your move is interstate or intrastate, the amount in dispute, and what your paperwork says.
Internal appeal or second review
Before moving outside the company, ask in writing for a higher-level review of your claim. Briefly summarize the key issues and attach your strongest documents.
Arbitration programs
Many interstate household-goods carriers are required to participate in a neutral arbitration program for certain disputes, including loss and damage claims and some billing issues. Your bill of lading or mover’s brochure should describe how to access arbitration, deadlines, and whether it is binding.
- Arbitration decisions are usually based on written submissions and documents.
- There may be filing fees, sometimes recoverable if you prevail.
- Arbitrators look closely at contracts, inventories, photos, and correspondence.
FMCSA and state complaints
For interstate moves, the Federal Motor Carrier Safety Administration operates the National Consumer Complaint Database, where you can report unsafe or deceptive practices. While FMCSA will not resolve your money dispute like a court, complaints can trigger investigations and help regulators spot patterns.
For intrastate moves, state consumer protection agencies or public utilities commissions often accept complaints, can pressure companies to comply with rules, and may provide mediation services in some states.
Small claims court or attorney review
If the amount in dispute is significant to you and other options do not resolve the matter, you can consider:
- Small claims court – Designed for relatively modest disputes with simpler procedures. Each state has its own dollar limits and rules.
- Attorney consultation – A lawyer experienced in transportation or consumer law can review your documents and explain your options, including whether litigation is realistic.
Court and arbitration outcomes are never guaranteed. However, building a clean, well-documented file from day one improves your chances in any forum.
Protecting yourself on your next move
Even if your current claim is still unresolved, you can use what you have learned to protect yourself in the future.
Before booking
- Verify the mover’s USDOT and MC numbers (for interstate moves) on FMCSA’s website.
- Read reviews for patterns involving damage, claims, and settlement behavior.
- Request written estimates from at least two or three carriers.
- Ask detailed questions about valuation options and claim procedures.
Before packing
- Photograph high-value items and rooms in your old home.
- Decide which items the mover should pack, particularly fragile or high-value goods.
- Consider third-party insurance if your belongings are valuable and mover valuation limits are low.
- List items that may need special handling or custom crating.
On move day and delivery day
- Review the bill of lading and valuation election carefully before signing.
- Keep your own list of cartons and high-value items.
- At delivery, note any obvious damage or missing items on the paperwork.
- Store all documents together so you can access them easily for any future claim.
Frequently asked questions
How long do I have to file a claim after my move?
Deadlines depend on your paperwork, the mover’s tariff, and whether your move was interstate or intrastate. Many interstate carriers require written notice within a set period and a complete written claim within several months, but you should check your bill of lading and any attached terms for the specific time limits that apply.
What if I signed the delivery receipt but discovered damage later?
Signing the delivery paperwork does not automatically waive your right to file a claim, especially for concealed damage you could not reasonably see at delivery. However, failing to note visible damage can make your claim harder to prove. Document issues as soon as you discover them and submit written notice promptly.
Can I still recover if I chose the 60 cents per pound option?
If your bill of lading shows released rate valuation (commonly $0.60 per pound per article), the mover’s liability is usually limited to that amount, even for expensive items. You can still file a claim, but potential payouts on light, high-value goods will be low. Strong documentation helps you obtain the full allowed amount but does not change the underlying limit.
Do I need receipts for every damaged item?
Receipts are helpful but not always required. You can support value with a combination of partial records (like bank statements), photos of the item in use, online listings for comparable goods, and a reasonable explanation of age and condition. High-value or disputed items are much easier to win if you have receipts or other strong proof of purchase.
Should I let the mover’s repair vendor fix my furniture?
Movers often have preferred repair vendors. You generally can allow an inspection and repair, but you are not required to accept poor-quality work. Take photos before repairs, ask for the repair scope in writing, and keep invoices. If you believe the proposed repair will not restore the item to a reasonable condition, explain why and support your position with an independent estimate.
What if the mover denies my claim completely?
If the carrier denies your claim, ask for a written explanation that cites specific contract terms, valuation rules, or evidence. Review the reasons carefully, compare them to your documents, and consider responding with a focused rebuttal. If the dispute remains unresolved, you may use the carrier’s arbitration program, file complaints with FMCSA or state agencies, or discuss options with an attorney or small claims advisor.
Can I claim emotional distress or inconvenience?
Most household-goods claim processes and arbitration programs focus on direct property loss and damage, not emotional distress, lost work time, or general inconvenience. While you can describe the impact the move had on you, expect the monetary resolution to be limited to damaged or missing belongings and related charges allowed by your contract and applicable rules.
Will filing an FMCSA complaint get my money back?
The FMCSA complaint system is designed to collect information about unsafe or potentially unlawful practices, not to act as a court. Filing a complaint can put pressure on a carrier and help regulators monitor patterns, but FMCSA does not typically order movers to pay specific claim amounts. Your property claim is usually resolved through the mover’s process, arbitration, or the courts.
Do I need a lawyer to handle my moving damage claim?
Many consumers handle claims on their own by following the steps in this guide and carefully organizing evidence. However, if the dollar amount is substantial, the legal issues are complex, or you are considering litigation beyond small claims court, consulting a qualified attorney can help you understand your rights and strategy. An attorney may also be useful if you believe the mover engaged in fraud or severe misconduct.
What if my move was international?
International household moves involve additional treaties, carriers, and insurance options, and often rely on separate marine or cargo insurance policies. Liability rules can be very different from U.S. interstate moves. In that situation, review your international shipping contract and insurance policy and consider consulting a professional experienced in international relocation claims.
Official sources & further reading
These resources provide additional background on your rights and the rules that may apply to your household move, especially for interstate shipments:
- FMCSA Protect Your Move – Federal information on choosing a mover, understanding estimates, and consumer rights.
- FMCSA National Consumer Complaint Database – File complaints about interstate household-goods movers and brokers.
- 49 CFR Part 370 – Principles and practices for the investigation and voluntary disposition of loss and damage claims – Federal regulation related to claims handling for certain carriers.
- 49 CFR Part 375 – Transportation of household goods in interstate commerce – Rules for interstate household-goods movers, including information brochures and some claim-related requirements.
- State consumer protection agencies or public utilities commissions – Check your state government website for intrastate moving rules and complaint procedures.
- Your bill of lading, tariff, and mover’s claim form – These contract documents explain valuation options, deadlines, and any required arbitration program.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.