When a move goes wrong, it can feel like your entire life is upside down. Boxes arrive crushed, furniture is scratched or broken, items are missing, and the moving company suddenly gets very quiet. You know you should “file a claim,” but you do not know where to start, what to say, or how to protect your rights.
What you do in the first days and weeks after a problem move can make a major difference in the outcome. Timely photos, organized documents, and clear written communication often matter more than how angry you feel on delivery day. Movers, insurance partners, and adjusters look at your paperwork and evidence long before anyone hears your story.
This guide walks you through how to handle a problem move step by step — whether you are facing damage, lost items, delayed delivery, a low settlement offer, or a dispute about what you signed. You will learn how to organize your file, calculate what you are owed under your valuation coverage, respond to the mover's claim process, and decide when to escalate to agencies, arbitration, or legal help.
This is general information about U.S. household-goods moves. Rules can vary for interstate, intrastate, local, military, corporate, and international shipments. Always review your bill of lading, estimate, tariff, and claim form instructions, and consider getting legal advice for serious or complex disputes.
Key takeaways
- Start by preserving evidence: photos, videos, inventory pages, and delivery receipts matter more than verbal complaints.
- Locate your bill of lading, estimate, and valuation election; these documents control most of your financial recovery.
- Write a clear, organized claim with item-by-item details, proof of value, and realistic repair or replacement amounts.
- Know the mover's deadlines and procedures from the tariff and claim form, but do not wait until the last minute to file.
- Expect the claims handler to apply depreciation, valuation limits, and exclusions; build your file to respond with facts.
- If a settlement offer seems unreasonably low, negotiate in writing with stronger evidence before considering escalation.
- Use FMCSA complaints, state agencies, and arbitration programs strategically when ordinary claim discussions break down.
What counts as a problem move?
A “problem move” can mean many different things. Knowing how your issue fits into common patterns helps you plan your strategy and your evidence.
Typical categories of problem moves
| Problem type | What it looks like | Main focus of your claim |
|---|---|---|
| Physical damage | Scratches, dents, broken legs, shattered glass, water damage, crushed boxes | Condition before vs. after, repair vs. replacement cost, valuation limits |
| Missing or lost items | Boxes never delivered, inventoried items not on the truck, partial contents missing | Proof you tendered the items, inventory documentation, value support |
| Delay and extra expenses | Shipment days or weeks late, hotel and meal costs, missed work | Delivery spread, guaranteed dates, tariff rules on delay liability |
| Billing and estimate disputes | Final cost far above estimate, surprise fees, hostage load threats | Type of estimate (binding/non-binding), written tariff charges, receipts |
| Claim handling disputes | Low offers, long delays, partial denials, misapplied exclusions | Evidence quality, valuation math, escalation options |
Many moves involve more than one category: damaged items plus missing boxes plus a surprise bill. You do not have to solve everything on day one, but you should separate problems by type so you can gather the right documents and evidence for each.
First steps in the first few days
The first days after delivery are critical for preserving your rights and creating a strong record. Even if you are exhausted, take a few focused steps before you fully unpack.
Step 1: Protect and photograph the scene
- Stop the driver from rushing you through paperwork. Take the time you need to walk through obvious damage.
- Do not discard broken pieces, packing materials, or crushed boxes yet; they are useful evidence.
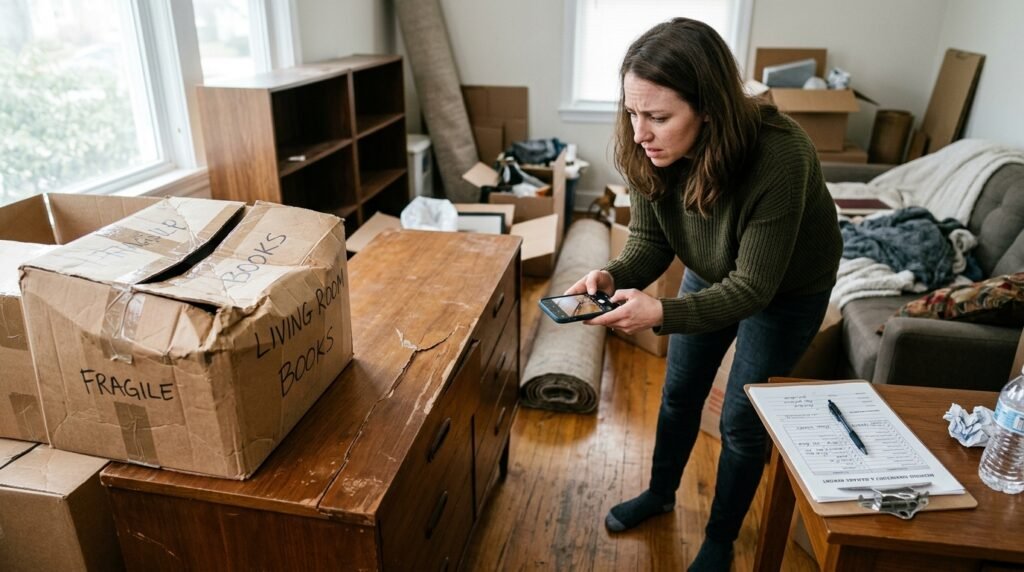
- Use your phone to take wide shots of entire rooms, then close-ups of each damaged item from several angles.
- Include photos of labels or model numbers for electronics and appliances, if visible.
- If items are wet or at risk of further damage, move them to a safe area after documenting how they arrived.
Step 2: Make brief delivery-day notations
If you still have access to the driver's delivery paperwork or electronic tablet, add short factual notes about damage or missing items. Do not argue or write emotional statements.
Example wording for delivery comments: “Several boxes crushed, dining table leg broken, sofa torn; customer will inspect further and file written claim.”
Step 3: Gather all moving documents in one place
- Bill of lading (the main contract and receipt for the shipment)
- Order for service and written estimate
- Inventory sheets (household goods descriptive inventory)
- Valuation/coverage election form (released value vs. full-value protection)
- Pickup and delivery receipts or weight tickets (for long-distance moves)
- Email confirmations and text messages about dates and charges
Put copies in a clearly labeled folder (digital and/or paper). You will reference these documents repeatedly as you build your claim.
Step 4: Check for claim instructions and deadlines
For interstate moves, many carriers follow claim rules based on federal regulations such as 49 CFR Part 370 and 49 CFR Part 375, plus their published tariff. Intrastate moves often follow state-specific rules. Your bill of lading or claim form usually explains:
- How long you have to submit a written claim (for example, 9 months from delivery for many interstate carriers, but this can vary)
- Where and how to submit (online portal, email, mail, or a third-party claims company)
- What must be included (inventory numbers, photos, estimates, receipts, etc.)
- Any separate process to dispute the mover's final offer (arbitration, small claims, etc.)
Mark these dates in a calendar. Do not rely on verbal statements about deadlines.
Key documents that control your claim
Understanding the documents you already signed is central to handling a problem move. They define the mover's liability, your valuation coverage, and the rules for resolving disputes.
Core documents for most household moves
| Document | Why it matters | What to review |
|---|---|---|
| Bill of lading | Main contract; shows carrier, shipment details, and key terms | Pickup/delivery dates, valuation level, signatures, special notations |
| Household goods inventory | Lists items loaded, with pre-existing damage codes and tag numbers | Whether your missing/damaged items were listed, and noted condition codes |
| Estimate and order for service | Controls price expectations and certain charge disputes | Binding vs. non-binding, services promised, packing responsibility |
| Valuation/coverage election | Sets the mover's maximum liability (for example, full-value vs. $0.60 per pound) | Box checked, any declared value amount, optional deductibles |
| Tariff or terms & conditions | Detailed rules the mover uses for claims, charges, and disputes | Claim deadlines, exclusions, arbitration language, delay policies |
If anything is missing, ask the mover in writing to provide a complete set of your shipment documents. Keep a copy of your request and their response.
Spotting key valuation elections
How you elected valuation (sometimes called “coverage” or “level of liability”) is often the single most important factor in a problem move:
- Released value (often $0.60 per pound per article) — very low protection; usually included at no additional charge for interstate moves unless you paid for more.
- Full-value protection (FVP) — mover agrees to repair, replace, or pay the current market replacement value of lost or damaged items, up to a declared shipment value, possibly with a deductible.
- Third-party insurance — sometimes sold separately; governed by its own policy rather than only by moving regulations.
If the mover marked a box that you do not recognize or that conflicts with what you were verbally promised, note this now. It may become part of a later dispute, especially in misrepresentation or sales-practice complaints.
How to document damage and missing items
Your photos, videos, and lists are the foundation of your case. Claims examiners usually never see your home or the actual damaged items. They rely completely on what you submit.
Photographing and filming effectively
- Take photos in good light without heavy shadows or glare.
- Include at least one photo that shows the entire item and where the damage is located.
- Then add close-ups of the damage from multiple angles (side, above, and straight on).
- Photograph serial numbers, labels, or maker's marks for higher-value items.
- Take at least one photo that includes the damaged item with its box or packing material, if possible.
- Record short videos to show issues that are hard to photograph (wobbly legs, sticking drawers, electronics that will not power on).
Describing damage in writing
Claim forms often have limited space. Use short, factual descriptions that answer: what was the item, what happened, and where is the damage?
Sample wording for damage description: “Item 42 – Wooden dining chair (dark walnut) – rear left leg cracked at joint during transit; previously stable and uncracked.”
Documenting missing items
- Compare the delivery inventory against the pickup inventory. Look for tag numbers or boxes not checked off as delivered.
- Note whether the driver marked certain items as “PBO” (packed by owner) or "CP" (carrier packed). This can affect how the mover views carton losses.
- List each missing item or box, including approximate contents and value.
- Explain where the items were stored at origin and whether the crew saw or packed them.
- If the mover made any comments about boxes not fitting on the truck, partial loads, or items moving on a later truck, record those statements in a dated note to yourself.
Preserving damaged items
Do not throw away damaged items or repair them before the claim is resolved unless doing so is necessary to prevent further loss (for example, mold). Many movers reserve the right to inspect items or pick them up if they pay replacement value under certain valuation levels.
If you must dispose of something for safety reasons, take extra photos and, if possible, keep a small sample (for example, a broken piece of glass with the pattern).
How to organize your evidence file
A messy claim with scattered emails, unsorted photos, and improvised lists is easier for a mover to minimize or deny. Treat your move like a small case file.
Suggested folder structure
| Folder | Contents | Tips |
|---|---|---|
| 01 – Contract & valuation | Bill of lading, estimate, valuation election, tariff pages | Highlight valuation choices and any special notations. |
| 02 – Inventory & receipts | Inventory sheets, purchase receipts, appraisals, warranty cards | Rename files with item names for easy search. |
| 03 – Photos & video | Before and after photos, videos of damage | Create subfolders by room or by claim item number. |
| 04 – Estimates & repair | Repair quotes, emails with repair shops, online replacement links | Note which estimate corresponds to which item. |
| 05 – Communications | Emails, letters, complaint filings, notes of phone calls | Include dates and names for each interaction. |
Item-by-item summary spreadsheet
Create a simple spreadsheet or table listing every damaged or missing item. Columns might include:
- Item description and brand
- Inventory tag number (if any)
- Room and box number
- Type of loss (damage, missing, both)
- Original cost and purchase date (if known)
- Claimed repair or replacement cost
- Photos file name(s)
- Notes about valuation, pre-existing condition codes, or mover comments
This summary lets a claims examiner review your case quickly and can make your claim appear more credible and organized.
Valuation, liability, and what the mover may owe
Your feelings about the move are not what determine compensation. The mover's liability usually comes from a mix of federal or state rules, the Carmack Amendment for many interstate moves, and the specific valuation you chose.
Basic concepts
- Liability — the mover's legal responsibility for loss or damage to your goods while they were in their custody, with certain exceptions.
- Valuation — the level of protection and maximum dollars per pound or per shipment that you agreed to in the contract.
- Exclusions and defenses — situations where the mover says it is not liable (for example, acts of God, inherent vice, inadequate packing in some scenarios).
Comparing common valuation levels
| Valuation type | How it usually works | Example outcome |
|---|---|---|
| Released value (e.g., $0.60/lb) | Mover pays up to a small amount per pound per item, regardless of actual value. | 50 lb TV lost at $0.60/lb = $30 maximum, even if it cost $700. |
| Full-value protection (FVP) | Mover agrees to repair, replace with like kind and quality, or pay replacement value, up to shipment value limit and subject to deductible. | Same TV lost; mover may pay current replacement cost or provide equivalent TV, minus any deductible. |
| Third-party insurance | Separate insurance policy; claims handled under insurance rules, not just mover's tariff. | Coverage may include more scenarios but require detailed proofs and deductibles. |
Always confirm which valuation or insurance applied at the time of pickup. If you have full-value protection, read the fine print on:
- Any deductible (for example, $250 or $500 per shipment)
- Maximum per-article limits
- Special rules for high-value items (sometimes requiring advance written lists)
- Whether the mover can choose repair instead of replacement
Calculating and supporting your claim amounts
Once you know your valuation level, you can calculate realistic dollar amounts. You do not have to be a professional appraiser, but you must be reasonable and able to show how you reached your figures.
Gathering value evidence
- Original purchase receipts or invoices (paper or email)
- Credit card or bank statements with transaction details
- Online listings for the same or comparable item (same brand, model, size, condition)
- Professional appraisals for antiques, artwork, or high-value items
- Written repair estimates from qualified shops
Handling depreciation
Many movers and claims companies will apply depreciation for age and wear, especially when your valuation or insurance allows payment of “actual cash value” instead of pure replacement cost. They may also argue that some items had pre-existing damage or normal wear and tear.
While each company uses its own guidelines, the following table shows an example of how depreciation might be considered in practice (not a rule, just an illustration):
| Item type | Approx. useful life | Example depreciation approach |
|---|---|---|
| Basic sofa | 7–10 years | Older sofa may receive partial value rather than full replacement. |
| Television | 5–7 years | Fast-depreciating electronics may receive lower ACV vs. original price. |
| Mattress | 7–10 years | Heavywear or older mattresses often valued at a fraction of new cost. |
You can push back on excessive depreciation by documenting good condition before the move (photos, cleaning receipts, low usage) or by showing current market prices for similar used items.
Building a claim calculation table
For your own use — and sometimes to attach as an exhibit — create a simple table or spreadsheet like this:
| Item | Original / current value (A) | Valuation or weight cap (B) |
|---|---|---|
| Dining table (solid wood) | $900 current replacement estimate from retailer | Under FVP, up to $900 (subject to deductible and repair option) |
| Box of books (40 lbs) | $250 estimated used value for titles | Released value: 40 lbs x $0.60 = $24 maximum claim |
This clarifies where valuation limits will restrict your recovery and where you should focus your negotiation efforts.
Filing your claim with the mover or claims company
Most carriers require that loss and damage claims be made in writing, within a specific timeframe, and include enough detail to identify the shipment and the items involved. Verbal complaints usually do not count as formal claims.
Before you submit
- Confirm the deadline and submission method from the bill of lading, tariff, or carrier website.
- Make sure you have at least basic information for each item: description, inventory number, nature of loss, your claimed amount.
- Prepare your supporting documents (photos, receipts, estimates) in labeled files, ready to upload or attach.
- Draft a short cover letter or email summarizing the scope of the problem.
Sample cover letter wording
“This letter serves as my formal written claim for loss and damage to shipment number [number], transported by [carrier name] from [origin] to [destination] with delivery on [date]. I have attached an itemized list of all damaged and missing items, together with supporting photographs, receipts, and repair estimates where available. Please confirm receipt of this claim and advise if you require any additional documentation under your tariff or claim procedures.”
Filing options
Depending on the mover, you may be asked to:
- Complete an online claim form with uploads for each item
- Fill out a PDF or paper claim form and mail or email it with attachments
- Submit through a third-party claims handling service that the mover contracts with
Whatever the method, keep copies of everything you submit, including any confirmation page or claim number.
How movers and claims departments typically respond
Understanding typical claim-handling behavior can help you stay realistic and persistent.
Common stages of claim handling
| Stage | What usually happens | Your best move |
|---|---|---|
| Acknowledgment | Carrier or claims company confirms they received your claim, assigns a claim number. | Save the acknowledgment; verify the claim number in all future communications. |
| Initial review | Examiner checks valuation, deadlines, and inventory; may request more documents. | Respond promptly with any requested info; keep responses factual and organized. |
| Investigation | They may contact the driver, review photos, and apply internal guidelines for depreciation and liability. | If long delays occur, send polite status requests in writing every few weeks. |
| Offer/denial | They make a settlement offer item-by-item, or deny some or all parts of the claim. | Compare their math to your valuation; prepare a written response if you disagree. |
Federal regulations give carriers a certain amount of time to acknowledge and reply to claims for interstate moves, often based on 49 CFR Part 370, but internal practices vary. Always check your specific carrier's policy.
Handling low settlement offers and denials
Many consumers are shocked by the mover's first offer. It may be much lower than your claimed amount, especially under released-value protection or when the company applies heavy depreciation or exclusions.
Analyze the offer line by line
- Compare each item on the offer or denial letter to your claim list.
- Note the reason given for reductions (weight limits, age, pre-existing damage codes, packing responsibility).
- Check that the mover applied the correct valuation type and math.
- Verify that weights used for released-value calculations are reasonable for the item's type and size.
Build a targeted response, not a general complaint
Instead of simply saying, “This offer is unacceptable,” point to specific errors or unfair assumptions.
Sample negotiation wording: “For Item 14 (queen platform bed), your offer of $45 appears to be based on released-value liability. However, my bill of lading and valuation election form both indicate full-value protection with no deductible. I have attached an additional screenshot from [retailer] showing a current replacement cost of $620 for the same model. Please review this item again under the correct valuation level.”
If the company denies an item based on pre-existing damage codes, mispacking by the customer, or an exclusion, you can respond with:
- Photos showing the item in good condition before the move (if available).
- Evidence that the mover actually packed the carton they now call “PBO” or that they did not warn you about improper packing.
- Clarification that the damage location does not match the claimed pre-existing mark.
When to accept, negotiate further, or escalate
There is rarely a perfect answer. Consider:
- Accepting when the offer is close to what you might reasonably expect under your valuation, and the cost and stress of escalation are not worth a small difference.
- Negotiating further when you see clear factual or mathematical errors and you can support your position with documents.
- Escalating (complaints, arbitration, legal review) when core items are denied or drastically undervalued and the dollar amounts justify more effort.
Communication strategy: what to say (and avoid)
How you communicate can strongly influence how your claim is perceived. You do not have to be friendly, but you should be precise and professional.
Best practices for written communication
- Use email or letters rather than phone calls when possible; written records are easier to prove later.
- Put your name, claim number, pickup and delivery dates, and origin/destination on every message.
- Stay factual. Stick to dates, item numbers, and documents, not speculation about motives.
- Attach supporting evidence directly to the email or reference exactly where it can be found in the claim portal.
- Keep your own log of dates sent and responses received.
Sample follow-up email
“On [date] I submitted a written claim for loss and damage to my interstate shipment, claim number [number]. Under your published procedures and applicable regulations, I understand that a decision should be made within a reasonable time. As of today, [days] days have passed. Please provide a written status update and advise whether any additional documentation is needed to complete your review.”
What to avoid saying too early
- Avoid admitting fault or agreeing you “must have packed badly” before a full review.
- Do not state that an item was already damaged unless you are absolutely sure; vague comments may be used against you.
- Be cautious about signing any general release, non-disparagement clause, or settlement agreement until you clearly understand what items and amounts it covers.
- Do not threaten lawsuits or public complaints in your very first message; this can harden positions instead of encouraging cooperation.
When and how to escalate your dispute
If the mover's offer is unreasonably low or they are not responding at all, you may decide to escalate. Escalation does not automatically mean going to court; several other tools exist.
FMCSA and federal complaint options (for interstate moves)
- FMCSA National Consumer Complaint Database — Allows you to log issues with interstate household-goods carriers and brokers. Complaints may not directly resolve your claim, but they can trigger enforcement interest if patterns appear.
- FMCSA “Protect Your Move” resources — Provide general guidance on consumer rights and red flags during moves.
State-level consumer assistance (intrastate and local moves)
For moves entirely within one state, state agencies often regulate movers, such as public utilities commissions, departments of transportation, or consumer affairs offices. Many accept complaints about:
- Unlicensed movers
- Overcharges beyond allowed tariffs
- Refusals to deliver goods without illegal extra payments
- Deceptive estimate or advertising practices
Arbitration programs and small claims court
- Some carriers participate in arbitration programs where a neutral arbitrator reviews the dispute. For interstate moves, federal rules require certain carriers to offer arbitration for some disputes, particularly about charges.
- Arbitration may be limited by your contract language (for example, a maximum dollar amount or certain types of issues).
- Small claims court is another option when the dollar amount is within the court's limit and you are willing to appear in person. Rules and limits vary by state.
Before you choose arbitration or court, read your bill of lading and any arbitration clause carefully, and consider getting legal advice if your claim is significant.
Common mistakes that weaken your case
Many problem moves become harder to resolve because of preventable missteps. Knowing these in advance can help you avoid them.
| Mistake | Why it hurts your claim | Better approach |
|---|---|---|
| Throwing away boxes and broken items immediately | Removes physical evidence the mover may want to inspect. | Keep items until claim is resolved, or document thoroughly before disposal. |
| Waiting months to submit any written claim | Risk of missing claim deadlines in tariff or contract. | Submit at least an initial written claim as soon as practical. |
| Sending only a general complaint with no itemized list | Claims may be delayed or minimized for lack of detail. | Provide an item-by-item list with claimed amounts and evidence. |
| Accepting verbal promises without written confirmation | Hard to prove later if staff changes or memories fade. | Follow up calls with short summary emails confirming what was said. |
Quick checklists you can follow
Immediate steps after a problem move
- Walk through the home during delivery and note visible damage.
- Take clear photos and short videos before moving items around.
- Mark obvious damage on delivery paperwork, if possible.
- Gather your bill of lading, estimate, inventory, and valuation form.
- Create a dedicated folder (paper or digital) for all move documents.
Before you file your written claim
- Prepare an itemized list of all damaged and missing items.
- Attach or organize supporting documents (photos, receipts, estimates).
- Confirm claim deadlines and correct submission address or portal.
- Draft a short, factual cover letter or email.
- Save a complete copy of everything you plan to submit.
When you receive a low offer
- Compare offer line-by-line with your claimed amounts.
- Review valuation type and math for each item.
- Highlight clear errors or unsupported assumptions.
- Gather any additional proof (new estimates, clearer photos).
- Send a professional written response explaining specific points of disagreement.
Before you sign any release or settlement
- Confirm which items are covered and which are excluded.
- Check whether the settlement is final or allows additional claims later.
- Understand any non-disparagement or confidentiality clauses.
- Verify the payment method and timeline.
- Consider talking with a lawyer if the amount is large or language is confusing.
Frequently asked questions
How long do I have to file a claim after a problem move?
It depends on your contract, tariff, and whether the move was interstate or intrastate. Many interstate carriers use a 9-month time limit from delivery for written claims, but you must check your bill of lading and claim instructions. Do not wait until the last month; submit as soon as you can reasonably document the loss.
Does taking photos really make a difference?
Yes. Photos and videos are often the strongest evidence you have. They show the condition of items on delivery, how they were packed, and the type of damage. Good visual documentation can counter claims about pre-existing damage or poor packing.
What if the mover says I packed the boxes badly?
Carriers sometimes deny or reduce claims for cartons marked “packed by owner.” You can still argue your case by showing that the outer carton was crushed or pierced (indicating handling issues) or by demonstrating that the mover actually did the packing. Clear photos and any written notes about who packed what can help.
Can I ask the mover for their internal claim rules?
You can request a copy of the mover's tariff provisions or written claim procedures. For many interstate carriers, these rules must be made available to customers. While you may not receive internal guidelines, the tariff and forms should explain deadlines, valuation options, and basic claim-processing standards.
What if I disagree with the mover's final offer?
You can negotiate in writing, pointing out specific errors and providing more evidence. If that does not resolve the issue and the amount is significant, you can consider filing complaints with FMCSA (for interstate moves), contacting state consumer agencies, using available arbitration programs, or exploring small claims court or legal advice.
Will complaining to FMCSA or a state agency force the mover to pay more?
Regulators typically do not order specific payment amounts on individual claims. However, complaints can encourage movers to communicate more seriously and may lead to enforcement actions if many consumers report similar behavior. Complaints are one tool in a broader strategy, not a guaranteed fix.
Do I need a lawyer for a moving damage claim?
Many smaller disputes are handled directly between consumers and movers without lawyers. For large losses, severe misconduct, possible fraud, or complex legal issues, consulting an attorney experienced in transportation or consumer law can help you understand your options and deadlines.
What happens if I miss the claim deadline?
If you miss the contractual or tariff claim deadline, the mover may deny your claim on that basis alone. In some cases, there may still be other legal or consumer-protection avenues, but they are harder to use. This is why documenting issues promptly and filing within the stated timeframe is so important.
Is full-value protection always better than released value?
Full-value protection usually provides much higher potential recovery for lost or damaged items, but it often costs more and may include deductibles or special rules for high-value items. Released value is cheaper upfront but can lead to very low payments. The best choice depends on your budget, the value of your belongings, and your risk tolerance.
Official sources & further reading
- Federal Motor Carrier Safety Administration (FMCSA) — Protect Your Move consumer resources
- FMCSA — National Consumer Complaint Database
- Code of Federal Regulations, 49 CFR Part 370 – Principles and practices for the investigation and voluntary disposition of loss and damage claims
- Code of Federal Regulations, 49 CFR Part 375 – Transportation of Household Goods
- Your move paperwork — bill of lading, written estimate, valuation/coverage election form, inventory sheets, and carrier claim instructions
- Your state's consumer protection office or public utilities commission (for intrastate move regulations and complaint processes)
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.