When your belongings arrive damaged, missing, or not at all, you have more than a bad moving day. You have a potential claim that will succeed or fail based on how well you document what happened. A strong moving damage claim file is your main tool to show what was lost, how it was packed and delivered, and what you are reasonably asking the carrier to pay.
Most people wait until they are upset with a low settlement offer before they start organizing their evidence. By then, critical photos, notes, and delivery-day details may already be lost. Carriers, adjusters, and arbitration programs tend to favor clear, well-documented files that follow the rules in your bill of lading, tariff, and applicable federal or state regulations.
This guide walks you step-by-step through how to build a strong moving damage claim file from the moment you notice a problem through settlement or escalation. You will learn what documents matter, how to track deadlines, what photos and estimates to get, how to calculate your claimed amount, and how to respond when the carrier disputes or underpays your claim.
This is general information about moving claims for U.S. consumers. It does not replace the specific terms in your moving paperwork or legal advice from an attorney. Rules can differ for interstate vs. intrastate moves, local moves, military or corporate relocations, and international shipments, so always review your contract and applicable regulations.
Key takeaways
- Your moving damage claim file is the full package of documents, photos, timelines, and estimates that show what happened and what you are claiming.
- Start building your file on delivery day: inspect items, note issues on the paperwork, and take clear photos before unpacking everything.
- Key documents include the bill of lading, inventory sheets, estimate, order for service, delivery receipt, and any valuation or insurance add-ons.
- Use written estimates, receipts, and online price references to support the dollar amount you claim, and understand how valuation limits and depreciation may apply.
- Organize your evidence so an outsider can follow it: one file per item with photos, inventory numbers, descriptions, and value support.
- Respond to low offers with facts, not emotion: point to specific documents, photos, and contract language in your claim file.
- Know your escalation options if the mover denies or underpays your claim, including carrier arbitration, FMCSA complaint tools, and state consumer agencies.
What a moving damage claim file really is
Your claim file is everything you would hand to a neutral decision-maker to explain your side of the dispute. Think about an arbitrator, small-claims judge, or a supervisor who has never met you. They will not be moved by how stressful your move was, but by organized evidence that matches the rules in your moving contract and applicable regulations.
In many cases, the carrier is liable under federal law (often the Carmack Amendment for interstate household-goods moves) or similar state rules, but only up to the valuation coverage you selected and subject to exclusions and deadlines. Your file needs to show:
- That the carrier received your items in good condition.
- That they were delivered damaged or not delivered at all.
- What each item is, its condition before the move, and its reasonable value.
- That you met the carrier's claim procedures and time limits.
The stronger and clearer your documentation, the easier it is for the adjuster to recommend payment within the carrier's liability limits.
Step 1: Know what kind of move you had
Before you can build the right claim file, you need to understand what rules apply. Different moves are subject to different laws, tariffs, and claim procedures.
Common U.S. move types and why they matter
| Move type | Typical rules | Why your file must reflect this |
|---|---|---|
| Interstate household-goods move (state to state) | Usually governed by federal rules, including FMCSA regulations and the carrier's tariff; liability often governed by the Carmack Amendment. | Deadlines and procedures often follow federal guidance and the carrier's written claim rules; arbitration is commonly required for disputes. |
| Intrastate move (within one state) | Typically governed by state law and state-approved tariffs; may involve a state public utilities commission or consumer agency. | Claim procedures and rights may be different from interstate moves; your file helps state regulators understand what happened. |
| Local move (within a metro area) | May be lightly regulated; terms in your contract can control many aspects of liability and claims. | Your file must clearly show what you agreed to in the contract and valuation add-ons because default legal protections may be weaker. |
| Military or corporate relocation | Often governed by separate contracts or programs with different claim rules and portals. | You may need to follow employer or government claim procedures in addition to carrier rules. |
Look at your bill of lading and estimate to see how your move is described and whether the mover is registered for interstate moves. For an interstate move, you can also look up the mover's U.S. DOT number on the Federal Motor Carrier Safety Administration (FMCSA) website.
- Action checklist:
- Locate your bill of lading or moving contract.
- Confirm whether origin and destination are in the same state.
- Identify any separate corporate or military relocation paperwork.
- Note any references to "arbitration," "tariff," or "claim procedures."
Step 2: Gather your core moving documents
The backbone of your moving damage claim file is your moving paperwork. This shows what services you agreed to, what valuation level you selected, and which items the mover recorded on the inventory.
Key documents to locate
- Signed estimate or quote (binding, non-binding, or not-to-exceed).
- Order for service or confirmation of services.
- Bill of lading (the contract of carriage).
- Household goods inventory sheets or electronic inventory.
- Valuation/coverage election form (e.g., full value protection or released value at 60 cents per pound per article).
- Pickup and delivery receipts, including any notations about damage or exceptions.
- Any emails, texts, or messages that change the agreement, delivery date, or valuation.
Why these documents matter
| Document | What it shows | How it helps your claim file |
|---|---|---|
| Bill of lading | Core contract; dates, addresses, valuation choice, special terms. | Establishes the carrier's responsibilities and limits of liability. |
| Inventory sheets | List of items, condition at origin (inventory codes), and tag numbers. | Helps prove the item was tendered to the carrier and any pre-existing notations. |
| Valuation form | Your coverage level and any deductibles or exclusions. | Sets the maximum the carrier may have to pay; guides your expectations. |
| Emails and texts | Changes to dates, promises, and service commitments. | Supports your story if there were delays, re-deliveries, or service failures. |
- Action checklist:
- Scan or photograph each document so you have digital copies.
- Save them in a folder labeled with the mover's name and your move date.
- Highlight or note key sections on copies (not the originals).
- Flag any written claim instructions and time limits.
Step 3: Inspect delivery and document damage
Inspection and documentation during and immediately after delivery are critical. Even if you have already received your goods, you can still strengthen your claim file by reconstructing what happened.
On delivery day: what to do while the crew is present
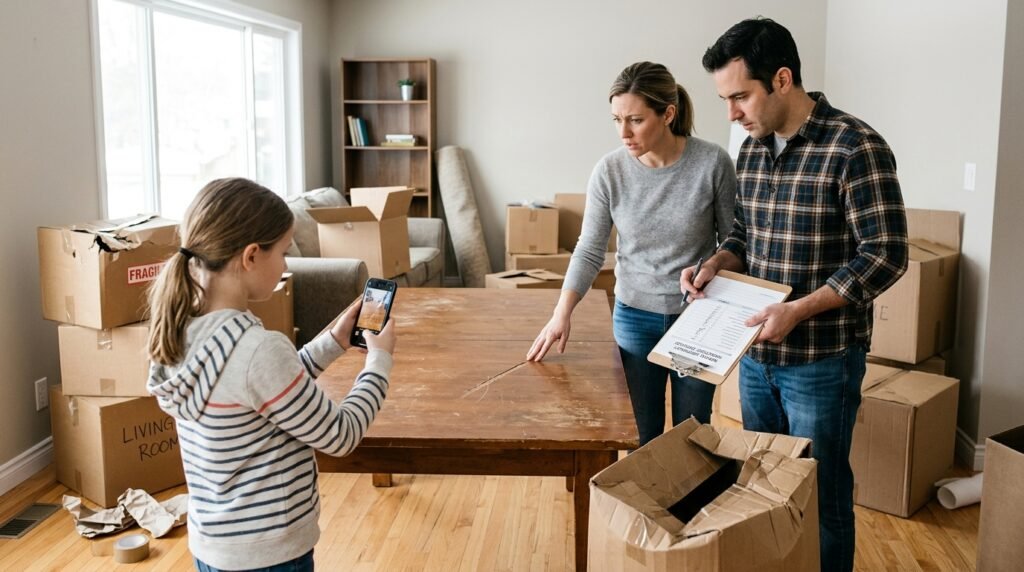
- Walk through your home as items come off the truck.
- Direct boxes and furniture to the correct rooms so problems are easier to find.
- Note any crushed boxes, torn wrapping, or broken pieces as you see them.
- Ask the crew to document visible damage or missing items on the inventory or delivery receipt.
- Before signing anything, read the delivery receipt for any "all items received in good condition" language.
If you find something clearly damaged during delivery, you can use wording like:
"I am noting visible damage to dining table leaves, chipped headboard, and crushed box #27 on the delivery paperwork. Full inspection will occur after unpacking."
After the crew leaves: first 24–72 hours
- Set aside a "claim table" or area to collect damaged items and packing materials.
- Open boxes starting with fragile and high-value items.
- Photograph damaged items before you repair, discard, or fully clean them.
- Photograph the damaged box, packing material, and any visible mishandling clues.
- Make a written list of issues as you uncover them, noting the date and time.
Do not rush to throw out packing materials or broken pieces. They may help show whether the carrier packed improperly or mishandled your shipment.
Step 4: Build your damaged and missing items list
Your claim file should include a clear, itemized list of everything you are claiming. Adjusters use this list as their roadmap, so make it detailed, consistent, and easy to follow.
Information to record for each item
- Item name and description (brand, model, color, size).
- Inventory tag number, box number, or other mover reference.
- Condition before the move (age, previous wear, any known issues).
- Type of problem (scratched, broken, missing parts, lost, late delivery, etc.).
- Approximate purchase date and original price, if known.
- Estimated weight, if valuation is weight-based.
- Photos and estimate references (photo file name, repair estimate number).
Sample item entry format
You can create a spreadsheet or table for your internal use. A simple way to describe an item in your written claim is:
"Item 3 – Samsung 55-inch LED TV, Model UN55XXXX, purchased 2019 for approximately $600. Listed on inventory tag #45. Arrived with cracked screen and dented frame. Non-operational. See Photos 5–8 and Estimate #2."
Lost or non-delivered items
For items that never arrived, your file should show that the mover received them and failed to deliver them.
- Identify the item on the inventory sheet (tag number, description).
- Note which room or box it was packed from at origin, if you remember.
- State clearly that the item was not delivered and has not been found.
- Include any emails or texts with the mover about searching for the item.
Step 5: Photos, video, and digital evidence
Photos and videos are often the strongest parts of a moving damage claim file. They can quickly show the severity of damage and how items were handled.
What to photograph
- The item as a whole, in context (e.g., TV on stand with visible cracks).
- Close-ups of the damage from multiple angles.
- Any identifying labels, serial numbers, or branding.
- Box labels, inventory tags, or numbers on damaged cartons.
- Packing material used (or not used) around damaged items.
- The location in your home where the item now sits, especially if property damage occurred (scratched floors, dented walls).
Best practices for usable claim photos
| Tip | Why it matters | How to apply |
|---|---|---|
| Good lighting | Prevents disputes about whether marks are shadows or real damage. | Use natural light where possible; avoid glare by shooting from different angles. |
| Multiple angles | Shows depth of a scratch or break, and overall impact. | Take a wide shot, then a medium shot, then close-ups. |
| Context images | Helps connect the item to its box, tags, and location in your home. | Include the box label or tag in at least one photo with the item. |
| File naming | Saves the adjuster time and reinforces your organization. | Name files like "Item03_TV_Photo1" instead of random phone names. |
- Action checklist:
- Create a digital folder for "Claim Photos."
- Take at least 3–5 photos per damaged item.
- Back up photos to cloud storage or an external drive.
- Record which photos go with which items in your item list.
Step 6: Estimates, receipts, and values
Even if liability is clear, carriers rarely pay amounts that are not backed by some form of value evidence. Your claim file should show how you arrived at the dollar amount you are requesting.
Types of value evidence
- Original receipts from when you purchased the item.
- Credit card or bank statements showing the purchase.
- Online product listings for the same or similar item (current replacement value).
- Repair estimates from local shops, contractors, or technicians.
- Written appraisals for artwork, antiques, or high-value items, if available.
Repair vs. replacement
Depending on your valuation coverage and the carrier's tariff, settlement may be based on repair cost, replacement cost, or a combination. For many full-value protection plans, the carrier may choose to repair, replace with a similar item, or pay you the current market value (sometimes subject to a deductible).
For basic "released value" coverage (often 60 cents per pound per article for interstate moves), your recovery may be limited to a small fraction of the item's replacement cost. Your claim file should still document the real value, but you should understand that the legal limit may cap payment.
Estimate and value tracking table
| Item | Evidence of value | Notes for claim file |
|---|---|---|
| Wood dining table | Local furniture repair estimate; similar table price from major retailer website. | Attach repair quote; note that repair is cheaper than full replacement. |
| Laptop computer | Original invoice; manufacturer website listing for current equivalent model. | Include serial number photo to link item to invoice. |
| Area rug | Online invoice email; screenshot of same rug currently sold online. | Explain if item is discontinued and show closest comparable. |
Step 7: Calculate and support your claim amount
Once you have your item list and value evidence, you can calculate your claimed amount. Your math should be transparent and consistent with your coverage type.
Key concepts: valuation and depreciation
- Valuation level: The maximum amount the carrier is responsible for, based on your selection at or before pickup (for example, full-value protection at a certain dollar amount per pound, or released value at 60 cents per pound per article).
- Depreciation: A reduction in value for age and normal use. Some programs pay "actual cash value" (replacement cost minus depreciation), while others pay full replacement cost.
- Weight-based limits: For released value, the carrier may multiply the item’s weight by the rate (e.g., 0.60) to arrive at a maximum payment.
Example: comparing claim calculations
| Scenario | Calculation method | Result for 50 lb item purchased for $800 |
|---|---|---|
| Released value at 60 cents per pound | 50 lbs x $0.60 per lb | Maximum liability of $30, even if the item cost $800. |
| Full-value protection, repairable damage | Cost of repair if less than replacement cost and within valuation limits. | If repair is $250, claim may be based on $250. |
| Full-value protection, total loss | Current replacement cost at time of loss, subject to plan and limits. | If comparable replacement is $750, claim may be based on $750. |
Sample claim amount entry
"Item 5 – Queen mattress. Purchased 2021 for $900 (see Receipt A). Current replacement cost for comparable model is $950 (see Exhibit 5A). Mattress arrived with large tear in fabric and structural damage; not usable. I am claiming $950 in replacement cost under my full-value protection coverage."
- Action checklist:
- Confirm your valuation level and any deductibles.
- Calculate a claimed amount for each item using consistent logic.
- Include a total claimed amount at the end of your item list.
- Make sure your total does not exceed any overall policy or valuation limits.
Step 8: Organize your claim file like an adjuster
Even strong evidence can be ignored if it is disorganized. Organize your claim file so that someone new to the dispute can follow the story quickly.
Suggested structure for your claim file
- Section 1 – Overview: cover page, your contact info, move details, and a short summary of the claim.
- Section 2 – Core documents: bill of lading, inventory, valuation election, estimate, order for service.
- Section 3 – Itemized claim list: table or list of each damaged or missing item with claimed amounts.
- Section 4 – Photos and media: index of photos by item number with file names or page numbers.
- Section 5 – Value evidence: receipts, estimates, and product listings organized by item.
- Section 6 – Correspondence: emails, texts, and letters between you and the mover or adjuster.
Paper vs. digital organization
You can maintain both a digital and a physical version of your claim file. Carriers often ask for electronic submissions, but you may be more comfortable reviewing a printed binder during phone calls or arbitration.
- Digital tips:
- Use a main folder with subfolders for "Documents," "Photos," "Estimates," and "Emails."
- Save files in PDF format when possible for easy sharing.
- Keep a log of what you sent to the mover and when.
- Paper tips:
- Use a binder with labeled tabs or dividers matching the sections above.
- Attach a simple index page listing contents.
- File new letters and notes immediately so nothing gets lost.
Step 9: Submitting a clear, complete claim package
Once your file is in good shape, you’ll prepare your formal claim submission. Carriers usually have specific requirements for how claims must be submitted and what information they must include. These instructions may appear in the bill of lading, tariff, or a separate claim form.
Check deadlines and procedures
Review your bill of lading, tariff summary, and any claim forms for:
- Time limit to file your claim (for example, a certain number of days from delivery).
- Time limit to bring suit or arbitration if the claim is denied.
- Required method of submission (online portal, email, mail, carrier app).
- Required information (item descriptions, dates, amounts, signatures).
If you are uncertain about a requirement, you can send a written question to the carrier asking them to confirm the correct process. Keep that correspondence in your file.
Sample claim cover letter wording
"I am submitting a claim for loss and damage arising from my household-goods move completed on [delivery date] under Bill of Lading #[number]. Attached is my itemized list of damaged and missing items, supporting photos, value documentation, and copies of my move paperwork. Please confirm receipt of this claim and advise if you need any additional information to evaluate it in accordance with your tariff and applicable regulations."
- Action checklist before you submit:
- Verify that every claimed item appears on your list with a claimed amount.
- Attach or reference supporting evidence for each item.
- Include your current mailing address, email, and phone number.
- Keep copies of everything you send, including mailing or submission confirmations.
How movers and claim departments typically respond
Once your claim is submitted, the carrier or a third-party claims company will review your file. Response times and procedures vary, but your organized documentation can influence how your claim is handled.
Common carrier response types
- Request for more information: They may ask for additional photos, estimates, or clarifications.
- Partial approval/offer: They agree with some items but reduce or deny others.
- Denial: They deny the claim in whole or in part, citing contract terms or alleged packing issues.
- Silence or delay: They do not respond within the expected timeframe.
Typical issues carriers raise
| Carrier argument | What they mean | How a strong file helps |
|---|---|---|
| "Pre-existing damage" | They claim the item was already damaged before shipment. | Origin photos and clean inventory notations can rebut this. |
| "Improper packing by owner" | They argue you packed the item poorly, so they are not liable under the tariff. | Photos of intact cartons, or evidence of carrier packing, can push back on this defense. |
| "Noted as scratched/chipped at origin" | They rely on condition codes on the inventory sheet to claim old damage. | Your description of increased or different damage, plus photos, helps distinguish new damage from old. |
When you receive a response, compare it carefully with your file. Note where they agree, where they dispute, and what evidence they rely on. This will guide your next steps.
How to counter low settlement offers
It is common for an initial offer to be lower than what you requested. A strong claim file gives you leverage to respond clearly and factually.
Steps to respond to a low offer
- Stay calm and organized. Emotional responses rarely help; your goal is to clarify the facts.
- Identify specific disagreements. List which items they underpaid or denied, with their reasons.
- Point back to evidence. For each disputed item, reference your photos, receipts, or estimates.
- Use contract language. If their position seems inconsistent with your valuation agreement or tariff summary, quote the relevant sections.
- Give a reasonable counter. You can maintain your original amount or, if appropriate, propose a compromise supported by evidence.
Sample response wording
"Thank you for your offer dated [date]. I appreciate your review; however, I disagree with the proposed amounts for Items 2, 5, and 9. For Item 5 (queen mattress), your offer of $120 appears to be based on released value at 60 cents per pound. My bill of lading and valuation election form, attached again as Exhibit A, show that I selected full-value protection. Current replacement cost for a comparable mattress is $950, as shown in Exhibit 5A. I respectfully request that you reconsider the settlement amount for this item in light of the documented coverage and evidence of value."
Common mistakes that weaken claim files
Many consumers unintentionally hurt their own claims by skipping key steps or failing to keep evidence. Understanding these mistakes helps you avoid them.
Mistake vs. better approach
| Common mistake | Why it hurts your claim | Better approach |
|---|---|---|
| Throwing away packing and broken pieces immediately | Destroys evidence of how the item was packed and the extent of damage. | Keep materials and broken parts until claim is resolved or carrier says otherwise in writing. |
| Not taking photos until after repairs or cleaning | Makes it hard to prove the original severity of the damage. | Photograph items as-found before cleaning, repairing, or discarding. |
| Relying only on verbal complaints | Verbal reports are easy to dispute and may not meet formal claim requirements. | Submit a written claim with clear itemization and supporting documents. |
| Missing claim deadlines | The carrier may deny the claim as untimely under the contract or regulations. | Review deadlines early and submit at least a preliminary written claim on time. |
- Quick self-check:
- Have you kept broken parts and packing materials?
- Did you take clear photos before any repairs?
- Do you have a written claim, not just phone calls?
- Are you within the mover's stated claim deadlines?
Escalation: FMCSA complaints, arbitration, and beyond
If you cannot resolve your claim directly with the mover, you may consider escalation options. Your well-prepared claim file becomes even more important at this stage.
Common escalation paths
- Carrier arbitration program: For many interstate moves, movers must offer a neutral arbitration program for certain disputes, especially those about loss and damage. You usually submit your claim file and any additional arguments to the arbitrator.
- FMCSA National Consumer Complaint Database: For interstate movers, you can file a complaint with the Federal Motor Carrier Safety Administration. This does not resolve your claim directly, but it can alert regulators to patterns of behavior.
- State consumer protection agencies: For intrastate or local moves, your state's consumer protection office or public utilities commission may accept complaints or have specific claim rules.
- Small claims court or attorney review: If permitted by your contract and local law, you may seek legal advice or file in small claims court. Your claim file serves as your evidence packet.
Always review your bill of lading and arbitration clauses to see whether arbitration is mandatory before going to court, and what deadlines apply.
What not to sign or say too early
What you sign and say in the early stages can affect how your claim is viewed. You do not want to accidentally waive rights or accept an unfair settlement.
Documents to review carefully
- Delivery receipts that state "all items received in good condition" when they are not. You can qualify your signature by noting visible damage or indicating "subject to further inspection."
- Release or settlement forms that require you to waive all claims in exchange for payment. Make sure the amount and terms are correct before signing.
- Blank or incomplete forms where details will be filled in later.
Phrases to avoid
- Admitting fault without knowing the facts (for example, "It was probably my packing" when you are not sure).
- Threatening language that could escalate conflict unnecessarily.
- Agreeing that your losses are "no big deal" when you intend to file a claim.
Staying organized until your claim is resolved
Claims, especially for large moves with many items, can take time. Staying organized and documenting ongoing communication can protect you if the dispute continues.
Maintain a communications log
- Date and time of each call, email, or message.
- Name and title of the person you spoke to.
- Short summary of what was discussed or promised.
- Follow-up actions you agreed to take, with deadlines.
Timeline overview for your claim file
| Stage | What you do | What to record in file |
|---|---|---|
| Delivery and first 72 hours | Inspect, photograph, and list damage; gather documents. | Initial damage notes, photos, delivery receipts with comments. |
| Claim preparation period | Obtain estimates, organize evidence, prepare itemized list. | Copies of estimates, receipts, correspondence with vendors. |
| Submission and review | Submit claim, respond to information requests, evaluate offers. | Proof of submission, carrier letters, your response notes. |
| Escalation (if needed) | File for arbitration or complaints, seek advice if appropriate. | Arbitration forms, regulator communications, final decisions. |
Related guides
Frequently asked questions
How long do I have to file a moving damage claim?
Deadlines depend on your contract, tariff, and whether the move was interstate or intrastate. Many carriers require written claims within a set number of days after delivery. Always check your bill of lading, any tariff summary provided, and the mover's written claim instructions. When in doubt, submit a written claim as soon as possible and keep proof of when you sent it.
What if I already signed the delivery receipt as "received in good condition"?
Signing a receipt that way can make your case harder, but it does not automatically erase your ability to claim concealed damage found later. Document what you discovered, when you discovered it, and why it was not obvious at delivery. Take photos and submit a written claim promptly, referencing your supporting evidence.
Can I repair or replace items before the claim is resolved?
You can, but you should document the damage thoroughly first and keep all receipts and estimates. Some valuation programs require the carrier to choose between repair and replacement, so check your paperwork or ask the mover before making irreversible decisions on expensive items. When repairs are necessary for safety or basic living, explain that clearly in your claim file.
Do I need a professional appraisal for every damaged item?
No. Appraisals are usually reserved for high-value, unique, or antique pieces where normal receipts or online listings do not reflect value well. For most everyday items, receipts, repair estimates, and current market listings are sufficient. However, if an item has special or unusual value, an appraisal can strengthen your file.
What if I packed some boxes myself?
When you pack your own boxes, carriers often argue "owner-packed" as a defense to loss or damage, especially if there is no visible external damage to the carton. You can still claim damage, but you strengthen your case by showing reasonable packing methods, photos of intact boxes, and evidence that the type of damage suggests rough handling or other issues in transit.
Is email enough to count as a written claim?
Often yes, but it depends on your contract and the carrier's procedures. Many carriers accept emailed or online-portal claims as long as they contain the required information. To be safe, format your email like a formal claim, attach your item list and supporting documents, and keep copies plus any automated confirmations.
Can I include emotional distress or inconvenience in my claim amount?
Most household-goods moving claim processes focus on physical loss or damage to property and certain service failures. They usually do not pay for emotional distress, stress, or general inconvenience. You can describe how the move affected you in your narrative, but expect settlement discussions to center on itemized property loss consistent with your valuation coverage.
What happens if the mover ignores my claim?
If the mover does not acknowledge or respond within the timeframe described in your contract or applicable rules, your organized file helps you escalate. For interstate moves, you can consider an FMCSA complaint and review the mover's arbitration program information. For local or intrastate moves, check with your state consumer-protection agency. In some situations, you may want to consult an attorney about additional options.
Do I need a lawyer to pursue a moving damage claim?
Most consumers start the process on their own using the carrier's claim procedures and, if available, arbitration. Whether to seek legal advice depends on the size of your claim, the complexity of the dispute, and your comfort with the process. This guide can help you build a strong file either way, so that if you later consult a lawyer, they have solid documentation to review.
What if my move was international?
International moves may involve different carriers, freight forwarders, and legal frameworks than U.S.-only moves. Liability, time limits, and procedures can be more complex. Your best approach is still to build a detailed claim file with the same elements covered here and then review your international shipping documents or consult a professional familiar with international household-goods claims.
Official sources & further reading
For more detail on mover responsibilities, consumer rights, and claim procedures, consult these official or authoritative resources:
- FMCSA Protect Your Move – Federal guidance on interstate household-goods moves, including consumer rights and mover obligations.
- FMCSA National Consumer Complaint Database – Online system to report problems with interstate movers and brokers.
- 49 CFR Part 370 – Federal regulations on the processing of loss and damage claims for certain carriers.
- 49 CFR Part 375 – Federal rules for the transportation of household goods in interstate commerce.
- Your state's consumer protection office or public utilities commission – Many states provide specific guidance for intrastate household-goods moves and complaint processes.
- Your signed bill of lading, tariff summary, and carrier claim form – The primary documents governing your particular move and claim.
This guide is general information, not legal advice. For a specific dispute, consult a qualified attorney or your state consumer-protection office.